
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did WuXi Biologics (Cayman) (SEHK:2269) Move Today?
WuXi Biologics (Cayman) (SEHK:2269) just cleared an unannounced two week U.S. FDA GMP inspection at its Wuxi Mashan site, covering multiple approved biologic products and reinforcing its role as a contract manufacturer to global partners.
That clean FDA outcome comes at a time when WuXi Biologics (Cayman) has been on a strong run, with the share price at HK$53.0 after a 60.41% three-month share price return and a 62.88% year-to-date share price gain. However, the five-year total shareholder return is still down 58.10%, indicating that while momentum has picked up recently, longer term investors remain in recovery mode.
Scan beyond WuXi Biologics (Cayman) and line up other quality-focused contractors in healthcare by running the curated list of solid balance sheet and fundamentals (202 results) against your own risk and return checklist.
WuXi Biologics (Cayman) has sprinted ahead, yet the share price still sits below both analyst targets and some fair value estimates. Is this renewed optimism already generous, or is it still too cautious?
Most Popular Narrative: 9% Undervalued
Against the HK$53.0 close, the most followed narrative pegs WuXi Biologics (Cayman) at a fair value of HK$58.22, so the current rally still screens below that anchor while sentiment rebuilds.
The accelerated ramp in ADC (antibody-drug conjugates) and bispecific/multi-specific project wins, which now make up over 40% of WuXi Biologics' portfolio and drive new, high-complexity business, positions the company as the partner of choice in these fast-growing biologics segments. This supports sustained backlog growth and provides strong visibility into higher late-stage and manufacturing revenues over the next 3-5 years.
See why 10 investors see WuXi Biologics (Cayman) as 9% undervalued.
Result: Fair Value of HK$58.22 (UNDERVALUED)
Still, the WuXi Biologics (Cayman) story depends heavily on international clients and remains exposed to potential US regulatory shifts that could unsettle long term earnings assumptions.
Find out about the key risks to this WuXi Biologics (Cayman) narrative.
Another View on WuXi Biologics (Cayman) Valuation
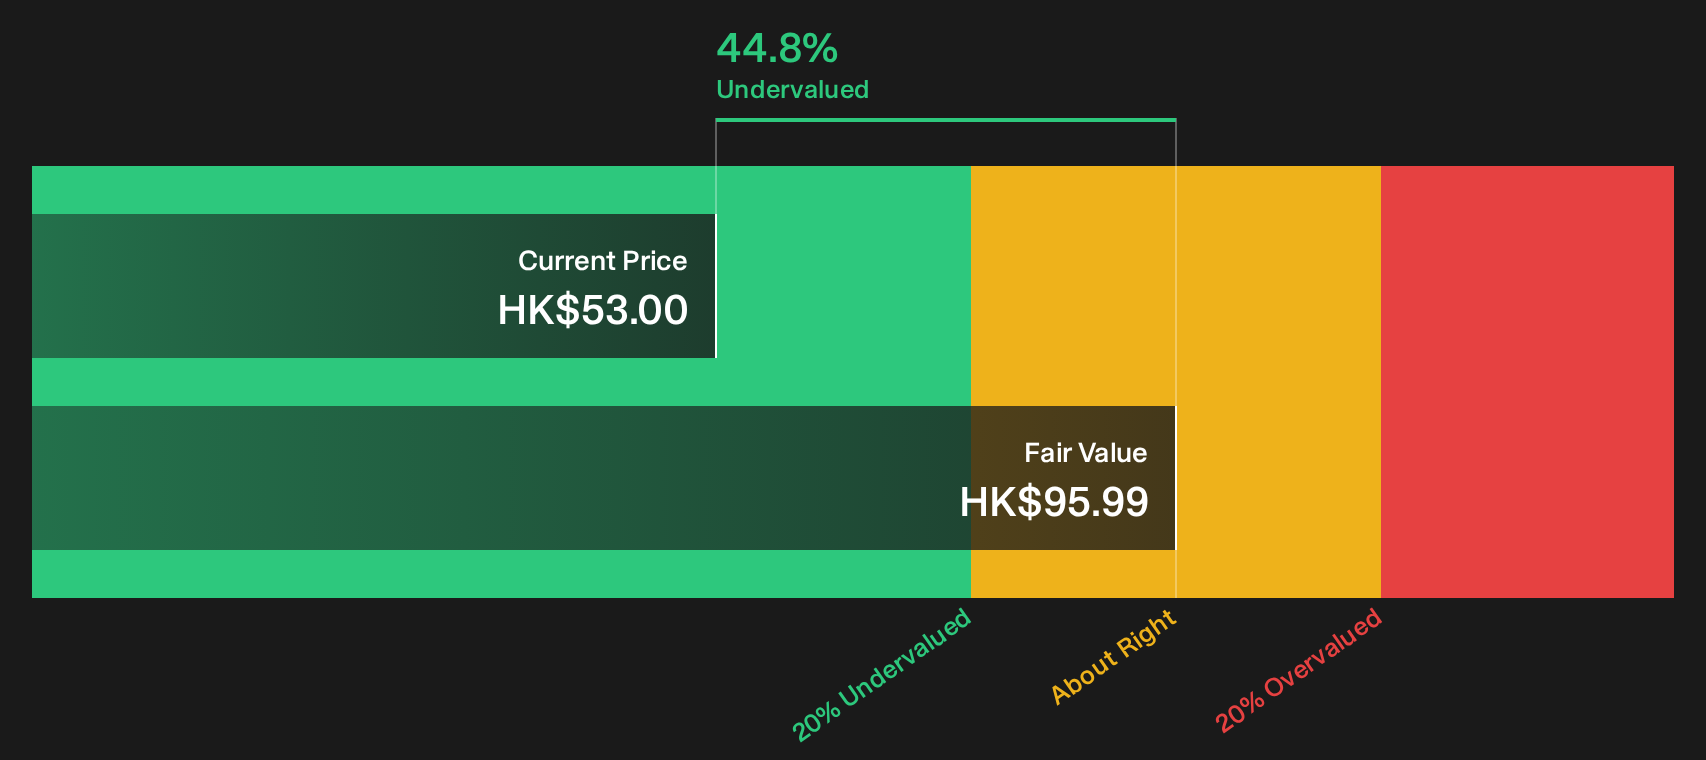
While the fair value narrative points to HK$58.22 and an undervalued WuXi Biologics (Cayman), our DCF model suggests an even larger gap. On that cash flow view, the shares trade at HK$53 against an estimated value of HK$95.99, which is also flagged as undervalued. If both point in the same direction, where do you think the bigger risk lies: in the forecasts, or in the price?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views remain on whether WuXi Biologics (Cayman) is priced fairly after this rally and valuation gap story. Move quickly, scrutinize the figures yourself, and weigh both the potential upside and the downside risks by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond WuXi Biologics (Cayman)?
If WuXi Biologics (Cayman) has sharpened your focus on quality, do not stop here. Fresh opportunities often sit just outside the stocks already on your radar.
- Target income resilience by scanning companies that pay higher yields and prioritise sustainability through the 162 dividend fortresses.
- Hunt for quality at a discount by using the 620 high quality undiscovered gems before the wider market takes notice.
- Dial down portfolio shocks by filtering for steadier performers with the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com