
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Compagnie du Cambodge (ENXTPA:CBDG) Faces A Fair Value Gap As Half Year Results Land
Compagnie du Cambodge (ENXTPA:CBDG) just posted half year 2026 results, reporting sales of €70 million compared with €66.2 million a year earlier, while net income declined to €16 million from €20.7 million.
The half year release lands after a mixed stretch for Compagnie du Cambodge shareholders, with the share price at €105.0 delivering a 9.38% year to date share price return. The 3 year total shareholder return of 81.40% signals strong longer term gains and suggests momentum has cooled slightly in recent months as investors weigh stronger sales against softer profitability.
Compare Compagnie du Cambodge's latest earnings swing with a curated list of solid balance sheet and fundamentals (202 results) that may handle profit pressure very differently.
Compagnie du Cambodge is priced at €105.0 after that mixed half year, yet the implied intrinsic value sits higher on current estimates. Is the recent pause a signal that the valuation gap is already closing?
Preferred Price-to-Sales of 45.2x: Is it justified?
On the current numbers, Compagnie du Cambodge trades on a P/S ratio of 45.2x, while the last close sits at €105. This is a rich valuation level in absolute terms and it raises a clear question for readers about what kind of future performance is being implied in that price.
The P/S multiple compares the market value of the equity to its revenue, so it effectively tells you how many euros investors are paying for each euro of sales. For a transportation and logistics business like Compagnie du Cambodge, this tends to reflect expectations about future profitability, pricing power and the stability of its income stream rather than current earnings alone.
Recent figures show profit margins at 18%, which is lower than the 40.9% recorded a year earlier. That compression in profitability sits alongside a valuation that our SWS DCF model currently judges as expensive, with the stock trading at €105 compared with an estimated future cash flow value of €18.78. It suggests the market is putting a heavy premium on the quality and persistence of earnings, even as reported income for the latest period is softer.
The comparison with peers is stark. Compagnie du Cambodge's P/S of 45.2x is described as expensive against a peer average of 2x, and even more so versus the broader European transportation sector at 0.7x. That gap implies investors are assigning a far higher revenue multiple to this stock than to similar businesses in the same industry.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 45.2x (OVERVALUED)
Still, a sharp pullback in profit margins or a reassessment of Compagnie du Cambodge's premium P/S relative to peers could quickly challenge this rich pricing story.
Find out about the key risks to this Compagnie du Cambodge narrative.
Another View on Compagnie du Cambodge’s Value
The SWS DCF model paints a very different picture for Compagnie du Cambodge. On that cash flow view, an estimated value of €18.78 per share compares with the current €105 price, which points to a stock that screens as heavily overvalued on this second yardstick.
When two valuation tools pull this far apart, it raises a simple question for you as an investor. Which set of expectations do you trust more: the premium revenue multiple the market is paying today, or the more conservative cash flow math underpinning the DCF model?
Look into how the SWS DCF model arrives at its fair value.
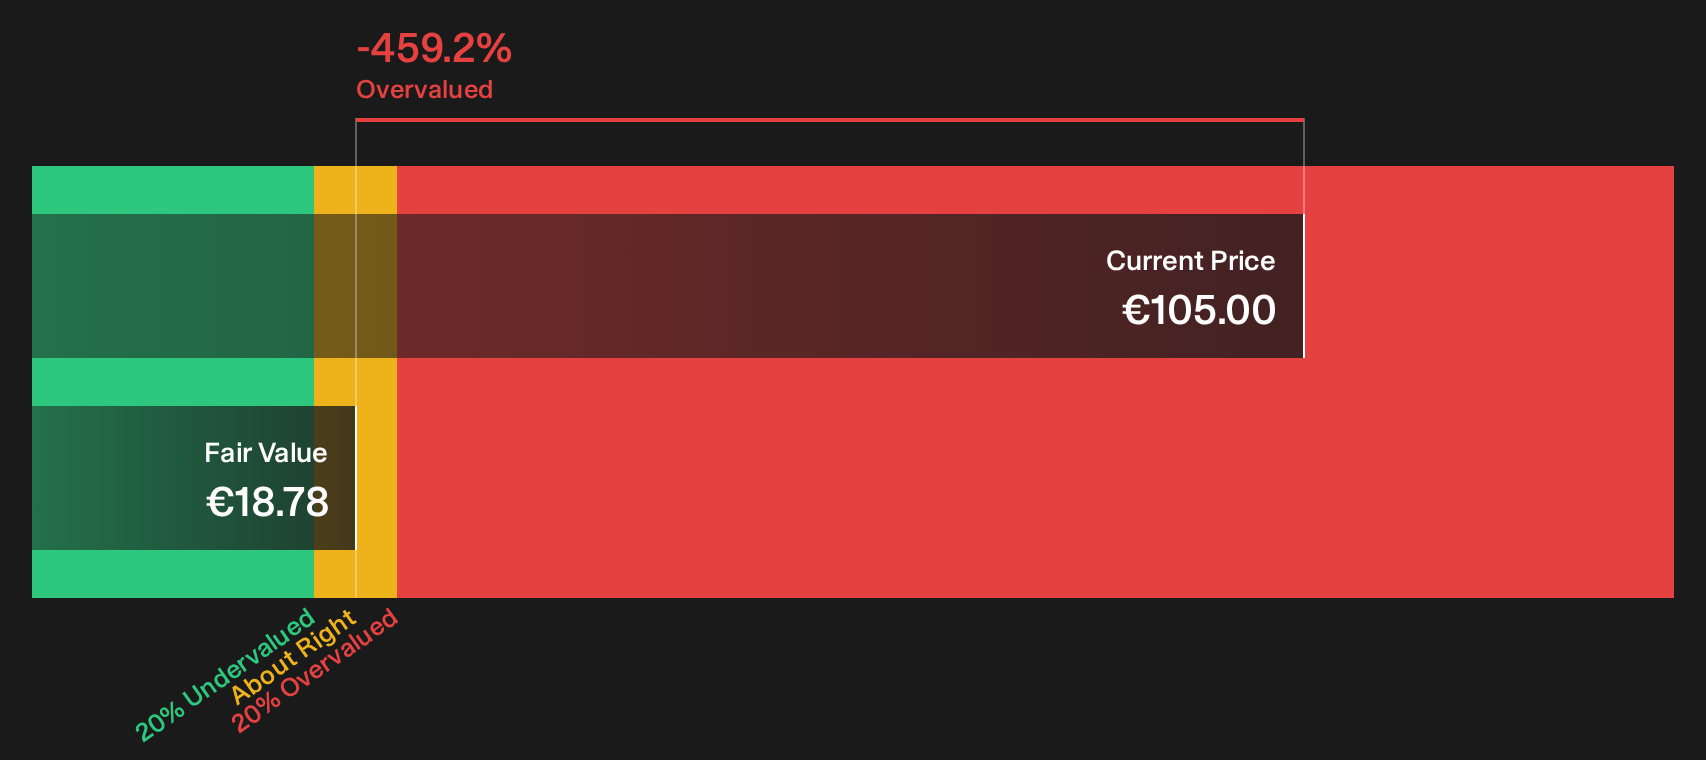
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Compagnie du Cambodge for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seen enough tension between Compagnie du Cambodge's premium pricing and the DCF math to feel uncertain about the next move? Take a closer look at the underlying data, then weigh that rich valuation against the fact analysts have already highlighted 1 important warning sign.
Looking for more Compagnie du Cambodge style investment ideas?
Do not stop your work with Compagnie du Cambodge. Use this as a reference point, then broaden your watchlist with focused stock ideas before the best options move away.
- Target resilient balance sheets by reviewing a curated list of solid balance sheet and fundamentals (202 results) that filters for companies with stronger fundamentals and financial cushioning.
- Hunt for mispriced opportunities through a focused 182 high quality undervalued stocks that highlights stocks combining quality metrics with more modest valuations.
- Prioritise stability and income by scanning a hand picked 227 resilient stocks with low risk scores built around businesses with lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com