
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shearwater Group And 2 British AI Stocks To Watch
Bill Ackman argues that AI is rewriting the old playbook for interest rates, because businesses see almost open ended potential returns from new technology. That debate matters for you. British AI related stocks linked to chips, cloud and ChatGPT style software may be priced as if nothing special is happening. This article walks through three ideas from an undervalued UK AI shortlist that could reward closer attention.
The three UK AI stocks below are only a sample, and the full screen has surfaced 2 more companies with equally compelling stories that are not covered here.
If you want to identify, compare and analyze the highest conviction AI ideas in one place, head straight to the Undervalued Artificial Intelligence/ AI Stocks screener.
Shearwater Group (AIM:SWG)
Overview: Shearwater Group provides AI driven Mind Security managed services alongside broader cybersecurity, managed security operations and identity software for global corporates.
Operations: Shearwater generates about £33 million from Services and £2 million from Software, with roughly £30 million coming from clients in the United Kingdom.
Market Cap: £14 million
Shearwater Group matters for this AI shortlist because its Mind Security offering plugs AI directly into day to day threat detection and response for clients already wrestling with ChatGPT era risks.
"Rising cybercrime, wider use of AI by attackers and tighter data regulation are prompting corporates and government departments to allocate more budget to cybersecurity."
What happens if one unseen pressure on Mind Security’s economics quietly shifts the balance between steady demand and sustainable profitability?
That hidden pressure point is exactly what the full narrative for Shearwater Group unpacks, separating temporary margin strain from shifts that could quietly reshape Shearwater Group’s long term economics.

Bytes Technology Group (LSE:BYIT)
Overview: Bytes Technology Group helps enterprises adopt AI and cloud by reselling software and hardware and delivering AI-focused IT services.
Operations: Bytes Technology Group generates about £220.6 million as an IT solutions provider, with roughly £211.9 million of revenue coming from United Kingdom customers.
Market Cap: £1.02b
Bytes Technology Group matters for this AI shortlist because its licensing, cloud and AI services are directly involved in the rollout of ChatGPT era tools across corporate IT budgets.
"The expansion of their cloud base in public and corporate sectors and strategic focus on AI-powered software products suggests potential for significant revenue growth as demand for these technologies increases."
What happens if one quiet shift in how key vendors reward AI centric licensing ends up tipping the balance on Bytes’ margins and growth expectations?
That inflection point is exactly what the full narrative for Bytes Technology Group lays out, highlighting where vendor incentives, AI uptake and risk around Bytes Technology Group may be quietly decoupling expectations from reality.

Satsuma Technology (LSE:SATS)
Overview: Satsuma Technology builds AI agents and subnet infrastructure that host and manage autonomous models and subnet alpha tokens for LLM-based services.
Operations: Satsuma Technology records about £0.05 million of revenue from computer graphics related services, all currently generated in the United Kingdom.
Market Cap: £23 million
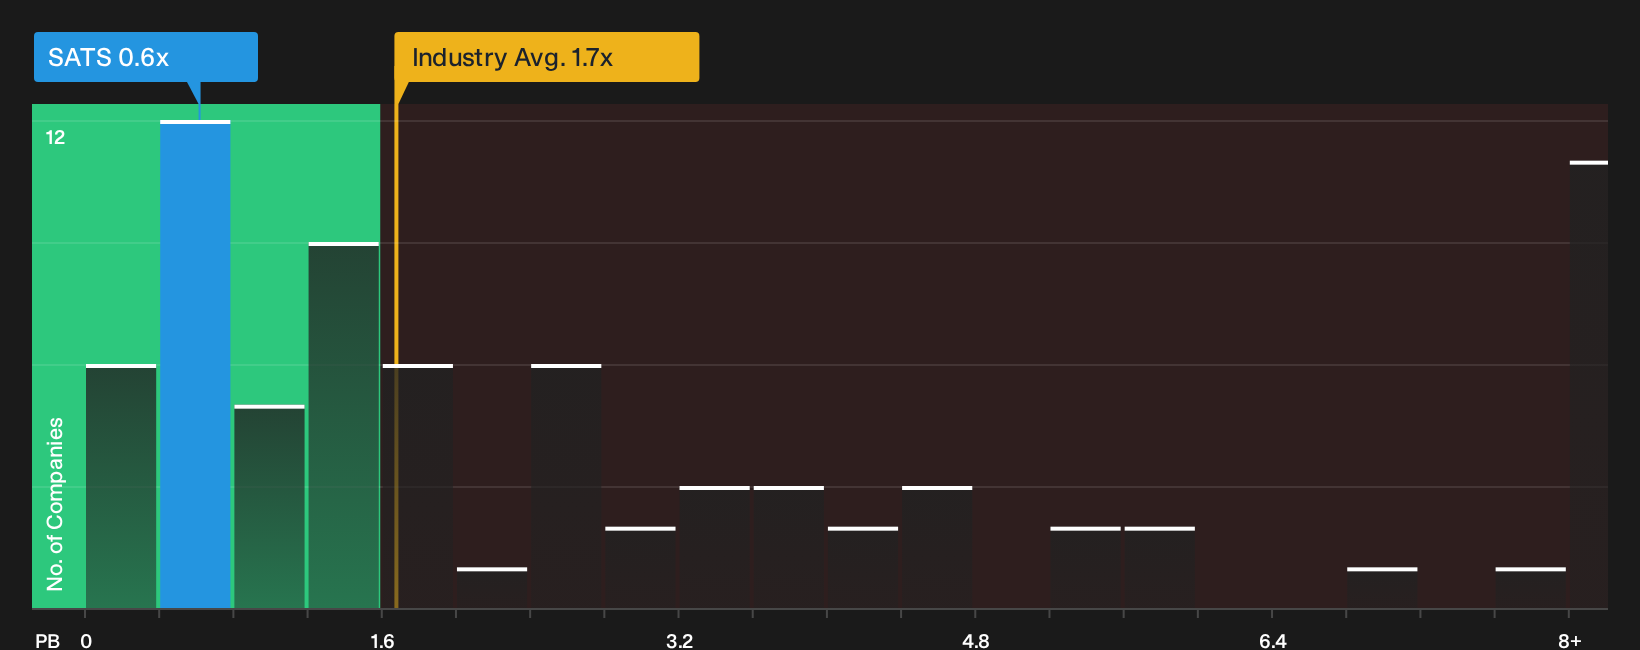
Satsuma Technology provides direct exposure to AI agents and subnet tooling that power ChatGPT style services. This is paired with very limited revenue, heavy losses and a suspended listing. The draw is a 0.6x P/B valuation inside a high profile theme, depending on how one unresolved funding constraint plays out.
That unresolved funding constraint is exactly where the analysis report for Satsuma Technology starts to unpack whether Satsuma Technology’s thin revenue base masks optionality or looming dilution risk
Seeking Fresh Alternatives Beyond AI?
Markets move fast, and the freshest breakout stories rarely stay under the radar for long. Scan new momentum before the crowd, while it matters, and get in early.
- Spot income workhorses built for staying power by reviewing 1 dividend fortresses that keep cash returning to shareholders while other payouts are dropping.
- Track future-facing infrastructure trends early by checking the 40 power grid technology and infrastructure stocks that could benefit as grids strain under rising AI and electrification demand.
- Hunt for resilient balance sheets before momentum really flies by scanning the list of solid balance sheet and fundamentals (10 results) that keep financial risk in tighter check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com