
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Smart Meter Growth Just Shift Siemens (XTRA:SIE) Investment Narrative?
- Recent industry reports point to strong projected growth in smart water management, industrial heating systems, smart meters, and digital software markets where Siemens is a key supplier, including its past partnership with CPFL Energia to modernize about 1.6 million smart meters in São Paulo by 2029.
- These sectors align closely with Siemens' focus on digital infrastructure and quality management tools. Expanding demand in these areas directly relates to how its core businesses may scale, generate service revenues, and deepen long term customer relationships.
- Attention now turns to how Siemens' role in smart grids and digital infrastructure could reshape the broader investment narrative for the company.
Scan beyond Siemens and size up other grid and infrastructure players that are riding the same digital and electrification themes with our hand picked 40 power grid technology and infrastructure stocks
Siemens Investment Narrative Recap
To own Siemens, you need to believe that demand for electrification, automation, and industrial software keeps pulling its core divisions forward while the large €117b order backlog supports visibility. The recent smart water, smart meter, PLM, QMS, and industrial heating reports mostly reinforce that Siemens is positioned in the right end markets rather than changing the story.
The key near term swing factor remains execution in Digital Industries and Smart Infrastructure, as customers weigh large projects against macro and regulatory noise. The biggest risk is still muted automation demand and fierce software competition, especially in China and Europe, which could pressure margins and slow the shift toward higher recurring digital revenues.
The CPFL Energia project in São Paulo, which targets about 1.6 million smart meters by 2029, is the clearest operational link to the smart metering and smart grid theme. It gives Siemens a live reference in a large emerging market, ties hardware to software, and supports the thesis that services and meter data management can deepen recurring relationships.
For catalysts, that deal matters less for headline revenue and more for proof that Siemens can win and execute complex grid digitalization work at scale. Smart meter and smart water management growth potential sits alongside PLM and QMS software as test cases for how well management turns industrial AI, SaaS, and electrification into stable, higher margin digital income while managing debt levels and integration risk.
Siemens' current analyst script points to €96.4b revenue and €12.1b earnings by 2029, based on 5.9% yearly top line growth and an earnings increase of about €4.2b from €7.9b today.
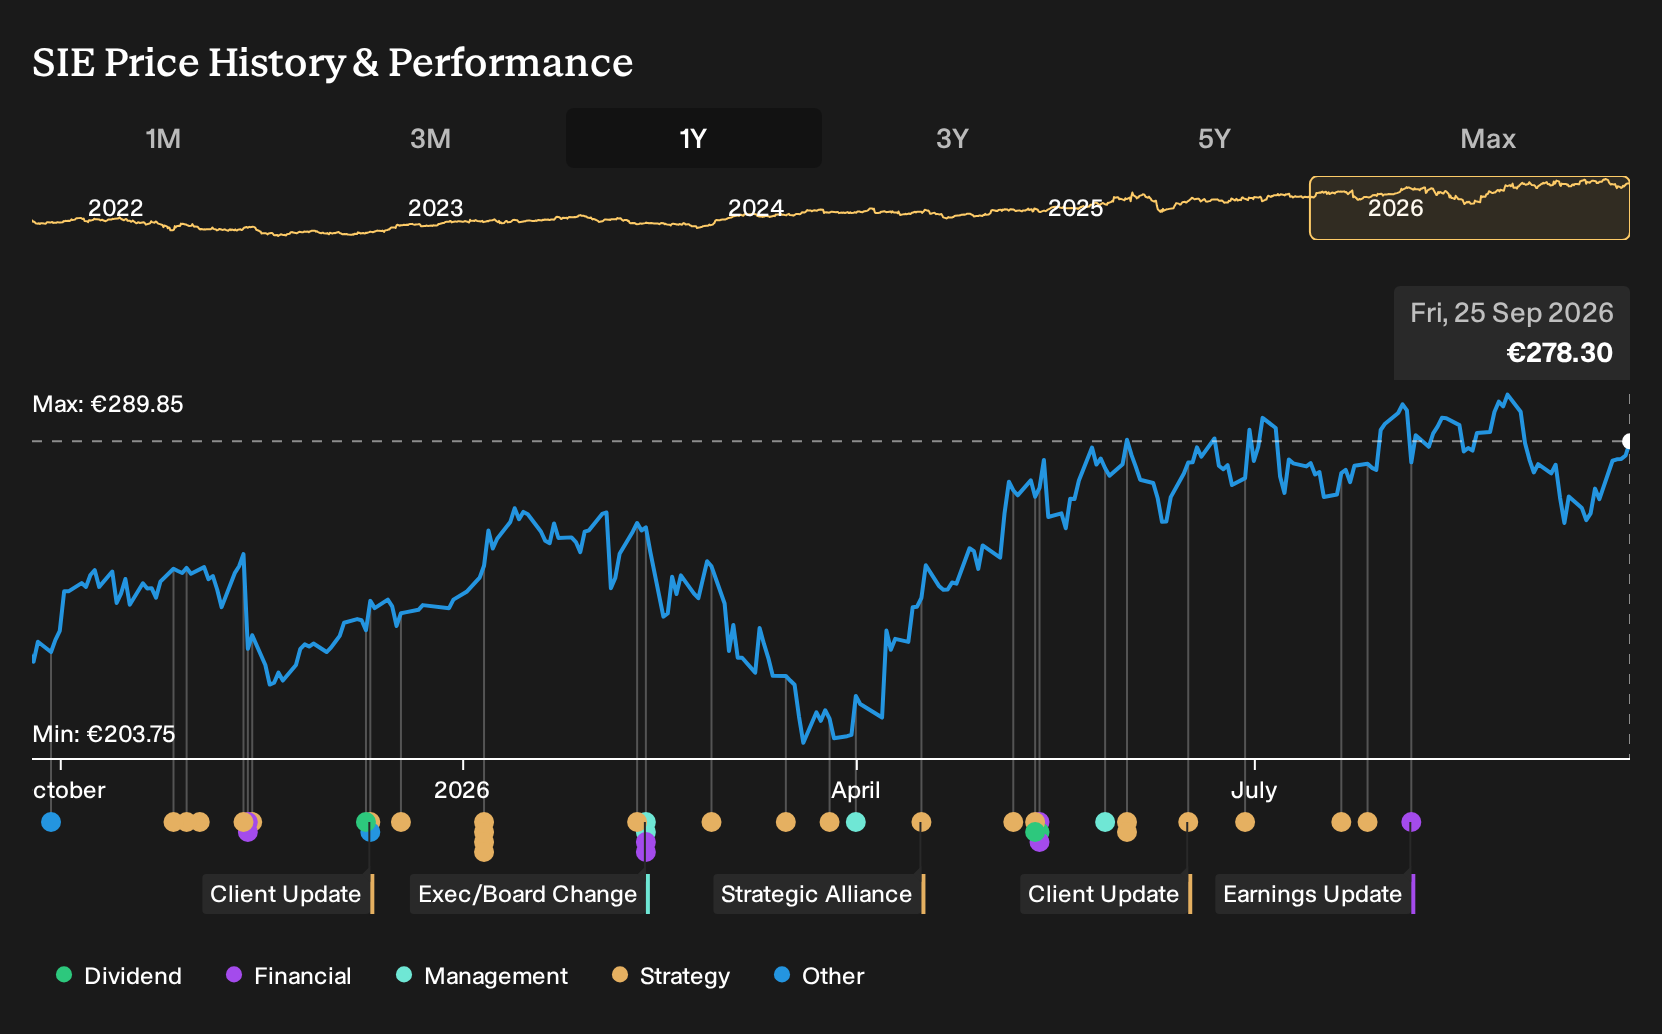
Uncover why Siemens' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Siemens watchers lean hard into the AI and data center angle. They were pencilling in revenue of about €108.8b and earnings of roughly €13.8b by 2029, far above consensus. You can treat the latest smart water and smart meter news as a fresh test of those upbeat assumptions.
Explore 4 other Siemens fair value estimates, including one that suggests a potential 40% increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Siemens research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siemens. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siemens' overall financial health at a glance.
Looking For More Investment Ideas Beyond Siemens?
If Siemens has sharpened your thinking about electrification, automation, and software, it can be useful to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for traits that fit your own approach, whether you care more about stability, income, or finding underfollowed opportunities.
- If capital preservation is high on your list, start with companies that screen as resilient on volatility and balance sheet risk through the 227 resilient stocks with low risk scores.
- If you want income to do more of the work, focus on businesses that offer stronger yields with relatively robust fundamentals by using the 162 dividend fortresses.
- If the appeal of Siemens is the mix of quality and mispricing, compare it with a curated 620 high quality undiscovered gems that might not yet be widely followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com