
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Naval And Communications Wins Require Action From Leonardo DRS Stock Investors?
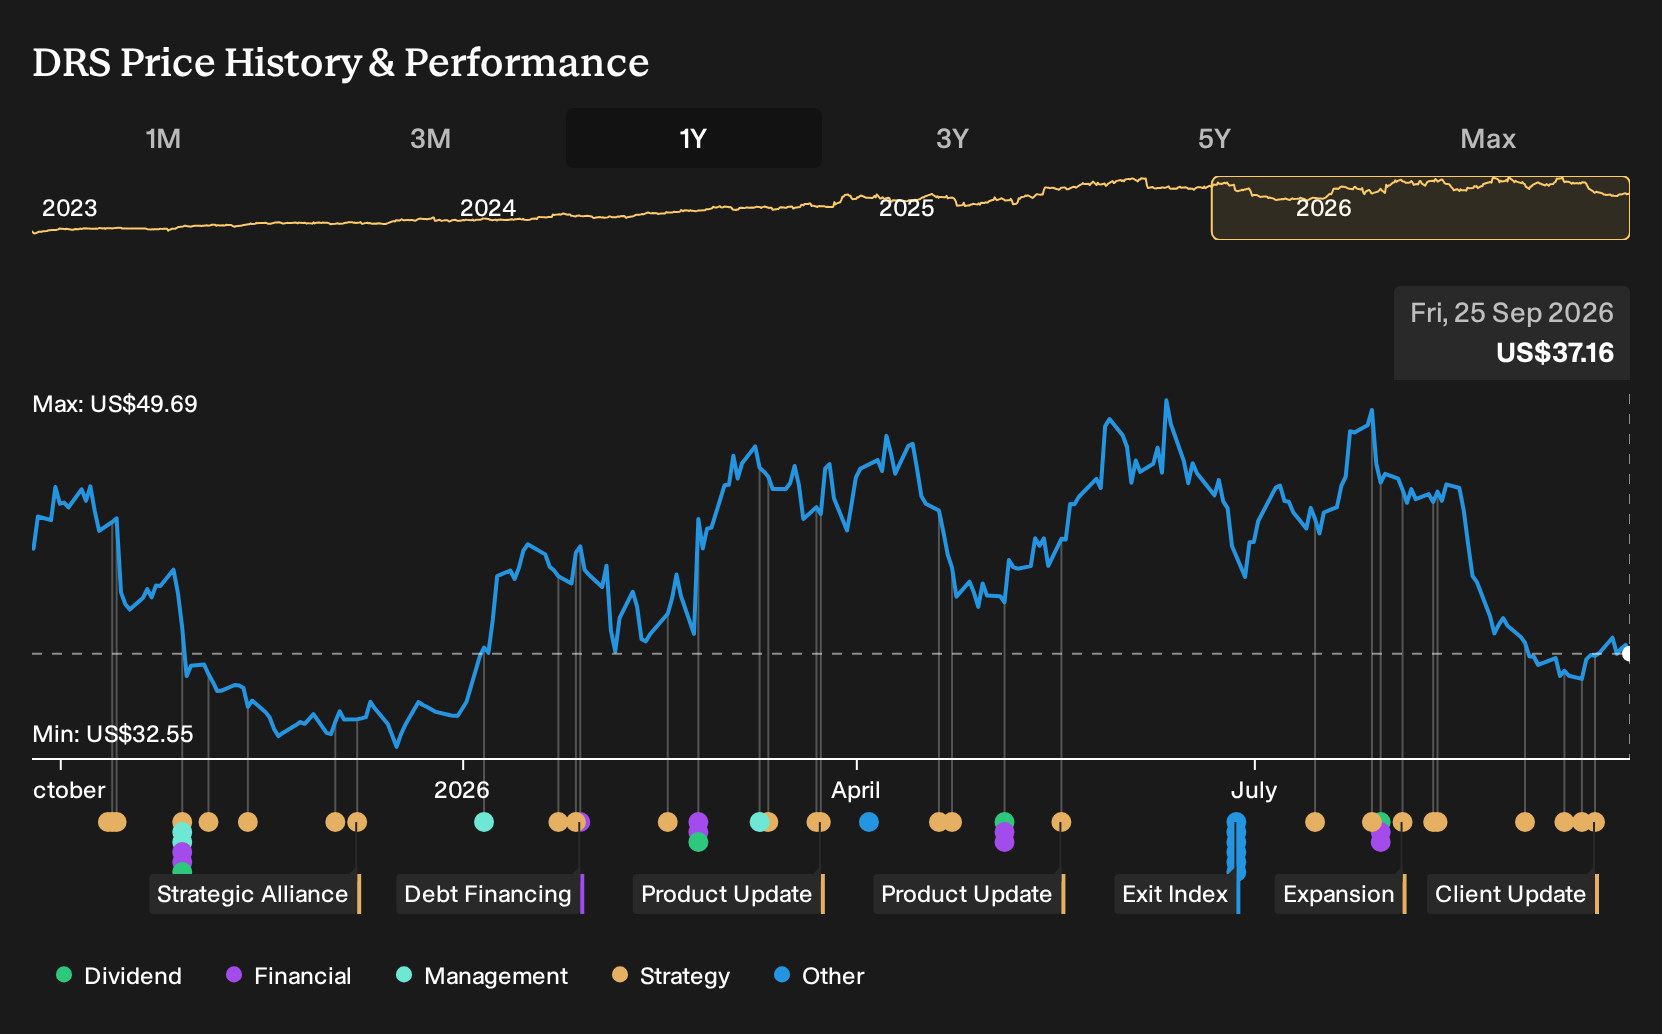
- Leonardo DRS announced contracts to supply electric propulsion systems for the Republic of Korea Navy’s KDDX destroyer program and JTT-X terminals under a US$39.6 million U.S. Navy award.
- The combination of permanent magnet naval propulsion hardware and modular, SATCOM focused transceivers suggests deeper integration of Leonardo DRS technology across allied fleets and aircraft.
- This article reviews how Leonardo DRS’s investment narrative may evolve as it supplies electric propulsion for Korea’s KDDX destroyer program.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to be comfortable with a defense electronics business that leans heavily on long cycle programs and funded backlogs, while carrying a P/E that is above some peers. The core belief is that its focus areas, such as naval propulsion and sensing, translate into sustained orders that support earnings, even as revenue growth expectations remain moderate.
The key near term swing factor is whether recent contract wins convert cleanly into backlog and margin delivery without reviving past concerns about a soft pipeline or weaker return on invested capital. The KDDX propulsion award and JTT X contract look helpful but not individually transformative, so the bigger risk around execution and future awards remains intact.
The KDDX electric propulsion deal with Doosan Enerbility ties directly into existing catalysts around naval modernization, where analysts already flag South Korean destroyer content as a driver for revenue visibility. This contract reinforces Leonardo DRS’ presence in integrated power systems, a segment where internal R&D and capex have been rising as a share of sales.
For you, the practical lens is simple. This announcement adds another data point that those higher cash outlays in naval propulsion are connecting to real hardware programs, while still leaving open questions on free cash flow and backlog trends if follow on work slows. Execution on KDDX timelines, cost, and performance now feeds straight into how credible that longer term earnings story looks.
Leonardo DRS’ current analyst script assumes revenues reach US$4.6b and earnings hit US$458.3m by 2029, based on 7.1% yearly revenue growth and an earnings increase of about US$136.3m from US$322.0m today.
Uncover why Leonardo DRS' fair value indicates a 45% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts see the big catalyst not just in contracts like KDDX, but also in how fast Leonardo DRS can scale AI driven sensing and C5ISR. Before this news, they were already modeling about 8.0% annual revenue growth and earnings of roughly US$444.6m by 2029. That is a far more upbeat script than consensus, so consider this announcement a fresh reason to compare those different narratives rather than assuming one view is correct.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests up to 59% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking For More Investment Ideas Beyond Leonardo DRS?
If the Leonardo DRS story has sharpened your interest in defense and industrial technology, it can be useful to line it up against other companies with different risk and return profiles. The Simply Wall St Screener lets you scan the market quickly and then go deeper on the handful of stocks that genuinely fit your own criteria.
- Focus on resilient balance sheets and steadier fundamentals by checking companies that feature in our list of solid balance sheet and fundamentals (24 results).
- If you want ideas where quality and valuation intersect, cast the net across our curated universe of 16 high quality undiscovered gems.
- For income oriented investors who care about both yield and durability, shortlist potential candidates using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com