
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How IT Write Down Will Impact Sampo Oyj Stock Investors
- Sampo Oyj reported that an impairment test on intangible assets tied to the Topdanmark IT integration will result in a third quarter 2026 impairment loss with related VAT charges of about €118 million before tax, which the group expects to have only a minor effect on solvency.
- The write down highlights the real cost of harmonising Topdanmark’s systems with If Group. It also puts a spotlight on execution discipline, capital allocation choices and how aggressively Sampo Oyj is willing to refresh its digital infrastructure to support future operations.
- We will look at how Sampo Oyj's investment narrative is affected by the €118 million IT impairment tied to the Topdanmark integration.
Scan how Sampo Oyj’s IT write down and buyback story compares with other insurers and financials by reviewing our hand picked 227 resilient stocks with low risk scores with resilient balance sheets and disciplined capital use.
Sampo Oyj Investment Narrative Recap
Sampo Oyj may appeal to you if you believe its focus on non life insurance, digital investments and disciplined underwriting can keep returns robust even while growth expectations are moderate. The €118 million IT impairment linked to Topdanmark appears to be a one off accounting hit with a minor solvency effect, so it does not obviously change the operational thesis.
The bigger short term swing factor remains how well Sampo Oyj manages claims, pricing and cost ratios across its Nordic and UK portfolios. The main risk still sits in regional exposure, competitive pressure and the need for ongoing tech spend, all of which could squeeze margins if conditions turn less favourable.
The completed €350 million share buyback is the other key piece of context for this impairment. Cancelling 37,827,020 A shares, about 1.42% of the previous share count, tightens the equity base at the same time the IT asset value is written down, so both items feed into capital and per share metrics.
For you as a shareholder, that pairing puts the spotlight on execution. Management now has to demonstrate that the Topdanmark integration, IT harmonisation and digital distribution push can earn attractive returns on the capital that remains, while still keeping enough flexibility to handle weather events, competition and slower forecast revenue growth around 2.6% per year.
Sampo Oyj Forecasts Behind The IT Hit
Sampo Oyj's narrative projects €10.9b revenue and €1.6b earnings by 2029. This assumes revenue stays broadly flat over the next three years and earnings decline by €0.1b from €1.7b today to the €1.6b analyst consensus level.
Uncover why Sampo Oyj's fair value indicates a 19% potential upside to its current price, a discount that could narrow quickly as sentiment adjusts.
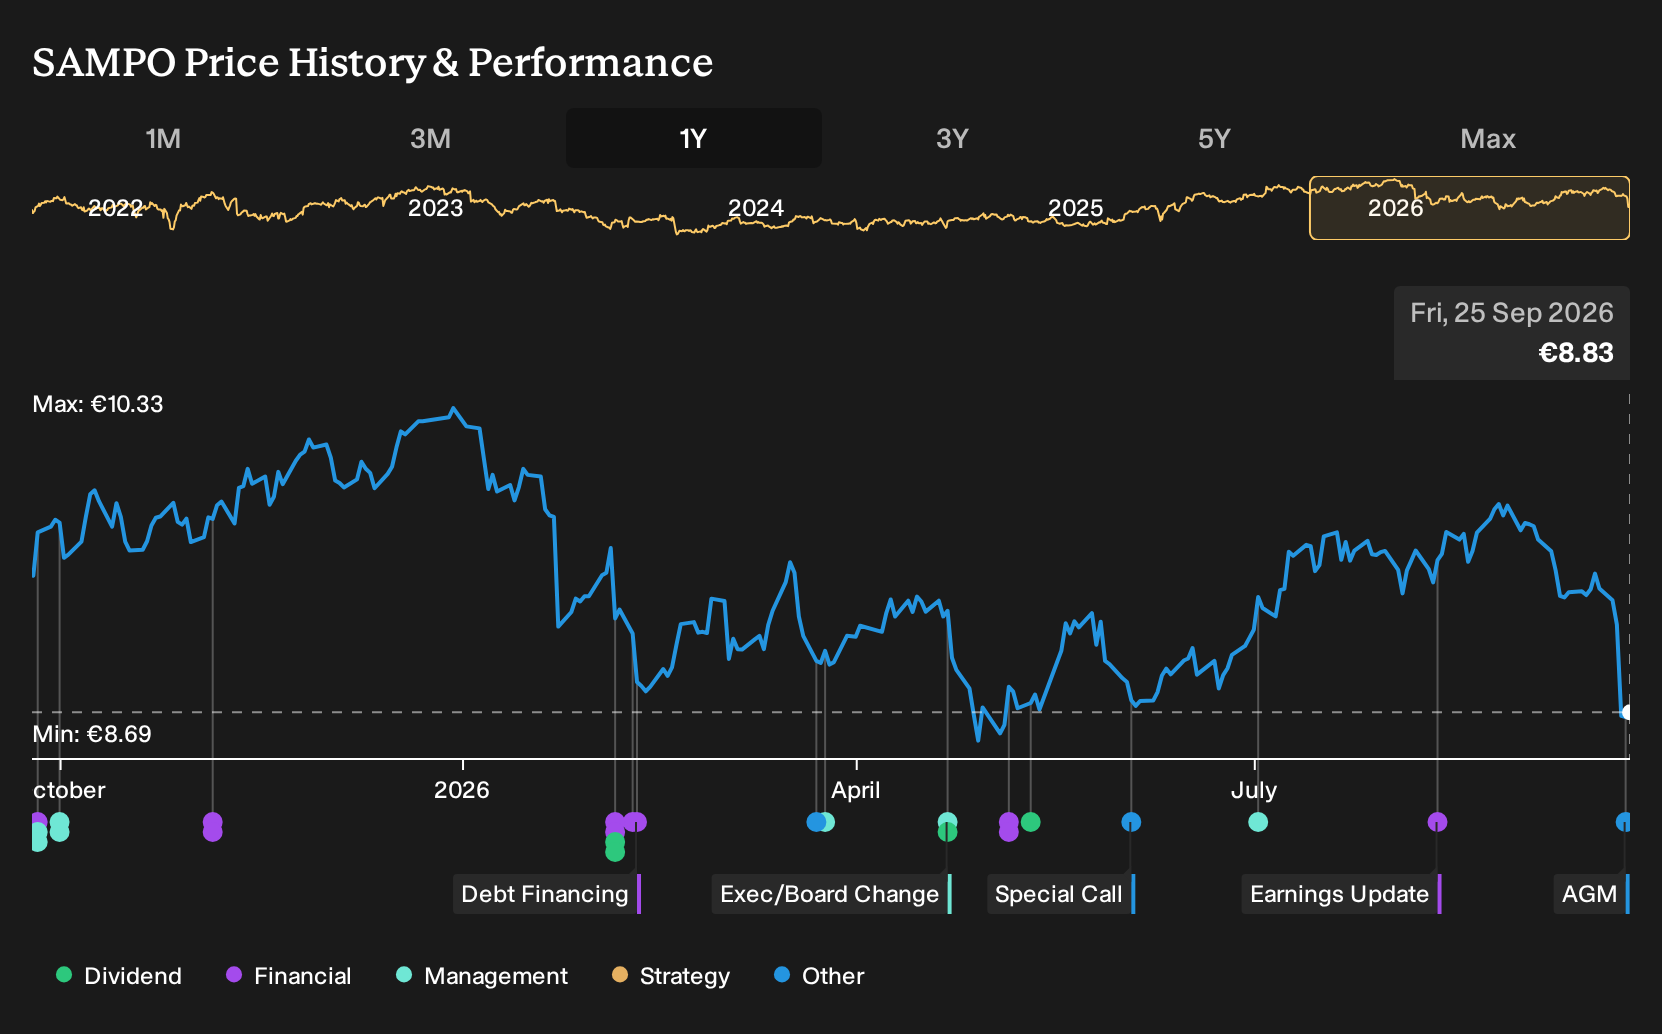
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about €10.51 and €14.26, so retail opinions on Sampo Oyj already span a wide price band. When these are set against the fresh €118m IT impairment and ongoing buybacks, it becomes clear why different investors may weigh execution risk very differently. It is worth exploring those contrasting viewpoints before deciding how this story fits your portfolio.
Explore 2 other Sampo Oyj fair value estimates, including one that suggests it could be worth just €10.51.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sampo Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sampo Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sampo Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sampo Oyj?
If the Sampo Oyj story has sharpened your view on risk, capital returns and balance sheet strength, it can be useful to compare it with other opportunities that share some of those traits but play out in very different corners of the market.
- For investors hunting for companies that the market may be underpricing relative to their fundamentals, take a look at 182 high quality undervalued stocks that could merit a spot on your watchlist.
- If income is a priority and you want businesses that target sizable payouts, review 162 dividend fortresses that focus on higher yielding distributions.
- For a broader watchlist built around resilience, filter for sturdier balance sheets and cleaner fundamentals by running a list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com