
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Codeshare Partnership At American Airlines (AAL) Has Changed Its Investment Story
- American Airlines Group and STARLUX Airlines have entered a new codeshare partnership, linking STARLUX’s Taipei services with American’s domestic network across 20 initial U.S. cities and offering single-ticket itineraries and through-checked baggage for travelers heading across Asia.
- The planned reciprocal frequent-flyer tie up means American Airlines customers could earn and redeem miles on eligible STARLUX codeshare flights, which may deepen loyalty engagement across transpacific and U.S. domestic routes.
- We will now look at how American Airlines Group's investment narrative is shaped by this expanded transpacific and domestic codeshare reach.
Scan how American Airlines Group’s new STARLUX tie up compares with other carriers expanding their reach across key routes by reviewing 40 power grid technology and infrastructure stocks in the current travel and infrastructure trend.
American Airlines Group Investment Narrative Recap
To back American Airlines Group, you need to be comfortable with a high fixed cost and high leverage business that is still unprofitable but shows improving revenue and shrinking losses. The core belief is that a broad network, strong domestic position and a growing loyalty ecosystem can support steadier cash generation over time.
Right now the key near term swing factor is whether revenue and earnings can cover interest and heavy fleet spending while domestic demand and pricing remain mixed. The STARLUX partnership helps American lean more on international and loyalty driven traffic, but it does not change the fundamental debt and cost risks.
This new codeshare sits alongside another big operational lever. American Airlines Group has a long dated agreement with Citi to support AAdvantage card economics from 2026. This agreement directly targets higher margin loyalty and partnership income rather than pure seat sales.
That shift matters when you set it next to the STARLUX deal. More international feed and more engaged loyalty members both work toward the same catalysts discussed earlier, namely higher ancillary and program revenue. For you as a shareholder, the open question is execution versus the ongoing pressure from debt, labor costs and uneven domestic trends.
American Airlines Group’s current analyst narrative points to US$68.2b in revenue and US$1.7b in earnings by 2029, based on an assumed 5.4% yearly increase in revenue and a swing in earnings of roughly US$2.0b from a loss of US$326.0m today to that 2029 forecast.
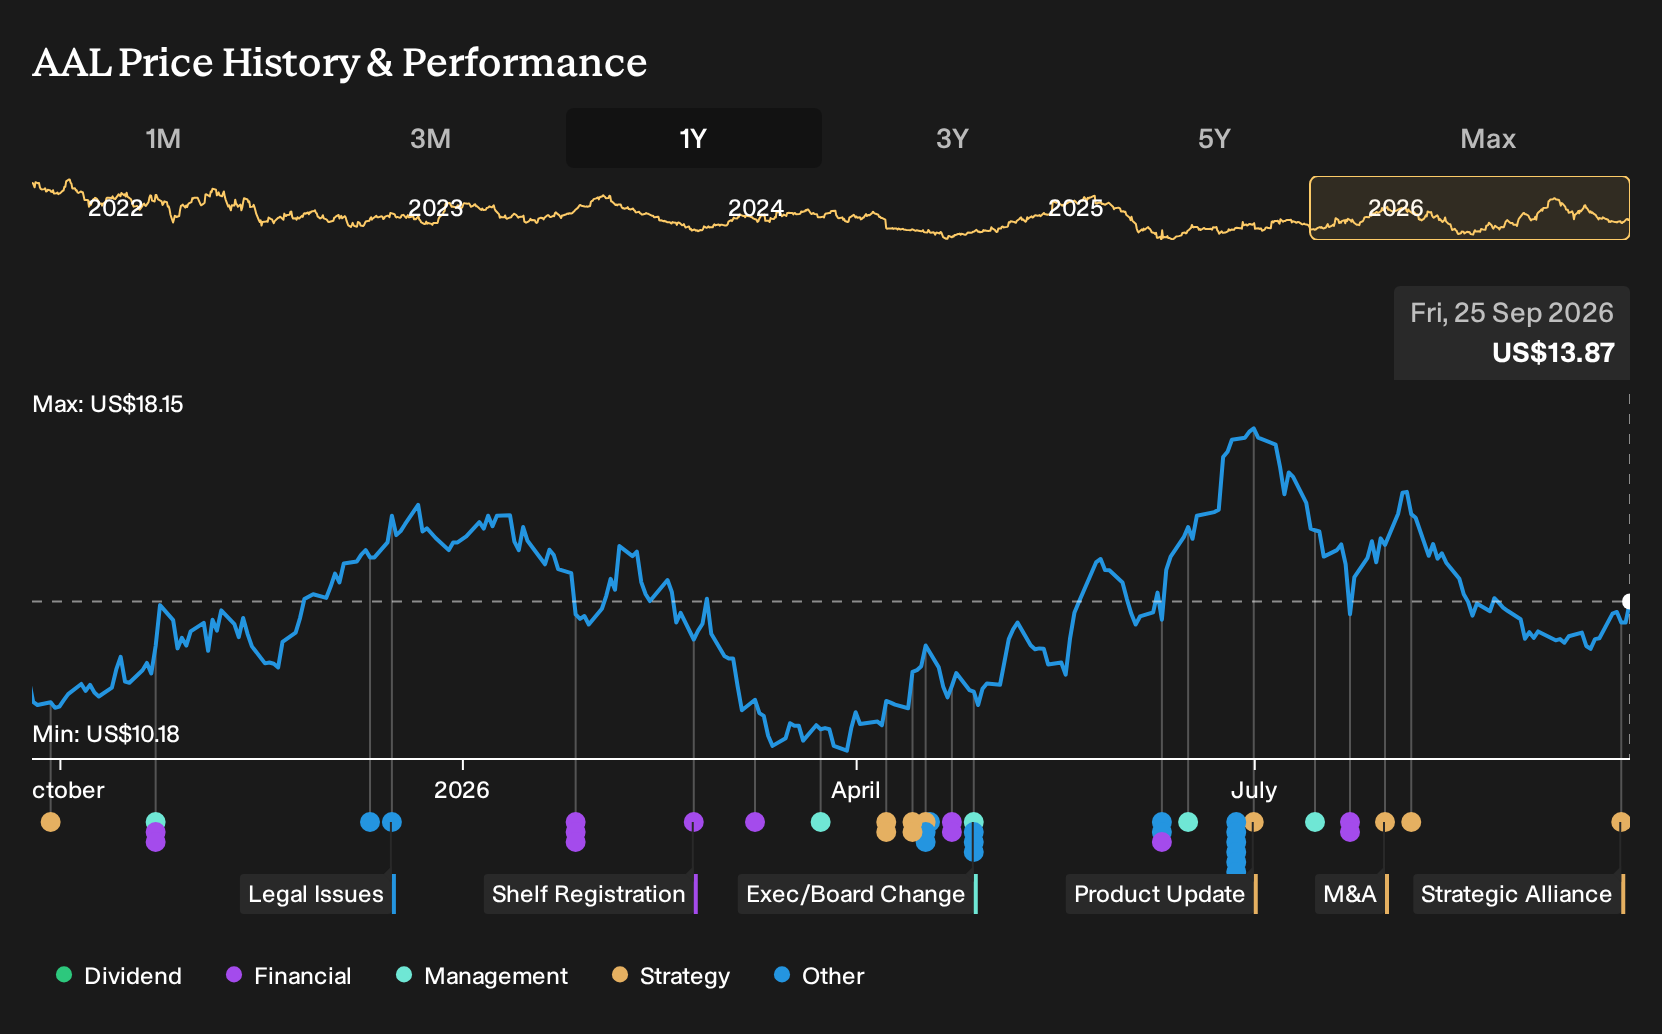
Uncover why American Airlines Group's fair value indicates a 27% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
One alternate view puts long term business travel risk at the center of the American Airlines Group debate. The most cautious analysts, using forecasts from before this STARLUX news, were only penciling in revenue of about US$60.8b and earnings near US$1.3b by 2029. That is a much lower bar than consensus. Use that gap as a reminder that smart people can disagree widely, and treat this new partnership as a fresh reason to revisit both the optimistic and cautious cases.
Explore 6 other American Airlines Group fair value estimates, including one that suggests as much as 28% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Airlines Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Airlines Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate American Airlines Group's overall financial health at a glance.
Looking For More Ideas Beyond American Airlines Group?
If the American Airlines Group story has you thinking about where to allocate fresh capital next, it can help to scan a wider field of opportunities that match your risk profile and income goals.
- For investors who want income to do more of the heavy lifting in total returns, consider screening for higher yielding candidates through 8 dividend fortresses that meet strict criteria around payout quality.
- If capital preservation sits high on your priority list, you could focus on steadier balance sheets and sturdy fundamentals by running a search using the list of solid balance sheet and fundamentals (24 results) and comparing which businesses look more defensively positioned.
- Those hunting for less crowded opportunities may prefer to start with companies that attract less attention yet still post strong fundamentals, using the 16 high quality undiscovered gems as a way to surface potential ideas that the broader market might be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com