
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OGE Energy (OGE) Could Be 11% Undervalued After Its Latest Dividend Call
OGE Energy (OGE) drew fresh attention after its board approved a fourth quarter dividend of $0.42875 per share, payable on October 30, 2026, to investors of record on October 5.
For context, OGE Energy’s share price has slipped 3.7% over the past month and 9.6% over the past quarter, even as the year-to-date share price return is 4.5% and the 5-year total shareholder return sits at 68.1%. This points to longer term momentum despite softer recent trading around the dividend decision.
Compare OGE Energy’s dividend move with other potential income opportunities by scanning a curated list of 8 dividend fortresses that may offer different risk and payout profiles.
OGE Energy now trades about 13% below the average analyst target after a softer quarter for the stock. Is that discount pointing to opportunity, or does it reflect concerns about valuation risk ahead of the next move?
Most Popular Narrative: 11% Undervalued
OGE Energy last closed at $44.81, compared with a widely followed fair value estimate of $50.45 that uses a 7.24% discount rate. That gap rests on a detailed view of future load growth, capital spending and regulation rather than just a simple comparison to recent trading.
Ongoing and planned investments in generation capacity and transmission infrastructure are now backed by a draft 2026 resource plan that identifies about 1.9 gigawatts of incremental capacity needs by 2031 and specific projects such as 550 megawatts of capacity additions in 2026, the 300 megawatt Frontier Storage project in 2027, and Southwest Power Pool assigned 765 kV transmission work. Together these initiatives extend the capital cycle and rate base growth potential, supporting future earnings.
See why 2 investors see OGE Energy as 11% undervalued.
Result: Fair Value of $50.45 (UNDERVALUED)
Still, OGE Energy’s story can change quickly if regulators push back on cost recovery, or if large data center demand slows and leaves the capital plan exposed.
Find out about the key risks to this OGE Energy narrative.
Another View: OGE Energy Through A Cash Flow Lens
The analyst fair value for OGE Energy leans on earnings forecasts and multiples, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow view, the stock at $44.81 sits above an estimated future cash flow value of $36.13, which frames the shares as overvalued rather than discounted. Which lens do you trust more when the signals conflict?
To see how this cash flow view is built and where the sensitivities sit, take a look at the Look into how the SWS DCF model arrives at its fair value..
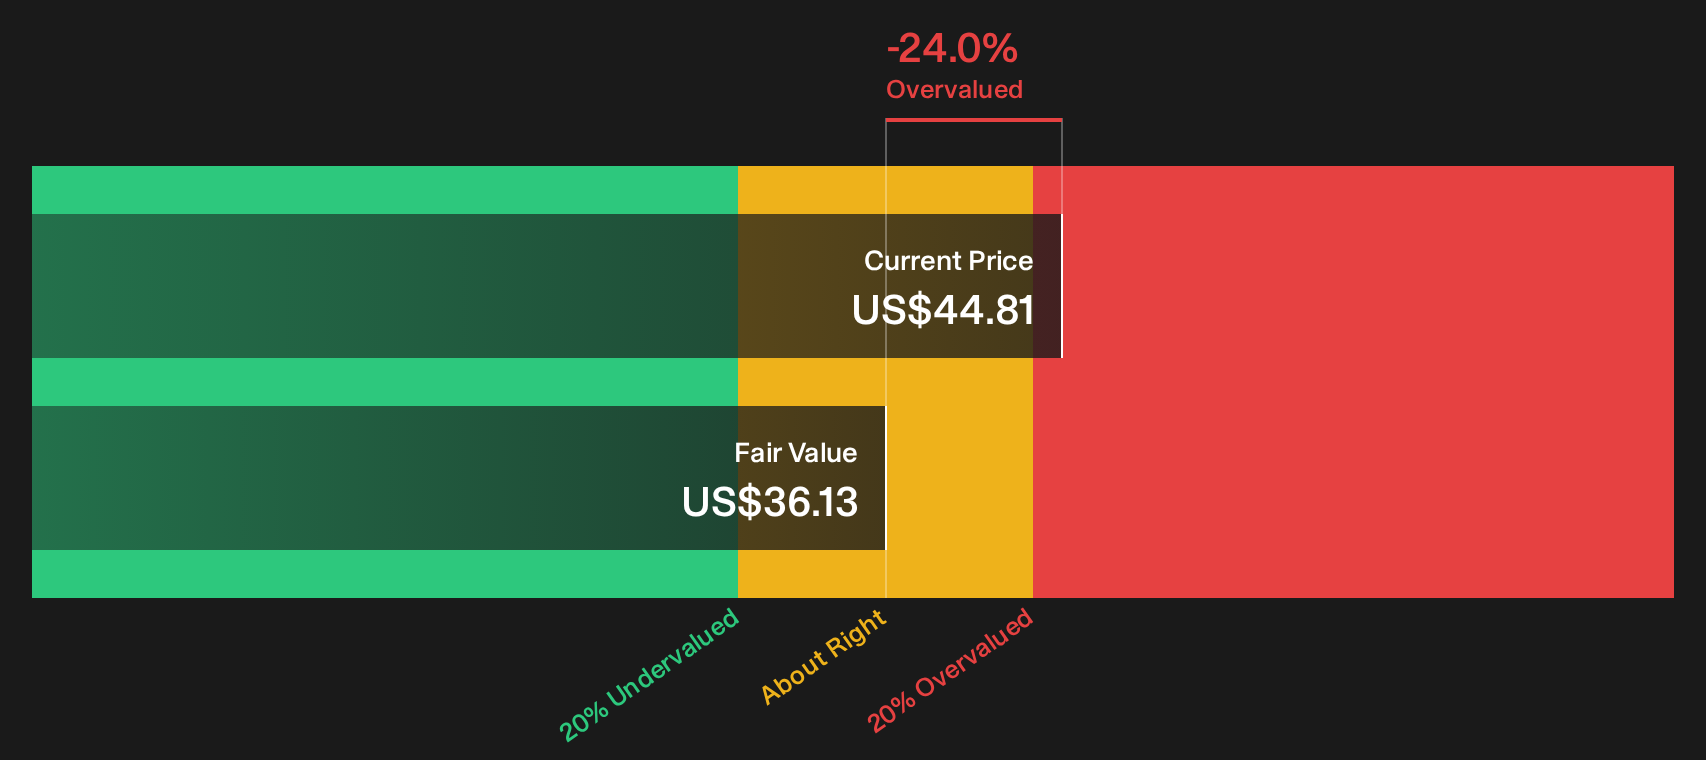
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OGE Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around OGE Energy's value and risk profile can be confusing, so consider acting while sentiment is still split and reach your own judgment by weighing the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond OGE Energy?
If OGE Energy has you thinking more broadly about where to put fresh capital to work, this is the moment to widen your search before the next move leaves you reacting instead of prepared.
- Target dependable income streams by scanning a curated 8 dividend fortresses that focus on payout strength alongside other financial fundamentals.
- Hunt for potential value opportunities through a 32 high quality undervalued stocks that combine pricing gaps with quality balance sheets and earnings power.
- Zero in on financial resilience using a list of solid balance sheet and fundamentals (24 results) that highlight stronger funding positions and lower leverage profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com