
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mitsubishi (TSE:8058) Just Gave Investors Something To Think About
Mitsubishi (TSE:8058) has set an ex-dividend date of September 29, 2026 for a cash payout of ¥62.00 per share. The announcement comes alongside earnings per share that exceeded analyst estimates.
Mitsubishi’s share price has climbed to ¥4,859, with a 90-day share price return of 10.36% and a year to date share price gain of 33.01%, while the 5 year total shareholder return of 391.00% indicates strong longer term momentum around the stock.
Scan how Mitsubishi compares with other income and quality plays by checking our hand picked list of 14 dividend fortresses riding similar themes of cash returns and resilience.
Mitsubishi’s payout and multi year share surge set a high bar. The real tension now is whether the current valuation still offers a fair trade off between upside and risk for new capital.
Most Popular Narrative: 8% Undervalued
Mitsubishi last closed at ¥4,859, while the most followed narrative places fair value around ¥5,265. That gap sits on a story built around energy transition exposure, food supply chains, and portfolio reshaping rather than a simple one quarter beat.
Significant strategic investments and first shipments in LNG, renewable fuels, and expansion in seafood/farming position Mitsubishi to benefit from global energy transition and rising food demand, supporting future revenue and earnings growth.
Active capital recycling and selective divestitures of lower-margin businesses align the portfolio toward higher-margin and recurring revenue streams, likely to enhance net margins and improve return on equity over the medium term.
See why 34 investors see Mitsubishi as 8% undervalued.
Result: Fair Value of ¥5,265 (UNDERVALUED)
Still, the Mitsubishi story can unravel if prolonged weakness in key commodities or slower payoffs from renewable and food investments undercuts the earnings profile that backs this narrative.
Find out about the key risks to this Mitsubishi narrative.
Another View on Mitsubishi’s Value
The narrative fair value for Mitsubishi sits around ¥5,265, yet our DCF work points in a different direction. On SWS DCF model assumptions, the estimated future cash flow value is closer to ¥2,731.83 per share, which frames today’s ¥4,859 level as overvalued by that lens. Which story do you trust more: earnings narratives or hard cash flow math?
Look into how the SWS DCF model arrives at its fair value.
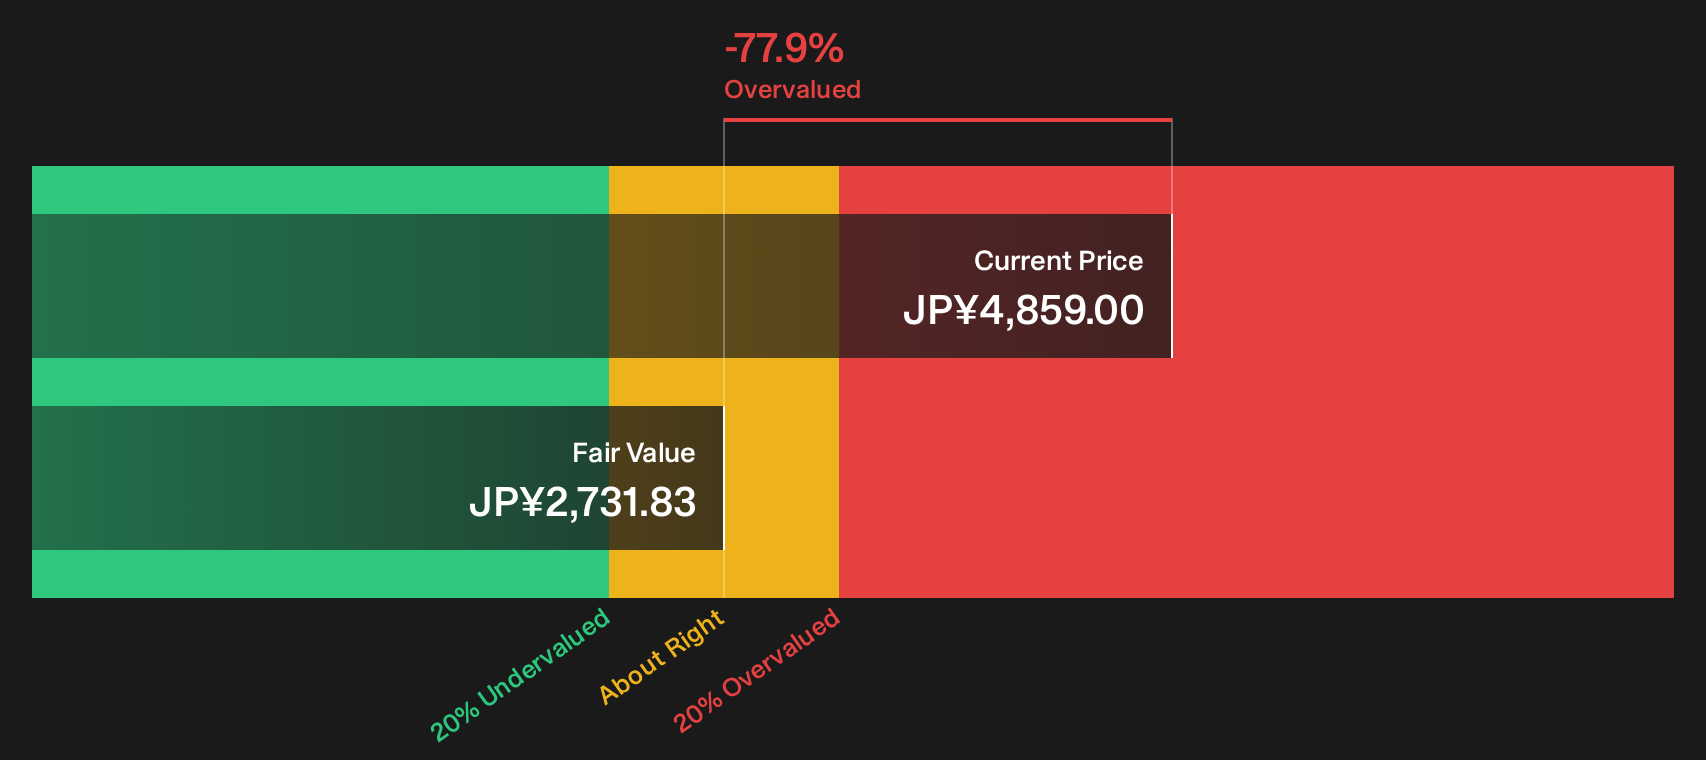
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The Mitsubishi story presents mixed signals so far. To move quickly from headlines to your own thesis, consider both sides of the debate with 2 key rewards and 1 important warning sign.
Looking for more Mitsubishi investment ideas?
If Mitsubishi has sharpened your focus, do not stop here. Cast the net wider with focused screeners that surface fresh possibilities before others catch on.
- Target potential value opportunities early by running your filters through 74 high quality undiscovered gems to combine quality fundamentals with lower market attention.
- Strengthen portfolio resilience by scanning for companies with robust financial positions using the list of solid balance sheet and fundamentals (22 results).
- Raise the floor on risk by reviewing the 21 resilient stocks with low risk scores to find companies that score well on balance sheet strength and business stability before volatility bites.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com