
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Turning Point Brands Stock CEO Change Means For Shareholders
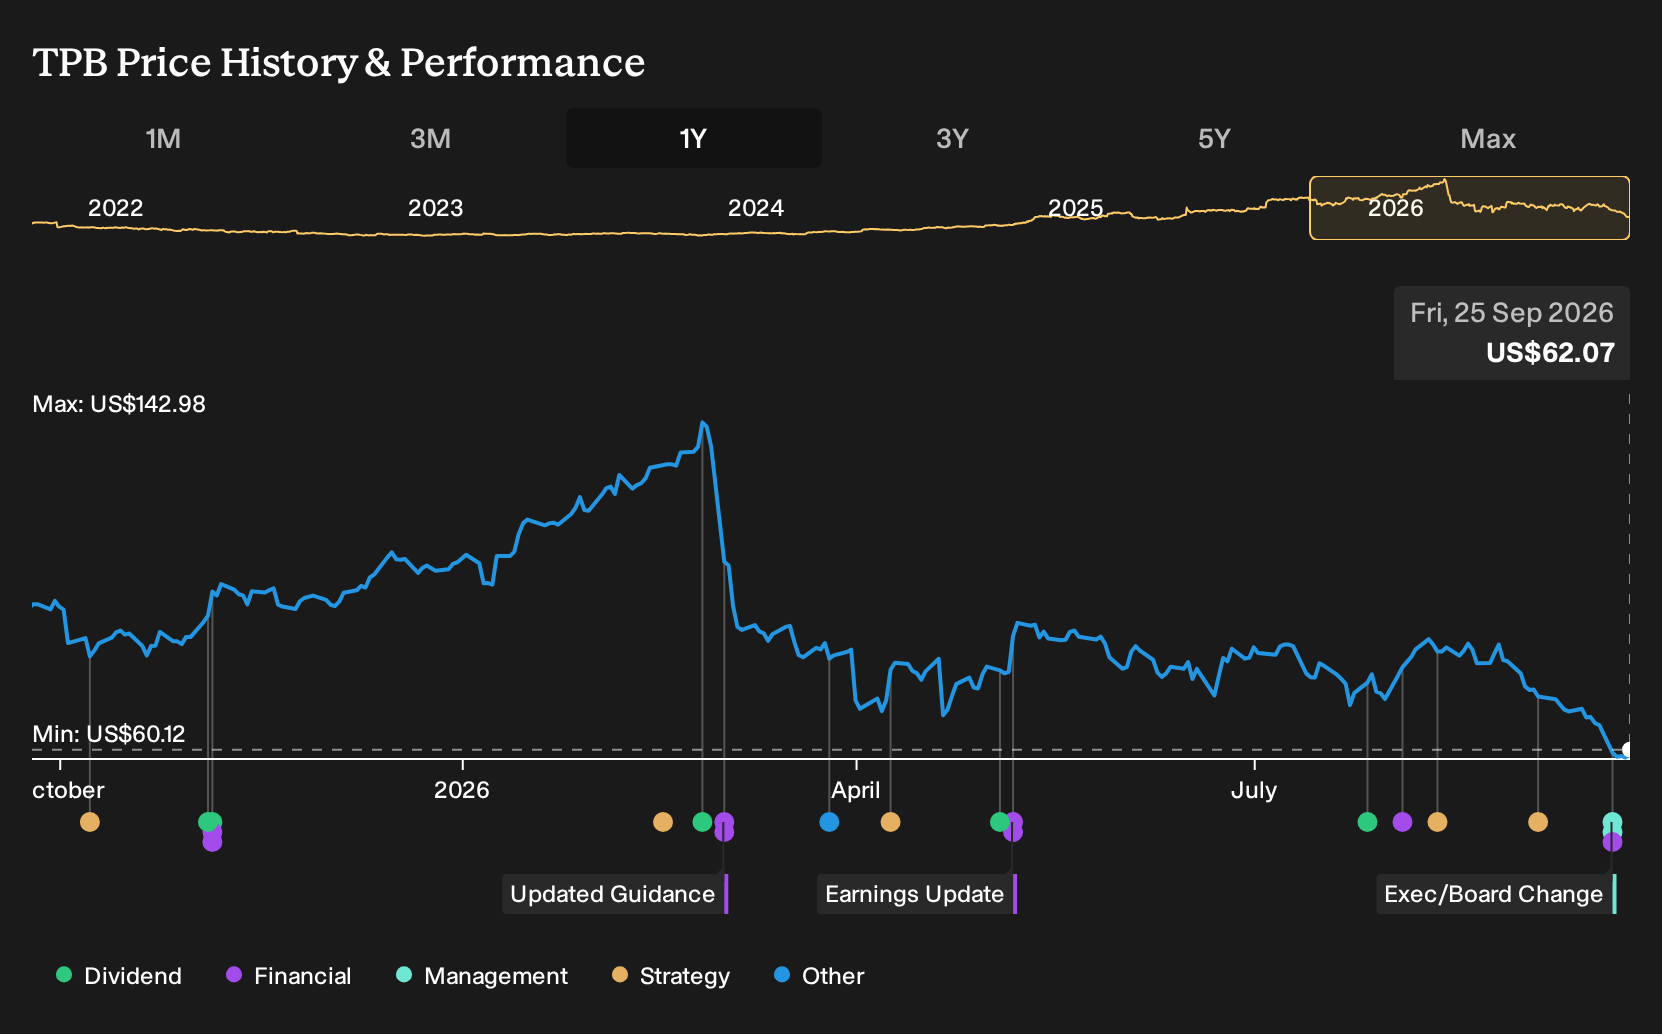
- Turning Point Brands reported that former Executive Chairman David E. Glazek will become CEO on October 1, 2026, following Graham Purdy’s resignation from his roles as Chief Executive Officer, President, and director. The company also reaffirmed its 2026 Modern Oral gross sales guidance of US$330 million to US$350 million and net sales of US$260 million to US$270 million.
- The leadership handover to a long-serving board member keeps Turning Point Brands’ governance and operating knowledge in-house while the business continues to target sizeable Modern Oral revenue. This underscores how central that segment remains to the company’s earnings mix and planning.
- We will now look at how Turning Point Brands’ investment narrative could be affected by this CEO transition alongside reaffirmed earnings guidance.
Turning Point Brands Investment Narrative Recap
To own Turning Point Brands, you need to believe the Modern Oral push can offset pressure in traditional tobacco and keep funding product development and distribution. The reaffirmed 2026 Modern Oral sales guidance signals management still sees that segment as the key near term driver. The CEO change does not alter those targets, so the core operating thesis remains tied to execution in nicotine pouches and premium brands.
The main short term catalyst is whether Modern Oral distribution, marketing spend, and sales force investments convert into the guided US$260 million to US$270 million in net sales. The biggest current risk stays the same for Turning Point Brands. High spending and reliance on nicotine pouches leave margins exposed if competitive discounting, regulation, or supply chain issues occur at an unfavorable time.
The reaffirmed 2026 Modern Oral guidance is the announcement that matters most here. It gives you a concrete yardstick to judge how smoothly the leadership handover to David E. Glazek is running. If Turning Point Brands keeps tracking toward US$330 million to US$350 million of Modern Oral gross sales, that would suggest internal plans and field execution remain aligned with prior expectations.
If performance drifts away from those targets, questions will quickly shift to marketing efficiency, pricing discipline, and competitive share rather than the headline CEO change. For now, the guidance reiteration keeps the focus on operational delivery in Modern Oral, while longer term risks such as regulation, overseas manufacturing exposure, and compressed profit margins still sit in the background of any catalyst discussion.
Turning Point Brands’ current analyst narrative points to US$1.0b in revenue and US$155.1 million in earnings by 2029, based on assumed 25.5% yearly top line growth and a rise in profit from US$44.6 million today, which would mean earnings more than triple from current levels over that period.
Uncover why Turning Point Brands' fair value indicates a 91% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
For Turning Point Brands, the big swing factor in the more optimistic narrative is Modern Oral onshoring. Bullish analysts were already penciling in about US$996.5 million of revenue and US$136.1 million of earnings by 2029 before this CEO news, so those projections could shift meaningfully once investors reassess execution risk under new leadership.
Explore 3 other Turning Point Brands fair value estimates, including one that suggests as much as 156% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Turning Point Brands research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Turning Point Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Turning Point Brands' overall financial health at a glance.
Looking For More Ideas Beyond Turning Point Brands?
Turning Point Brands may or may not fit your watchlist, but the real edge often comes from lining it up against a broader bench of candidates. The Simply Wall St Screener lets you quickly sort through other companies that match the kind of risk, income, or balance sheet profile you want to pair with a position like this.
- If you care most about resilient balance sheets and durable fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that filters for financially robust businesses.
- For investors who want potential mispricings with quality metrics to back them up, scan through a 32 high quality undervalued stocks and see which tickers fit your criteria.
- If capital preservation and a smoother ride matter more than chasing every swing, narrow your search to a 30 resilient stocks with low risk scores that focuses on sturdier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com