
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Credicorp (BAP) Is Back In The Spotlight
Credicorp (NYSE:BAP) has drawn fresh attention after recent trading left the share price at $386.16. Investors are weighing that level in relation to the group’s multi-country banking, insurance, and microfinance footprint across Latin America.
Recent trading has been relatively steady, and that calm surface sits on top of a strong run, with Credicorp’s share price return of 34.83% year to date and a one year total shareholder return of 53.57%, which points to momentum that has been building rather than fading.
Scan other banking and financial stocks showing similar momentum to Credicorp by reviewing the hand picked 32 high quality undervalued stocks now.
After a move like this, the debate around Credicorp shifts fast. Is the recent rerating already generous, or do the current numbers still leave meaningful upside on the table once you line them up against valuation?
Most Popular Narrative: 9% Undervalued
The most followed Credicorp valuation narrative pegs fair value at $422.69, above the recent $386.16 close. This frames the move as still short of that reference point and puts the recent rally in the context of longer term assumptions about earnings and discount rates.
Ongoing investments in digital platforms, AI, and end-to-end automation are boosting operational efficiency, enabling scalable service delivery with lower marginal costs, which is expected to further improve the group's net margin as revenue from digital channels grows. The group's strategic shift toward a more diversified, fee-generating, and digitally enabled business model is reducing earnings volatility, increasing cross-sell opportunities in insurance, pensions, and wealth management, and positioning Credicorp for more resilient and consistent net earnings growth.
See why 13 investors see Credicorp as 9% undervalued.
Result: Fair Value of $422.69 (UNDERVALUED)
Still, the Credicorp story can change quickly if Peru faces fresh political or regulatory shocks, or if rapid Yape lending weakens asset quality and drives up provisions.
Find out about the key risks to this Credicorp narrative.
Another View: Credicorp Through The P/E Lens
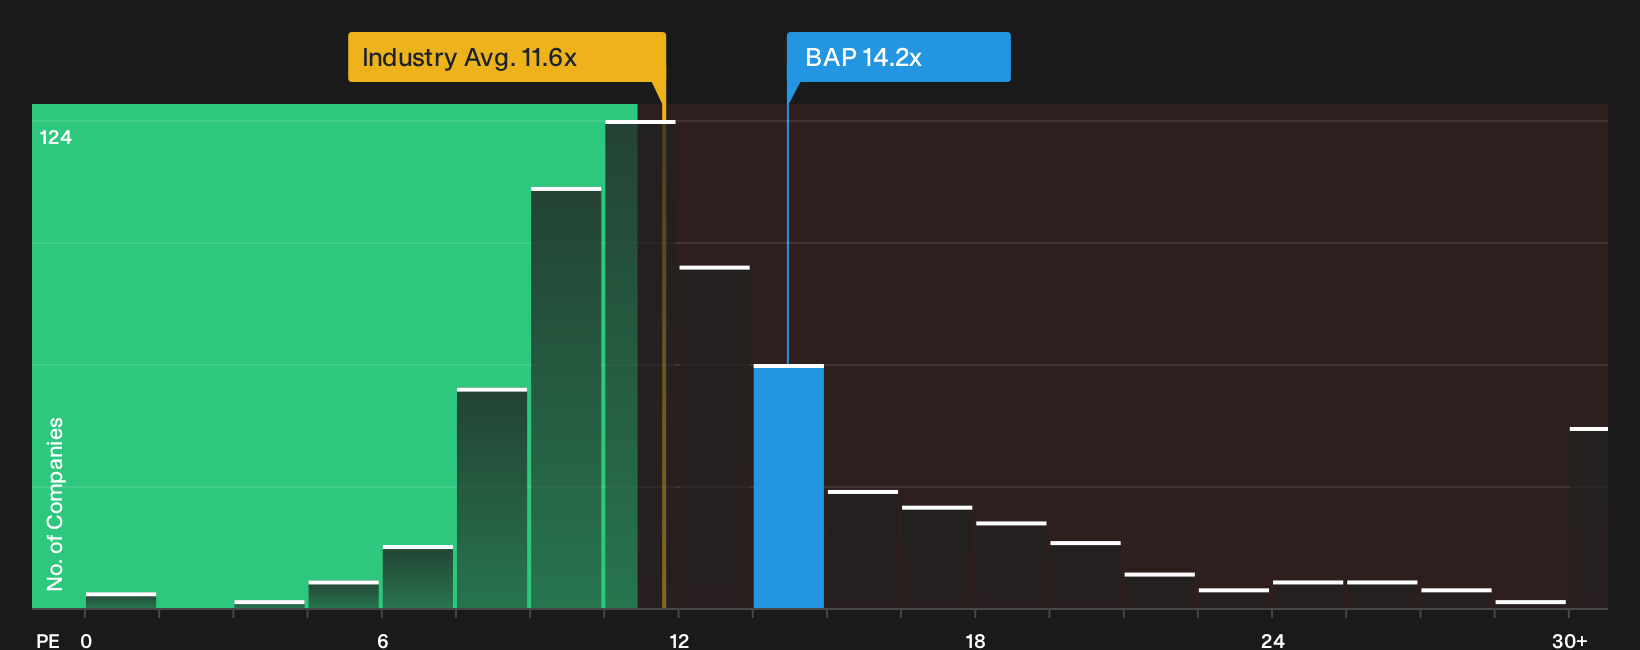
The first fair value story has Credicorp looking 9% undervalued, yet the market’s pricing signal is not quite as straightforward. At a P/E of 14.2x, the stock sits above the US Banks industry on 11.6x, but below both peer averages at 15.4x and the fair ratio of 15.7x.
That mix of richer pricing than the wider sector, but still a discount to closer peers and the fair ratio, suggests investors may be paying up for quality while not fully pricing in the earnings profile. The key question is whether that gap closes through price moves, profit delivery, or a combination of the two.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong momentum and a mixed valuation story can spark very different reactions. Move quickly, review the underlying numbers and pressure test both the upside potential and the embedded risks, then use the 3 key rewards and 2 important warning signs to balance those signals for yourself.
Looking For More Ideas Beyond Credicorp?
If you stop with Credicorp, you risk missing other opportunities. Put a shortlist together now using focused stock lists that match your style and risk comfort.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when conditions change.
- Hunt for mispriced quality and see which companies feature in the 32 high quality undervalued stocks before other investors catch on.
- Boost your income focus by reviewing the 8 dividend fortresses that screens for higher yielding payers with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com