
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Power Corporation of Canada (TSX:POW) Looks Fully Valued On Buybacks And Wealthsimple Focus
Power Corporation of Canada (TSX:POW) is back in front of institutional investors, with Executive VP and CFO Jake Paul Lawrence set to speak at the 25th Annual CIBC Eastern Institutional Investor Conference on September 24, 2026.
Recent price action has been strong, with Power Corporation of Canada delivering a 31.07% year to date share price return. Its 1 year total shareholder return of 67.23% and 3 year total shareholder return above 200% suggest momentum has been building as investors react to the simplified financial services focus, Wealthsimple’s growing scale and the ongoing share buyback program.
Scan for other financial holding and wealth management stocks showing similar momentum and capital return focus using our curated list of 9 high quality undiscovered gems.
After a 67.23% 1 year total return and a recent share price near CA$94, Power Corporation of Canada still trades below analyst targets. Is this caution from the market warranted or mispriced?
Price-to-Earnings of 22.6x: Is it justified?
Valuation has raced ahead of the story. At roughly CA$94 per share, Power Corporation of Canada trades on a P/E of 22.6x while our DCF model flags a fair value closer to CA$90, and several benchmarks suggest investors are paying a premium for each dollar of earnings.
The P/E ratio compares the share price with earnings per share. For a diversified financial group like Power Corporation of Canada, this measure helps you see how much the market is willing to pay for its current profit stream, relative to both peers and an estimated fair level.
Here the market is assigning a much richer tag than those reference points. The stock is described as expensive versus the estimated fair P/E of 15.2x, which indicates a level that earnings could reasonably support based on a regression of fundamentals. That is a wide gap between what investors are paying and where the valuation model suggests the multiple could settle.
The premium stretches further when set against the broader field. Power Corporation of Canada trades on 22.6x earnings, compared with 11.5x for the North American insurance industry and 17.9x for its peer group, which is a strong signal that buyers are accepting a higher bar than both sector and fair value benchmarks.
Explore the SWS fair ratio for Power Corporation of Canada.
Result: Price-to-Earnings of 22.6x (OVERVALUED)
Still, the bullish setup around Power Corporation of Canada could unwind quickly if wealth and insurance fee pools soften, or if buybacks slow and reduce support for that premium multiple.
Find out about the key risks to this Power Corporation of Canada narrative.
Another View on Power Corporation of Canada’s Value
The P/E premium makes Power Corporation of Canada look stretched, yet the SWS DCF model points to a fair value of about CA$90 per share, only slightly below the current CA$94.28 level. That smaller gap raises a simple question: Is the market really overpaying, or just pricing in a bit more optimism than the model assumes?
Look into how the SWS DCF model arrives at its fair value.
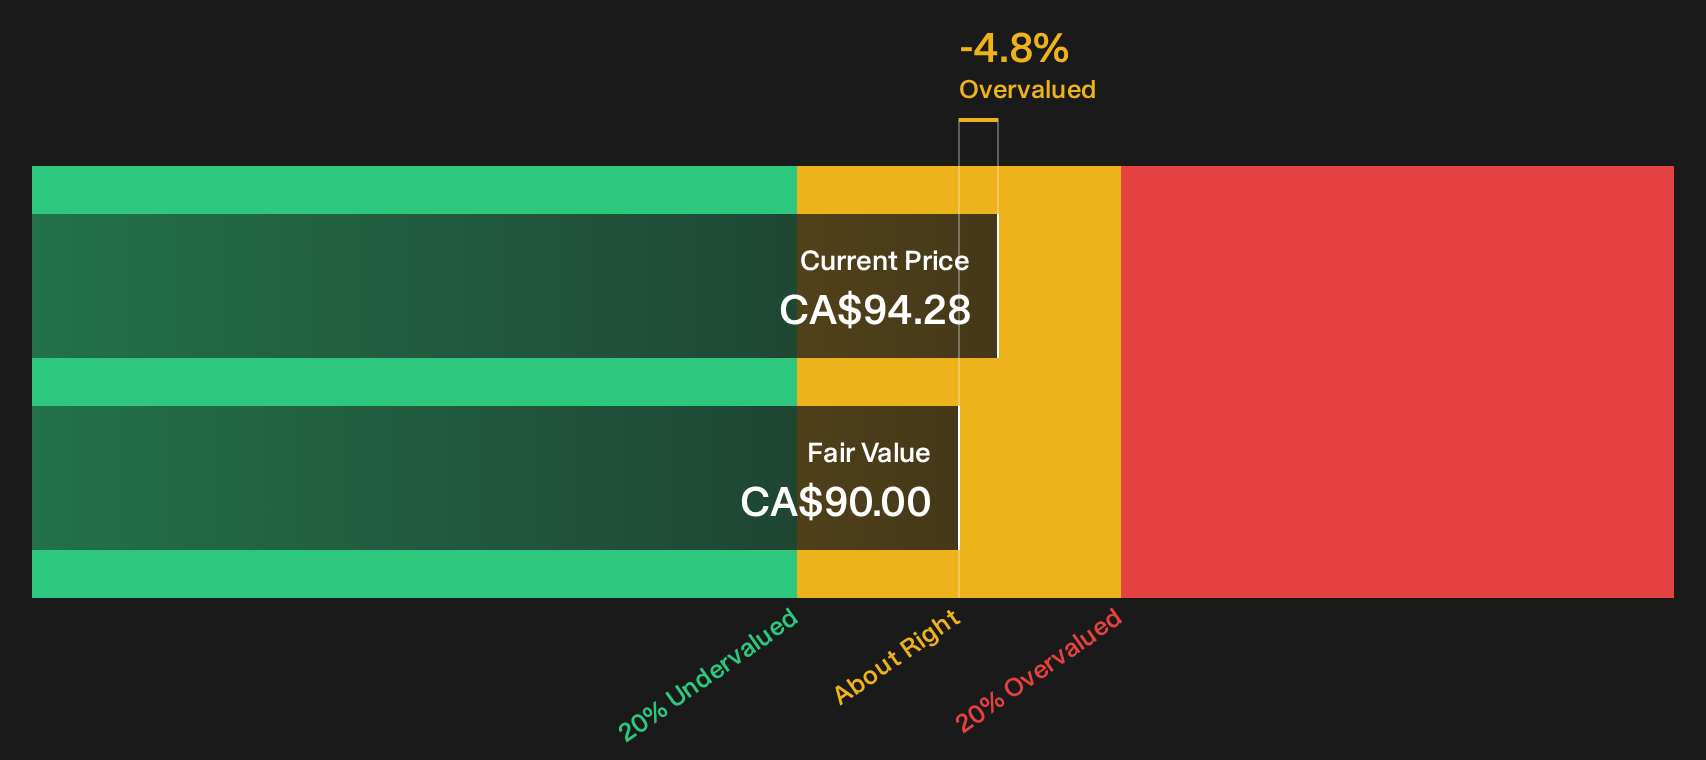
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Corporation of Canada for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Power Corporation of Canada is clearly mixed. Move quickly, review the key drivers for yourself, and weigh both sides of the story with the help of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Power Corporation of Canada?
If you like what you see with Power Corporation of Canada, do not stop here. Broaden your watchlist and pressure test your thesis against fresh opportunities.
- Scan for potential value candidates that combine quality fundamentals with marked-down valuations through our curated 5 high quality undervalued stocks.
- Target resilient payers that focus on income strength by reviewing a hand picked set of 1 dividend fortresses.
- Sharpen your downside protection and concentrate on capital preservation with a focused pool of 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com