
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Has Avantor (AVTR) Run Too Far After Its CFO Change?
Avantor (AVTR) just refreshed its financial leadership by appointing Todd Garner as Chief Financial Officer and Executive Vice President, placing a seasoned industry veteran in charge of planning, accounting, capital structure, and investor communication.
A sharp 48.35% 3 month share price return and a 33.07% year to date gain suggest momentum in Avantor is building, even though the 1 year total shareholder return of 28.80% sits against a 3 year total shareholder return decline of 27.66% and a 5 year total shareholder return drop of 63.30%.
Scan how Avantor’s CFO shake-up compares with other lab supply and life sciences players by lining up the finance focused opportunities in our hand picked list of solid balance sheet and fundamentals (24 results).
Avantor now trades around US$15.25, above the average analyst target of US$14.66, while a simple intrinsic cross check still indicates a discount. Where does fair value actually land after this surge and CFO reset?
Most Popular Narrative: 5% Overvalued
Avantor is trading around $15.25 against a widely followed fair value estimate of $14.56, so the narrative framework now treats the stock as slightly ahead of that modeled worth while still hinging on a turnaround story that leans heavily on sector demand and self help.
The global growth in demand for biopharmaceuticals and healthcare solutions is being reinforced by Avantor's major contract wins and extensions with large pharma and biotech consortia. These positions Avantor to capture greater market share as end-market funding and patient procedures return to normalized or higher levels, creating sustained potential for above-market revenue growth.
See why 10 investors see Avantor as 5% overvalued.
The fair value work behind that $14.56 figure leans on a discount rate of 8.77%, modest revenue growth assumptions around 2.8% a year, and a shift in profit margin from a current loss of $578.0m toward a 9.1% margin profile over time. That framework also assumes Avantor eventually trades on a P/E of 19x once earnings reach $651.0m, which is lower than the 37.4x multiple used for the broader US Life Sciences group in the same narrative.
Against that backdrop, the current price sitting above the consensus target while our own intrinsic cross check signals a 10.2% discount to $16.99 leaves investors weighing two different valuation anchors and deciding which set of inputs they trust more, the conservative Street model or the cash flow driven approach.
Result: Fair Value of $14.56 (OVERVALUED)
Still, the narrative around Avantor can unravel if aggressive pricing to win large contracts keeps compressing margins, or if bioprocessing headwinds persist longer than analysts expect.
Find out about the key risks to this Avantor narrative.
Another View: Avantor Looks Cheap On Sales
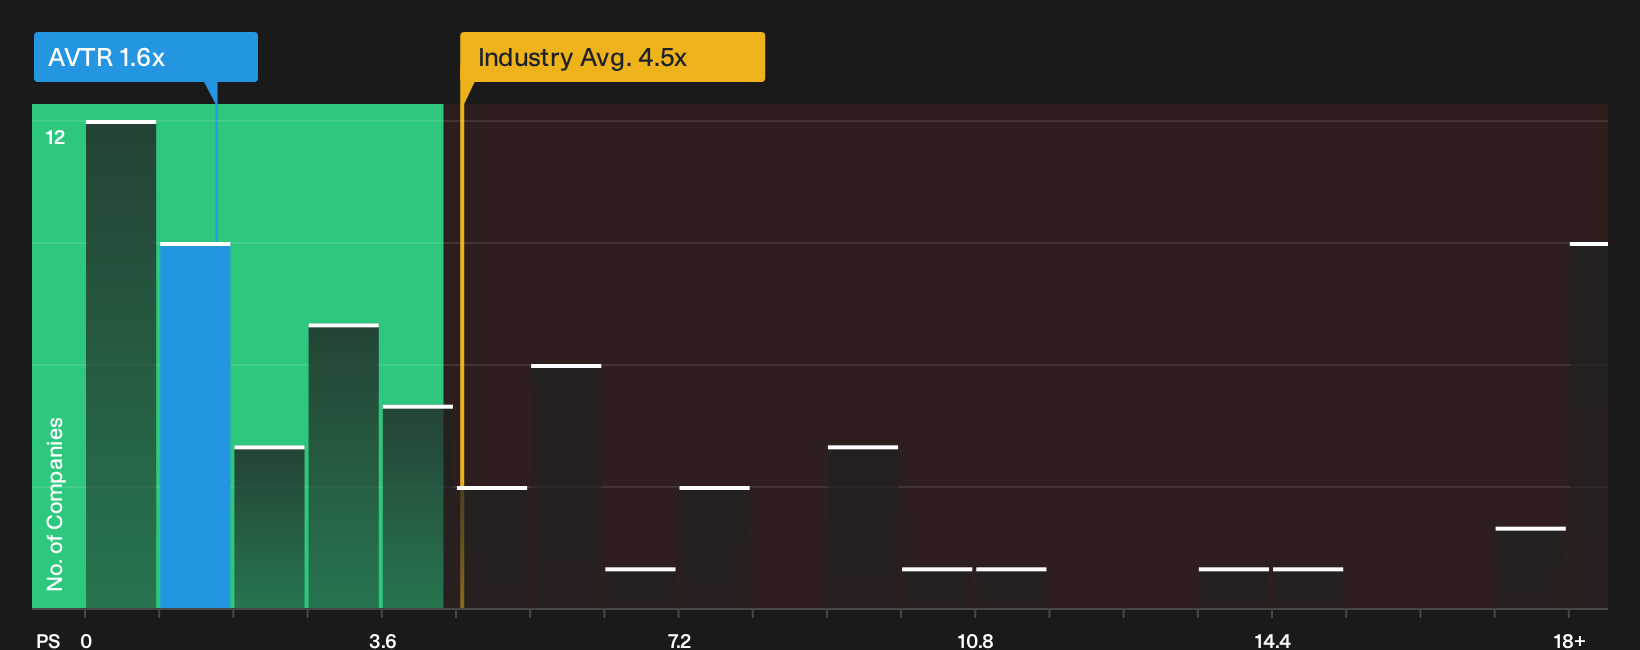
The earlier fair value work estimated Avantor as roughly 5% overvalued at $14.56. Looking at a simple sales-based valuation tells a very different story. The stock trades on a P/S of 1.6x, while the fair ratio is 3.3x and peers are clustered around 11.3x.
That gap suggests the market is pricing in significant execution risk, giving limited credit for the turnaround plan, and allowing a wide margin for error if cash flow trends align with expectations.
See what the numbers indicate about this price in the valuation breakdown See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Avantor's valuation and fundamentals can feel messy, so move quickly, test the assumptions against your own thresholds, and weigh the balance of risks and potential upsides with the 3 key rewards and 1 important warning sign.
Looking for more Avantor sized investment ideas?
If Avantor has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist now so you are not chasing every move later.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) before the next bout of volatility catches you unprepared.
- Hunt for pricing power and potential mispricing by reviewing the 31 high quality undervalued stocks that could fit your return and risk limits more closely than Avantor.
- Identify ideas for income focused portfolios by running through the 8 dividend fortresses and spotting yields that line up with your cash flow goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com