
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PagerDuty (PD) Rebounds Sharply, Is It Already Fully Priced?
PagerDuty (PD) has attracted fresh attention after a recent price move that left the stock up about 18% over the past month and close to 58% over the past 3 months.
That sharp move has come on top of a 17.97% 1 month share price return and a 58.20% 3 month share price return, yet PagerDuty’s 1 year total shareholder return is still down 10.85% and the 5 year total shareholder return is down 66.00%. Recent momentum is therefore building from a weak longer term base and may reflect shifting expectations around growth potential and risk rather than a clean recovery story.
Compare the recent move in PagerDuty shares, which follows a weak long-term base, with other stocks showing fresh momentum by scanning our hand picked 16 high quality undiscovered gems.
PagerDuty has gone from a long slide to a sharp rebound, which puts you in a simple bind. Step in after this jump, or wait until the valuation case looks cleaner.
Most Popular Narrative: 14% Overvalued
PagerDuty last closed at $14.38, while the most followed narrative pegs fair value at $12.64 using a 9.5% discount rate. That gap frames the recent rebound as richer than the underlying cash flow story implies.
The transition from seat-based to usage-based pricing models, validated by rapid growth in usage-based product lines and strong initial customer feedback, aligns future topline growth more closely with actual customer value realization. This sets the stage to reaccelerate ARR growth and improve net retention as automation reduces per-seat dependency.
See why 18 investors see PagerDuty as 14% overvalued.
Result: Fair Value of $12.64 (OVERVALUED)
Still, the PagerDuty story can break the wrong way if usage based pricing makes customer spending more volatile, and if aggressive rivals pressure margins and renewal terms.
Find out about the key risks to this PagerDuty narrative.
Another View on PagerDuty’s Valuation
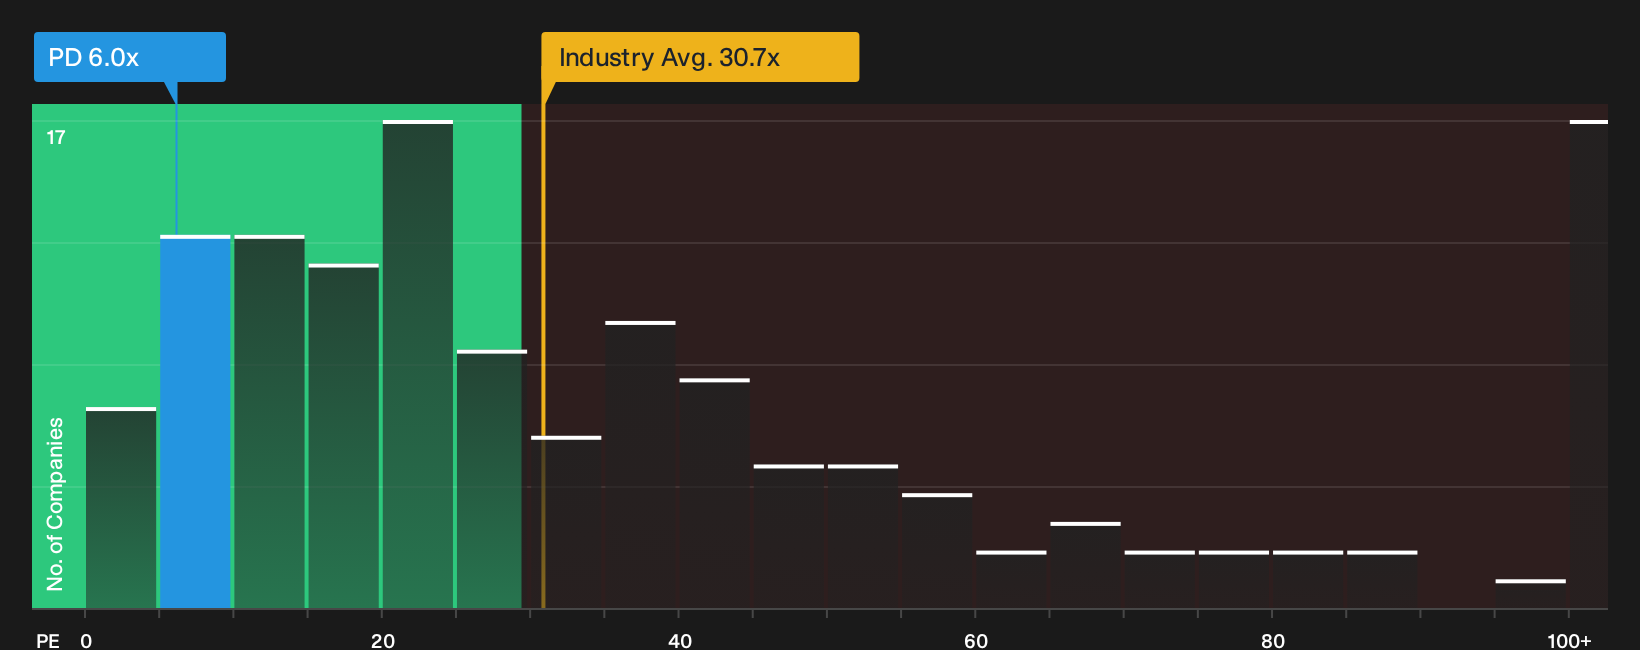
Analyst narratives frame PagerDuty as 14% overvalued at $14.38 versus a $12.64 fair value, yet the current P/E of about 6x tells a very different story. That ratio sits well below the US Software industry at 30.7x, the peer average at 41.5x, and even the fair ratio of 6.3x. This points to relatively low expectations already baked into the price. The real question is whether you think the business will grow into those sector and peer multiples, or stay closer to that fair ratio.
To pressure test those assumptions against the earnings multiple and what the market could move toward, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around PagerDuty’s valuation and risk profile can feel messy. Act while the data is fresh and reach your own judgment using the 3 key rewards and 2 important warning signs.
Looking for more PagerDuty investment ideas?
If PagerDuty has you rethinking where the best risk and reward might be hiding, do not stop with a single ticker when a broader watchlist could sharpen your edge.
- Target resilient uptrends by scanning a curated mix of strong balance sheets and fundamentals with the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by running through a focused set of potential bargains using the 31 high quality undervalued stocks.
- Lock in potential income streams by reviewing companies built around higher yields and staying power through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com