
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is AB SKF (OM:SKF B) Fully Valued After Its PLP Launch?
AB SKF (OM:SKF B) has just rolled out its new Progressive Lubrication Pump (PLP), a modular automatic system aimed at improving machine reliability, reducing manual maintenance, and enhancing visibility into lubrication performance.
Recent trading suggests interest in AB SKF is firming, with a 2.25% 1 day share price gain and a 10.47% 90 day share price return. The 1 year total shareholder return of 19.17% and 3 year total shareholder return of 63.29% point to momentum that extends beyond this latest product launch.
Scan beyond AB SKF and compare it with 93 robotics and automation stocks reshaping industrial automation and reliability.
AB SKF has just rallied on the PLP launch and carries a mixed recent return profile, so the live question is whether that move justifies paying up now or waiting for a clearer margin of safety as the numbers are weighed.
Most Popular Narrative: 2% Overvalued
The most followed narrative for AB SKF pegs fair value at SEK266.06, slightly below the last close at SEK272.10. The recent PLP bump therefore sits on top of an already full valuation framework that leans on automation and robotics execution.
The ongoing automation and digitalization of manufacturing, along with AB SKF's continued investments in automation, manufacturing regionalization, and rightsizing are expected to enhance operational efficiency and support sustained improvements in operating and EBITDA margins over the next several years. The expansion and modernization of the industrial segment now contributing 72% of sales and 89% of adjusted operating profit positions SKF to benefit from the global push for energy efficiency and sustainability, driving future revenue growth from advanced, energy-efficient bearing solutions.
See why 21 investors see AB SKF as 2% overvalued.
Result: Fair Value of SEK266 (OVERVALUED)
Still, the story around AB SKF can change quickly if the automotive separation drags on or if restructuring costs weigh more heavily on margins than expected.
Find out about the key risks to this AB SKF narrative.
Another View On AB SKF Valuation
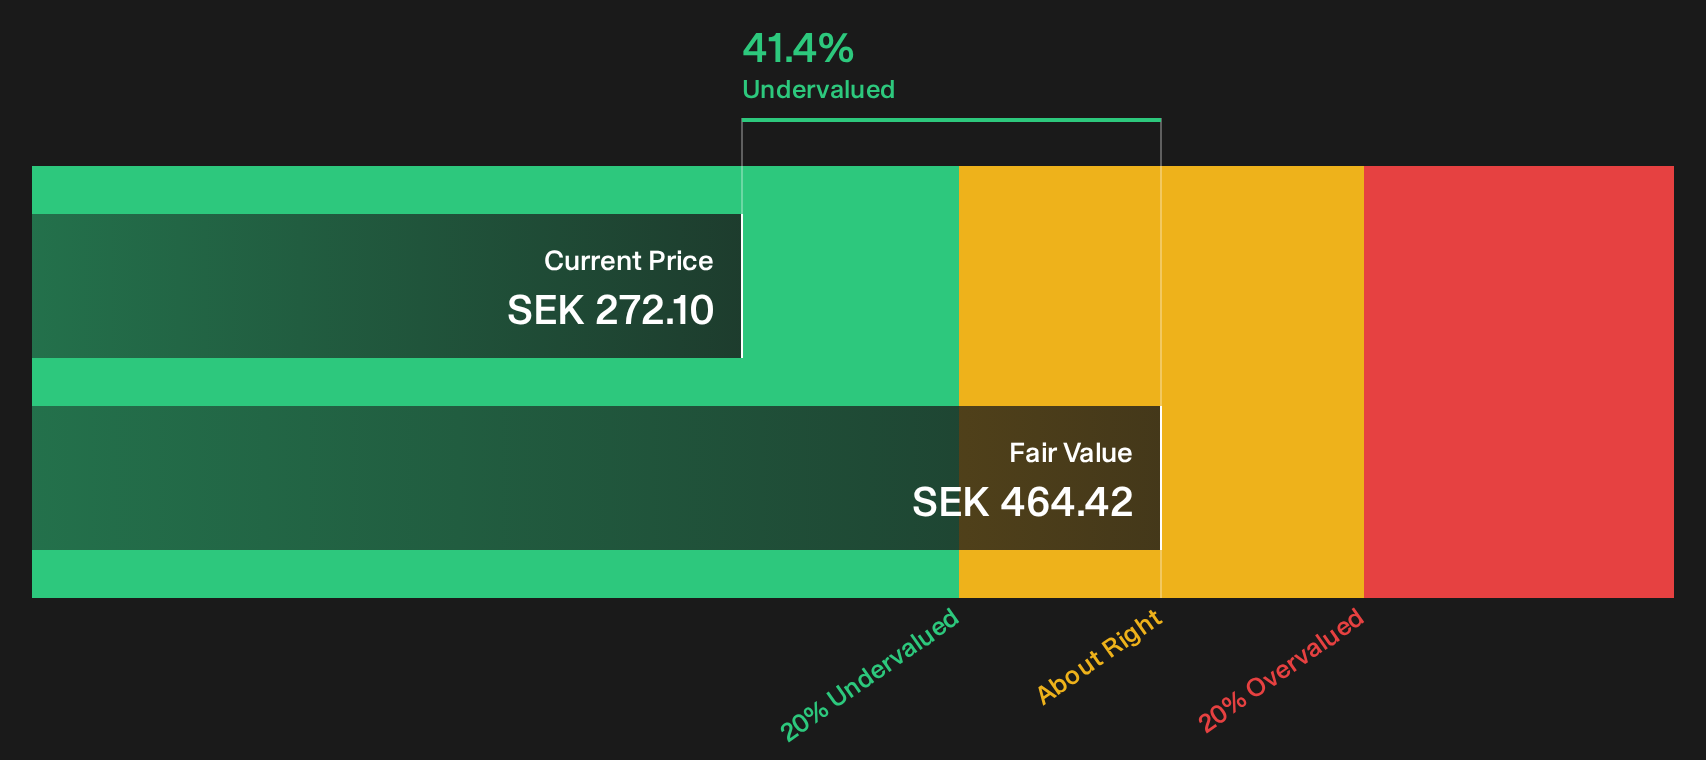
The narrative around AB SKF being about 2% overvalued on a fair value of SEK266 contrasts with a very different message from our DCF model. On future cash flows, the shares screen as trading about 41.4% below an estimated value of SEK464.42, which points to a wide gap in what investors are currently willing to pay.
That kind of split between a relatively tight analyst target range and a much higher DCF output raises a simple question for you: Is the constraint on AB SKF the assumptions going into the model, or the market's willingness to price long term cash flows more generously if execution improves?
If you want to see how those cash flow assumptions get built up in detail, walk through the SWS DCF model and test where your own expectations sit against it, then Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed signals on AB SKF's value can be useful, not paralysing, if you move quickly to stress test the thesis against both upside and downside. To pressure test that balance directly, weigh the 2 key rewards and 1 important warning sign.
Looking for more AB SKF style investment ideas?
If you are serious about putting capital to work, do not stop with AB SKF. Use focused screeners to surface ideas you might otherwise miss.
- Target resilient compounding potential by scanning a 228 resilient stocks with low risk scores that score well on stability when markets get choppy.
- Hunt for mispriced quality by reviewing a 620 high quality undiscovered gems that pair strong fundamentals with limited attention.
- Strengthen portfolio durability by focusing on a list of solid balance sheet and fundamentals (202 results) that can better handle funding pressure or profit swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com