
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SAP (XTRA:SAP) Could Be 10% Undervalued As Cloud Revenue Jumps 24%
Recent headlines around SAP (XTRA:SAP) are being shaped by a 24% jump in cloud revenue in Q2, fresh AI product launches, and new collaborations such as Wipro’s STO360 solution with Aramco.
Those AI updates and cloud launches are feeding into the share price story too, with SAP’s stock at €185.92 after a 37.6% 90 day share price return. This contrasts with a year to date decline of 7.9% and a 1 year total shareholder return down 16.0%, even as the 5 year total shareholder return of 73.7% points to stronger momentum over a longer stretch.
Spot potential peers riding the same AI and cloud tailwind by scanning our hand picked 87 AI infrastructure stocks before you move on from SAP's latest update.SAP has already delivered a sharp rebound. At the same time, the recent surge in cloud and AI headlines hints that the debate is only starting. Is most of the upside already priced in, or is the valuation still catching up?
Most Popular Narrative: 10% Undervalued
On the most followed view of SAP, a fair value of about €207 per share sits meaningfully above the latest close at €185.92. This puts the recent cloud and AI excitement into sharper context.
The accelerating global push for digital supply chain resilience and business process digitalization is enlarging SAP's addressable market, as evidenced by record cloud backlog, robust new pipeline development (including post-Sapphire event momentum), and consistently strong double-digit growth in cloud ERP. Deepening strategic partnerships (e.g., Alibaba in China) are unlocking new high-growth markets and lowering customer acquisition costs, setting up SAP for faster geographic expansion and further topline acceleration.
See why 207 investors see SAP as 10% undervalued.
Result: Fair Value of €207 (UNDERVALUED)
Still, the SAP story can change quickly if cloud backlog growth slows or if rising AI and compliance costs eat into those projected margin gains.
Find out about the key risks to this SAP narrative.
Another View: SAP Through The P/E Lens
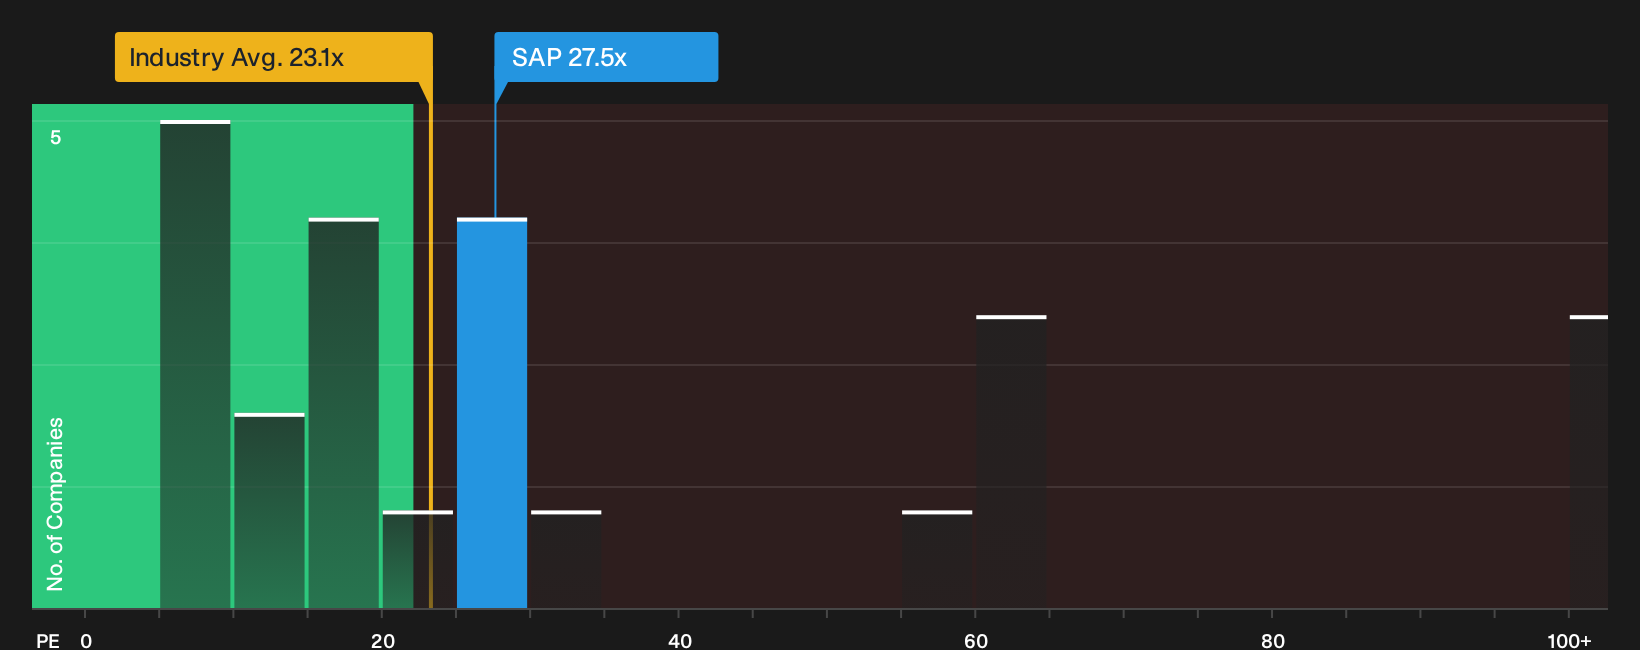
There is a catch. While the narrative fair value suggests SAP is undervalued, the current P/E of 27.5x looks expensive next to the European software group at 23.1x and a peer average of 19.8x. The fair ratio of 35.7x points to a wide valuation range that cuts both ways. Is that a margin of safety or a sign of higher risk if sentiment cools?
Before relying on any single yardstick, it helps to see how the numbers compare across different valuation checks, rather than focusing only on headline multiples. Our breakdown sets out SAP's pricing relative to its earnings power. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If SAP's mix of AI optimism and rich P/E multiples leaves you undecided, move quickly and stress test the thesis against the detailed reward breakdown. To balance the upbeat narrative with the underlying data, review the 3 key rewards.
Looking for more investment ideas beyond SAP?
You have seen how SAP stacks up. Now widen your playbook and pressure test your next moves with a few targeted screens that surface very different types of opportunities.
- Target reliable income streams by checking companies that currently screen as potential 161 dividend fortresses.
- Hunt for misunderstood opportunities by reviewing a focused set of 620 high quality undiscovered gems before they attract wider attention.
- Prioritise capital preservation by scanning 228 resilient stocks with low risk scores that pair resilience scores with cleaner financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com