
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Applied Aerospace & Defense (AADX) Showing With Record Revenue And Backlog?
- Applied Aerospace & Defense (NYSE:AADX) reported record quarterly revenue and backlog in its first update as a newly listed company.
- The business posted a net loss for the period, driven by one-time compensation charges and IPO related offering expenses.
- Management highlighted the use of IPO proceeds to support organic growth initiatives and to deepen commitments on existing defense contracts.
- This combination of record revenue and backlog, alongside an IPO driven net loss, is worth weighing against the rest of our findings. Take a look at 2 warning signs we have identified for Applied Aerospace & Defense.
For a broader view on how automation and defense spending intersect, compare Applied Aerospace & Defense with peers in 93 robotics and automation stocks.
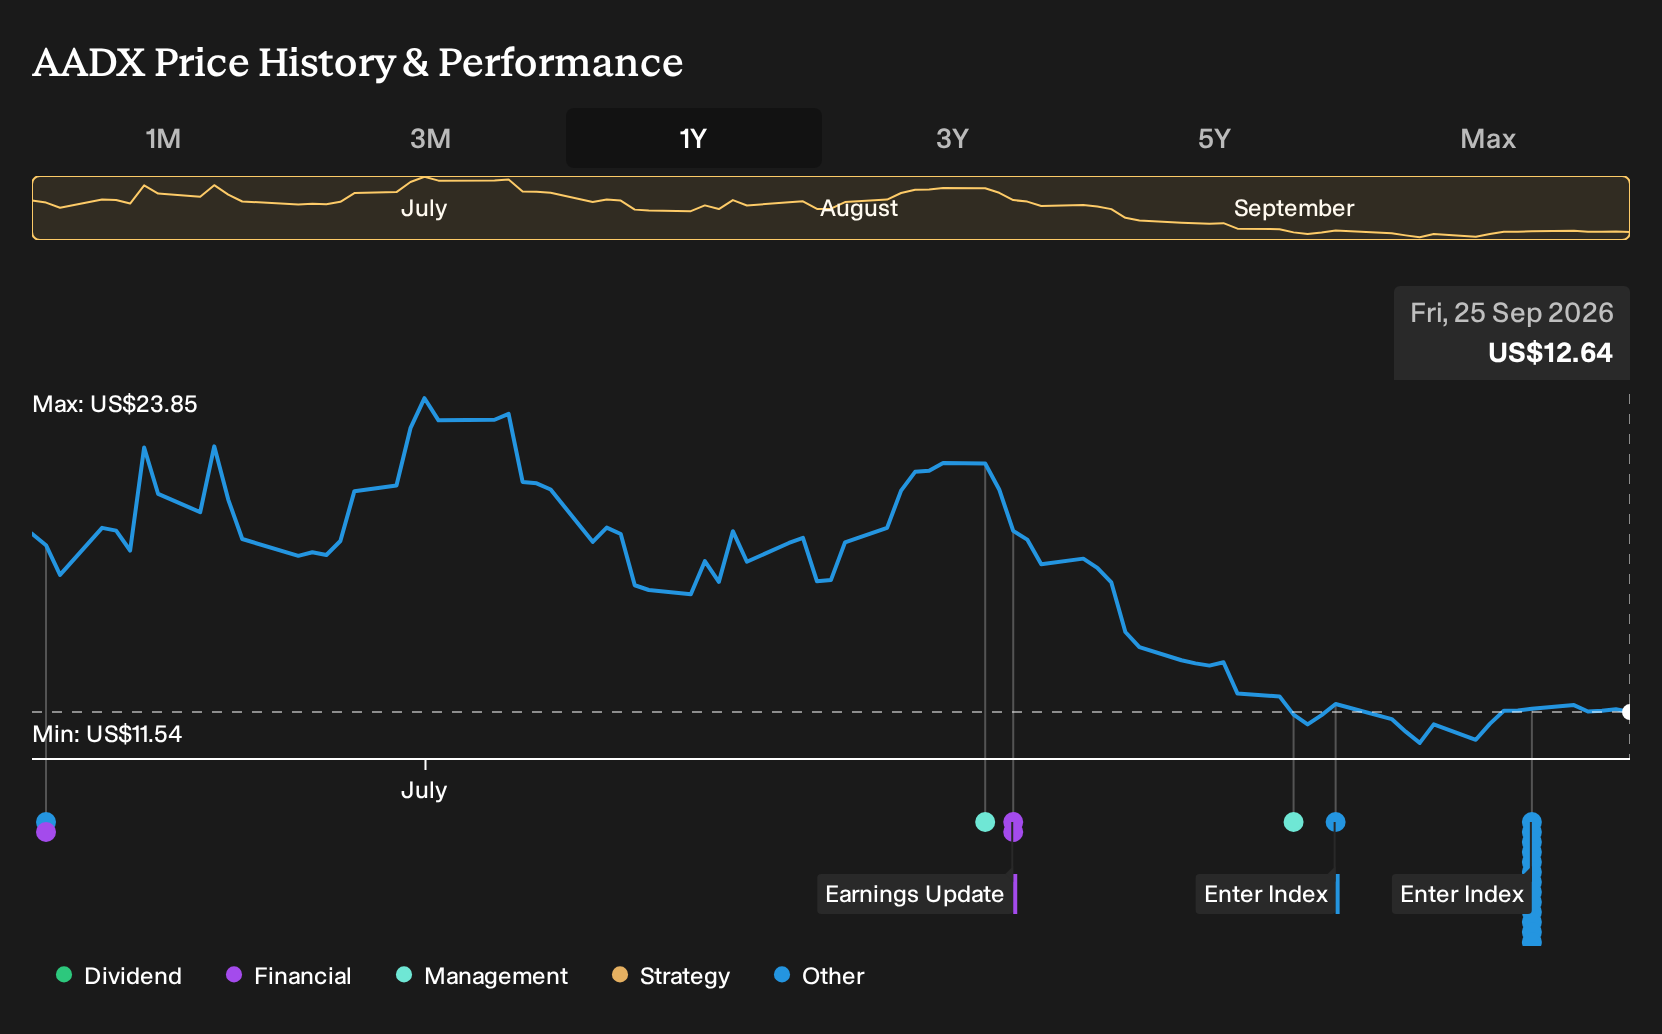
Applied Aerospace & Defense designs and builds integrated subsystems for space and defense programs, putting it squarely in the complex hardware supply chain behind government and commercial missions. That positioning helps explain why record contracted work and fresh IPO capital matter for how its backlog translates into future activity.
See which insiders are buying and selling Applied Aerospace & Defense following this latest news.
Why does record revenue and backlog matter if Applied Aerospace & Defense reported a loss?
Record sales and a US$1.13b contract backlog show that Applied Aerospace & Defense has substantial contracted work in hand, even as one time IPO and compensation costs pushed the quarter into the red. The bigger question for you is how efficiently that backlog converts into cash and profitability once those temporary charges roll off.
Does this news change the Applied Aerospace & Defense Narrative?
The update lines up closely with the existing Narrative, which focuses on a backlog of more than US$1.1b and roughly 40% spare capacity across 11 facilities as key drivers. Strong contracted work and fresh IPO proceeds both support the idea that the business has the workload and footprint to serve the space and defense programs highlighted in that thesis, while execution risks around new program ramps remain important to monitor.
See how these catalysts shape Applied Aerospace & Defense's path to a $25.14 fair value.
What should investors watch next to see if this is really working?
One early indicator is how quickly contract backlog and the US$3.8b weighted pipeline translate into higher adjusted EBITDA and stronger operating cash flow in the next few reporting periods. It may also be useful to track management commentary on margin trends as collaborative combat aircraft, MV-75 and Precision Strike programs move through their early learning curves.
What long range forecasts are really implying about Applied Aerospace & Defense
Short term updates only tell part of the story, because the longer range estimates sketch a very different destination for Applied Aerospace & Defense than this quarter suggests on its own. See where analysts expect Applied Aerospace & Defense to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com