
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Blue Owl Capital (OWL) Stock Still Looks Pricey As Loan Loss Risk Looms
Blue Owl Capital has seen its share price fall sharply over the past year, and that slide puts fresh focus on whether the current US$9.32 level still lines up with what its earnings can support. For anyone tracking the stock, the question now is how much of the recent news flow is already reflected in that earnings based valuation story.
- The stock is down 43.3% over the past year, which puts recent earnings power under the microscope and raises the issue of how the market is weighing those results.
- The possible loss of a junior loan in the Loparex restructuring on one side, and the expansion of Blue Owl’s credit facilities and real assets activity on the other, can both influence how investors think about future income and the risk attached to those cash flows.
- The analysts covering Blue Owl Capital have run their own numbers. See what analysts think Blue Owl Capital's shares could be worth.
The issue now is whether Blue Owl Capital’s current share price is adequately explained by its earnings when you line it up against the Fair Ratio benchmark.
If this Blue Owl Capital story has you rethinking how earnings and risk show up in prices, a focused screen of 31 high quality undervalued stocks can be a useful next starting point for research.
Does Blue Owl Capital Look Pricey on Earnings?
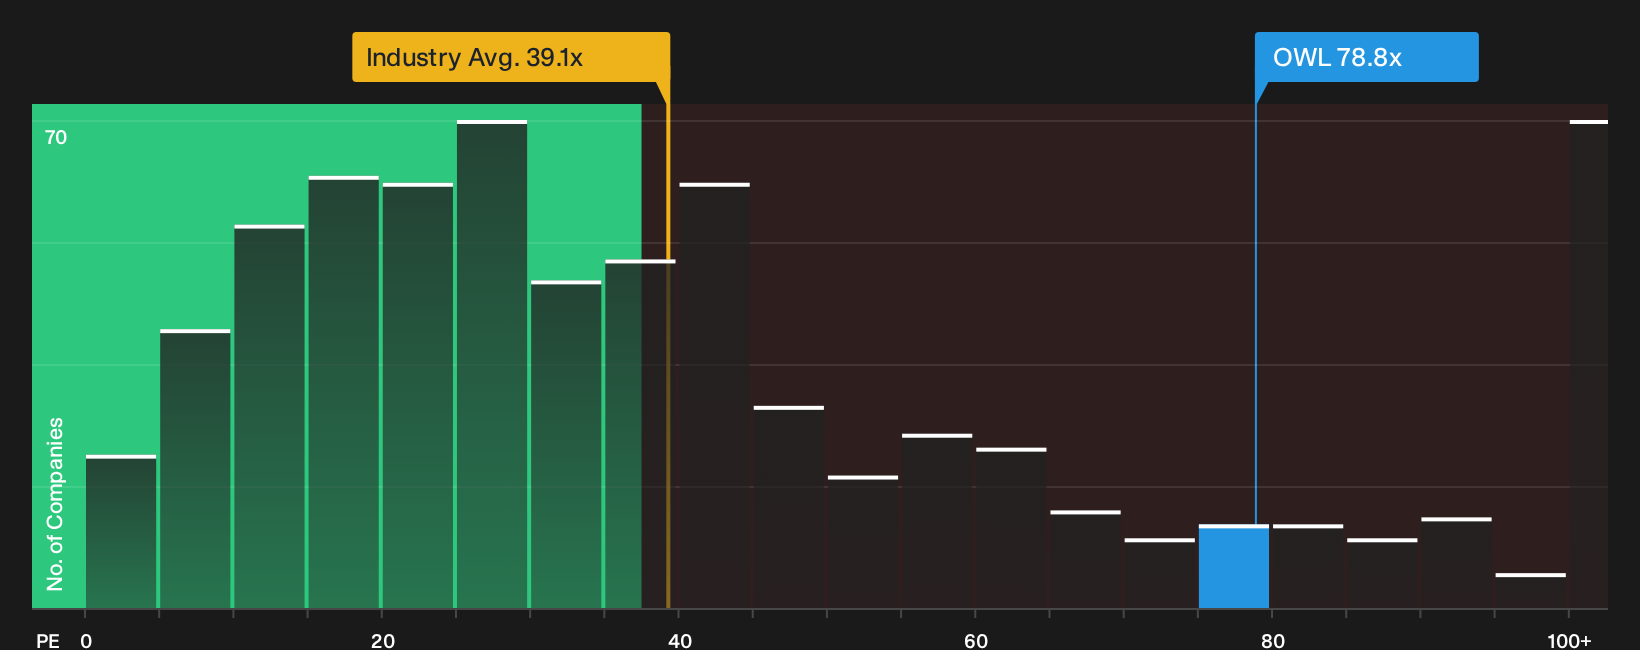
The P/E ratio is a useful lens for Blue Owl Capital because earnings are a key driver of how investors value capital markets groups. On this measure, the stock trades at about 78.8x earnings, which is roughly double the capital markets industry average of 39.1x and well above the peer basket at 30.5x.
The Fair Ratio model, which blends the company’s own profitability, risks, size and sector traits, flags that Blue Owl Capital screens overvalued on earnings and that the gap is very wide. The framework is heavily penalising the firm’s risk profile and the quality of recent earnings, so the result is better read as a warning signal rather than a precise target. Because the potential loss on the Loparex junior loan sits alongside high profile credit and real assets deals, the current P/E suggests investors are still paying a premium for Blue Owl Capital’s earnings despite that mixed news flow. Explore the numbers behind Blue Owl Capital's P/E valuation.
The Blue Owl Capital Narrative: What Would Justify Today's Price?
Narratives on Blue Owl Capital pick up where this valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on Simply Wall St's Community page. Each scenario links its number to a clear view on how Blue Owl Capital's growth, margins and risk profile might evolve, so you can revisit those assumptions as fresh information arrives.
One of the top community narratives on Blue Owl Capital: 27% undervalued
"Exceptional long-term opportunities in digital infrastructure, fueled by generational investment in data centers and AI-related assets where Blue Owl has industry leadership, are catalyzing large-scale fundraising…"
Discover why this Narrative puts Blue Owl Capital at 27% undervalued.
Before you decide on Blue Owl Capital, there is one more lens worth checking
Price and earnings only tell part of the story for Blue Owl Capital, since professional analyst projections offer a separate view of where profits and risks might sit a few years from now. Explore where analysts expect Blue Owl Capital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com