
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Autonomous Quarry Expansion Just Shift Caterpillar (CAT) Stock Narrative?
- Luck Stone and Caterpillar expanded autonomous hauling to two more Virginia quarries after autonomous trucks at Bull Run moved over 3.5 million tons since November 2024. This marks the first deployment of Caterpillar's haulage solution on Cat 775 trucks.
- Caterpillar's push to pair autonomy with operator training, dealer support and quarry process changes points to a broader shift toward technology-heavy, skills-based roles in heavy equipment operations.
- We will look at how Caterpillar's investment narrative is affected by this earnings momentum story and the Luck Stone autonomy expansion.
Scan beyond Caterpillar to identify other industrials investing in automation and AI infrastructure by reviewing the hand picked 87 AI infrastructure stocks that may influence the next wave of heavy equipment demand.
Caterpillar Investment Narrative Recap
For an investor to stay with Caterpillar, the core belief is that heavy equipment, services and autonomy can turn a very large installed base and record backlog into consistent cash generation, even while tariffs, pricing pressure and geopolitics bite into margins. The short term swing factor remains how effectively that backlog converts into shipments and profits without eroding pricing power.
The Luck Stone expansion shows Caterpillar is not only selling iron but also embedding autonomy, services and dealer support into quarry workflows. That supports the long term thesis, but does not fundamentally change the near term risk that new tariffs, weak regions or discounting in Construction and Resource Industries could pressure operating margins and earnings volatility.
The most relevant recent update for this autonomy story is the Luck Stone announcement itself, which highlights Caterpillar autonomous trucks hauling more than 13 billion tonnes globally with no reported injuries while operating. That scale matters for investors watching whether autonomy is a niche project or a real operating platform that can feed services, software and replacement parts over time.
Expanded deployment on Cat 775 fleets at Boscobel and Bealeton, supported by dealer Carter Machinery, turns autonomy into a test case for how Caterpillar executes in quarry markets beyond mining. For catalysts, investors are watching whether similar projects help support record backlog conversion in Resource Industries while balancing key risks around tariffs, pricing pressure and region specific demand softness.
Caterpillar's analyst narrative points to revenues of US$94.5b and earnings of US$17.4b by 2029, based on a projected 10.1% yearly revenue growth rate and an increase in earnings from US$9.4b today to US$17.4b, which represents roughly an 85% rise in profit over the period.
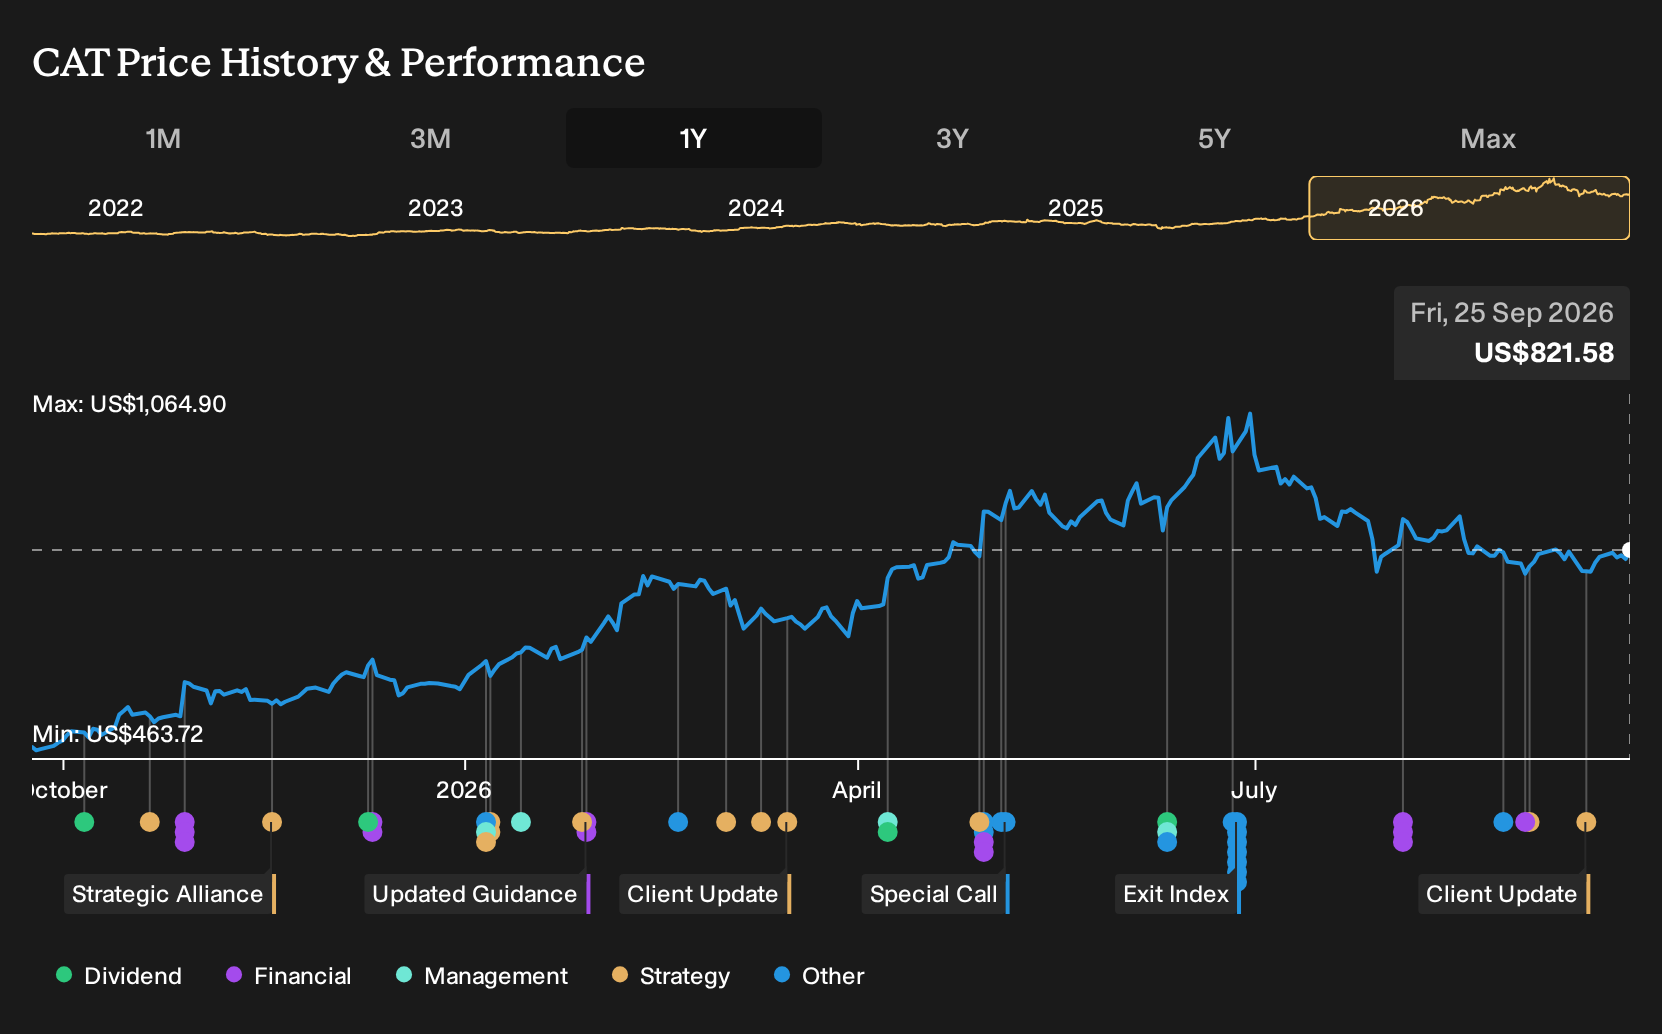
Uncover how Caterpillar's fair value indicates an 18% potential upside to its current price that could narrow quickly as investors reassess Caterpillar's autonomy story.
Exploring Other Perspectives
One upbeat angle on Caterpillar focuses on backlog driven operating leverage. The most optimistic analysts were already modelling revenue growth of 16.6% a year and earnings reaching about US$20.7b by 2029. You can treat the Luck Stone autonomy expansion as a fresh data point that might push those assumptions either higher or lower as views evolve.
Explore 8 other Caterpillar fair value estimates, including one that suggests a potential upside of as much as 19% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and research.
- A great starting point for your Caterpillar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Caterpillar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Caterpillar's overall financial health at a glance.
Looking For More Investment Ideas Beyond Caterpillar?
Once you have a view on Caterpillar, it can help to cross check that thesis against other businesses with different balance sheets, income profiles and risk levels using the Simply Wall St Screener.
- If you want income to play a bigger role in your plan, review a curated set of higher yielding payers through 8 dividend fortresses that combine sizeable distributions with fundamental checks.
- For a focus on quality and staying power, scan companies with stronger financial footing by running through the list of solid balance sheet and fundamentals (24 results) and compare their resilience to cyclical names like Caterpillar.
- If you are hunting for potential future leaders that are not yet widely followed, cast a wider net using the 16 high quality undiscovered gems to spot lesser known businesses with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com