
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
On Holding (ONON) Signs Kylian Mbappé, Is The Upside Already Priced In?
What Mbappé’s deal means for On Holding stock
The trigger for On Holding (NYSE:ONON) right now is clear. The company has signed Kylian Mbappé to help launch its first football boots and apparel, extending the brand beyond its running and tennis roots.
Recent trading tells a mixed story. On Holding’s share price is up 9.9% over the past week, yet still down 36.2% year to date, with a 1-year total shareholder return that has declined 29.5%. This points to fading momentum over the past several months despite the Mbappé announcement and other corporate moves such as the newly authorized share repurchase plan.
Compare On Holding’s Mbappé-fuelled push into global sportswear with other potential breakouts by scanning our hand picked 16 high quality undiscovered gems across consumer and growth-focused sectors.
Bulls see On Holding’s Mbappé deal, double digit revenue and net income growth, and a US$1.0b buyback as mispriced strength. Bears point to the sharp share price decline. Which side does the valuation math support next?
Most Popular Narrative: 30% Undervalued
On Holding’s most followed narrative points to a fair value of $42.55 against a last close of $29.96, which puts the Mbappé deal into a wider story about premium branding, direct relationships with customers, and the price investors are currently willing to pay for that mix.
The acceleration in DTC (Direct-to-Consumer) and e-commerce channels, with DTC reaching new highs (41.1% of sales in Q2 and up 54% YoY), gives On more control over brand, pricing, and customer data while increasing gross and EBITDA margins, an operational catalyst likely to further expand profitability as DTC continues its mix shift.
See why 116 investors see On Holding as 30% undervalued.
Result: Fair Value of $42.55 (UNDERVALUED)
Still, if premium pricing starts to bite consumers or heavy investment in new sports like football fails to pay off, the On Holding story could look very different.
Find out about the key risks to this On Holding narrative.
Another View: What On Holding’s P/E Is Signalling
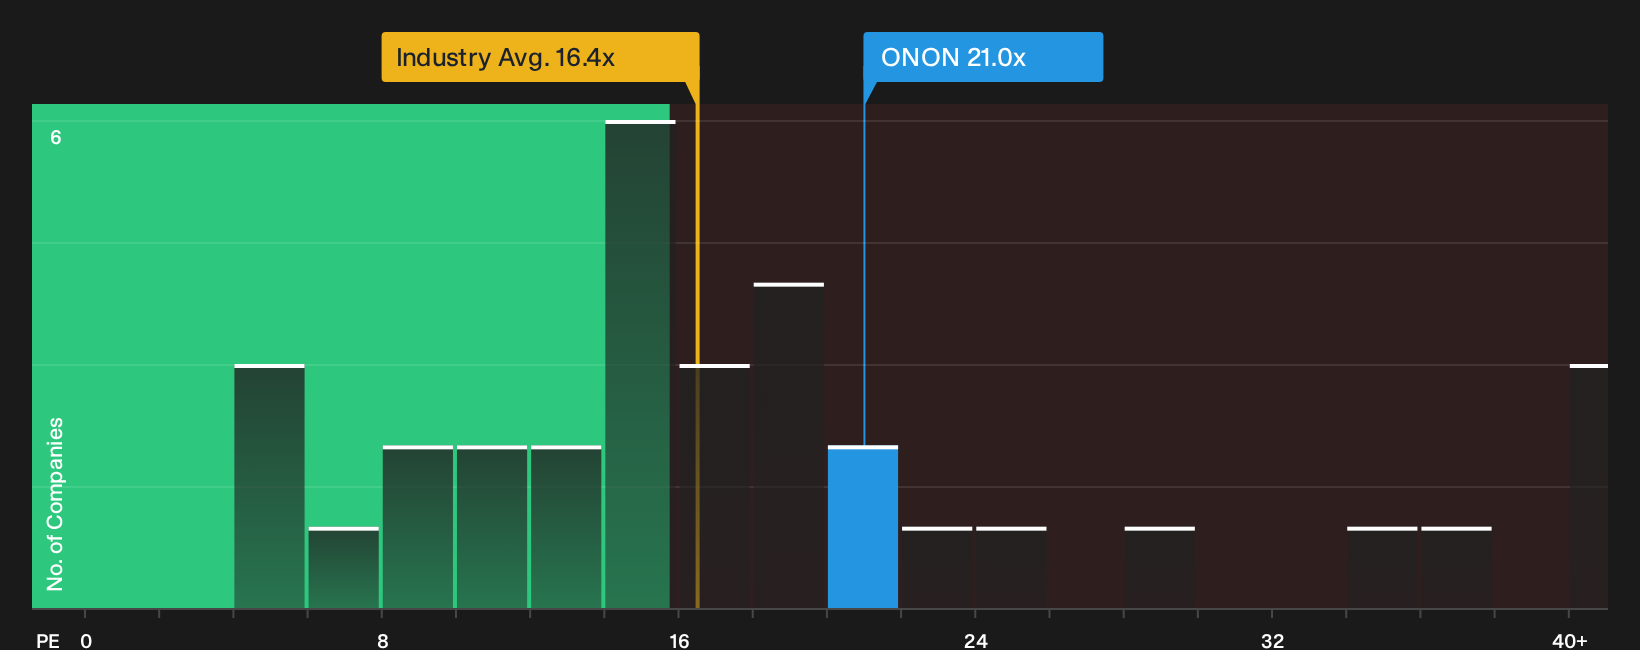
There is a catch. While the earlier narrative leans on fair value and upside, On Holding currently trades on a P/E of 21x, above the US Luxury industry at 16.4x and peers at 14.8x, yet only slightly below its fair ratio of 22.5x. That mix points to a stock where expectations are already pretty demanding. Where does that leave room for error if sentiment turns again?
To see how those expectations stack up against the underlying numbers, and how the current price compares with the ratio the market could move towards over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around On Holding in this article tilts cautiously optimistic, yet your view matters more than any single narrative. Move quickly, test the numbers, and weigh the 3 key rewards.
Looking for more investment ideas beyond On Holding?
If On Holding has sharpened your focus on quality opportunities, do not stop here. Broader idea hunting now can shape your next few years of returns.
- Target potential mispricings by scanning a curated set of companies that combine quality fundamentals with attractive prices using the 31 high quality undervalued stocks.
- Strengthen your income playbook by reviewing businesses with robust yields and payout histories through the 8 dividend fortresses.
- Prioritize resilience by zeroing in on companies screened for solid finances and healthy balance sheets via the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com