
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Christian Dior (ENXTPA:CDI) Faces A Holding Reshuffle, Is The Stock Still Cheap?
Christian Dior (ENXTPA:CDI) drew intense attention after the Arnault family group outlined a restructuring of its holding entities around LVMH, including a planned cash tender offer for minority Christian Dior shareholders.
The restructuring news arrived after a sharp swing in Christian Dior’s momentum, with a 7 day share price return of 12.68% coming against a year to date share price decline of 30.84% and a 1 year total shareholder return down 11.92%. This suggests sentiment has recently improved, but longer term performance has been weak.
Compare Christian Dior’s holding-company shake-up with other potential value plays by scanning our curated list of 181 high quality undervalued stocks that also combine solid cash flows with robust balance sheets.
Christian Dior controls a powerful portfolio of luxury brands, yet the stock has fallen hard this year, even after the tender offer news. Is that business strength now being undervalued, or already fully reflected in the price?
Price-to-Earnings of 16.5x: Is it justified?
Christian Dior screens as inexpensive on a simple earnings yardstick, with a P/E of 16.5x against a last close of €416 and a share price that has fallen sharply this year compared with its recent rebound.
The P/E ratio compares the current share price to earnings per share and helps you see how much investors are paying for each euro of profit. For a diversified luxury group that controls fashion, beauty, spirits, jewelry and retail operations across multiple regions, that single number acts as a shorthand for how the market is weighing durability of cash flows against recent profit trends.
On this measure, Christian Dior looks cheaper than both the peer basket and the broader European luxury set. Management is running on earnings that our data classifies as high quality, yet the 16.5x P/E sits well below the peer average of 30.1x and below the European luxury industry average of 17.9x. This points to the market assigning a lower price tag to each euro of profit than it does for comparable businesses.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 16.5x (UNDERVALUED)
Still, the long share price decline over 1 year and 3 years, along with uncertainty around the Arnault group restructuring, could keep Christian Dior under pressure.
Find out about the key risks to this Christian Dior narrative.
Another View on Christian Dior’s Value
Purely on earnings, Christian Dior looks inexpensive. The SWS DCF model tells a different story. It values the shares at €984.79 per share versus the current €416, which implies a wide gap that could either signal mispricing or very cautious expectations from investors.
Look into how the SWS DCF model arrives at its fair value.
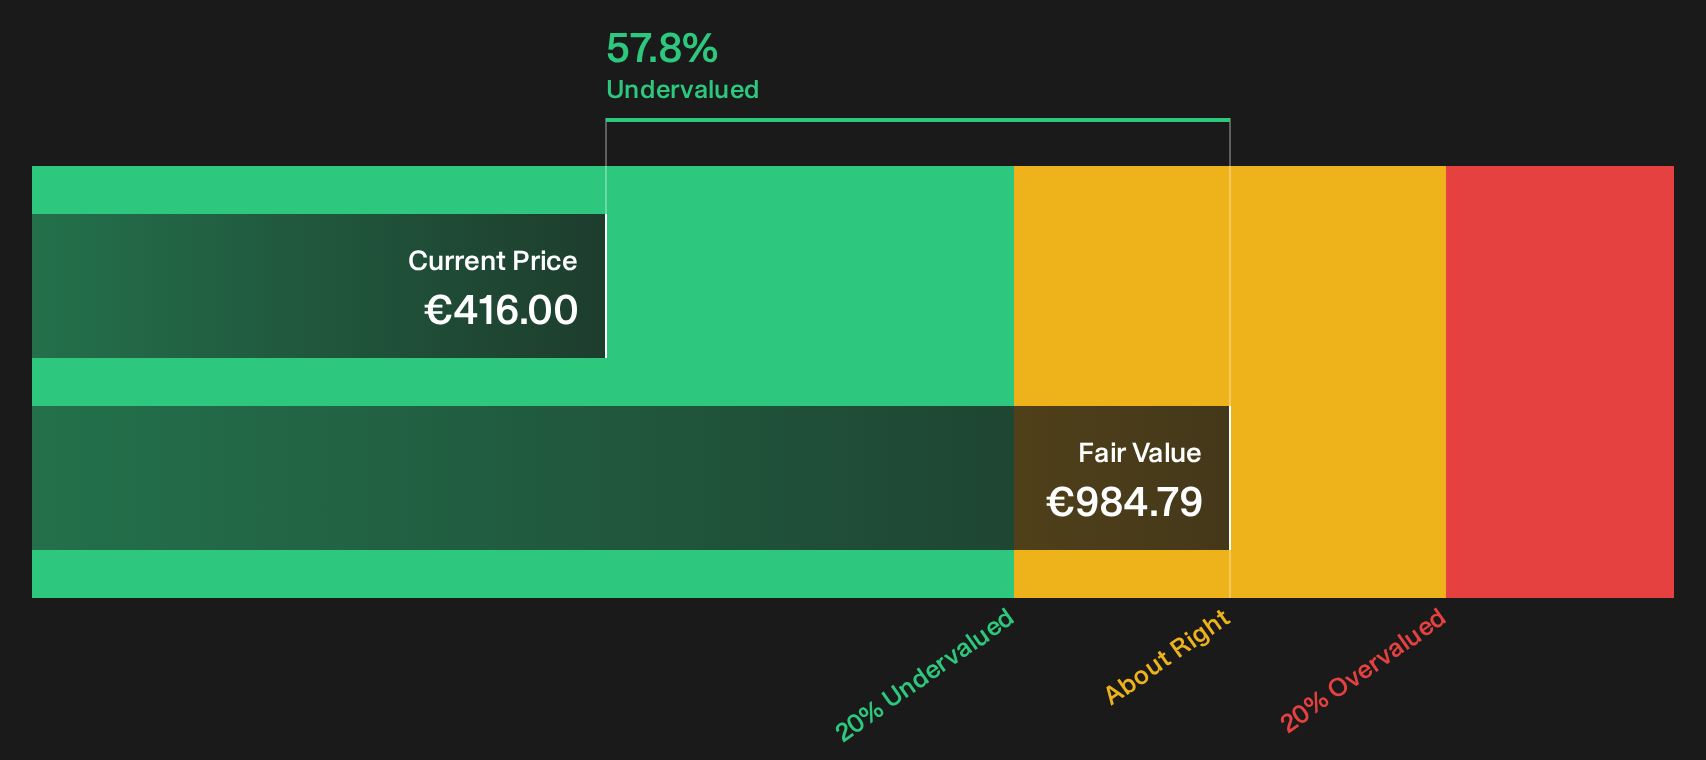
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Christian Dior for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Christian Dior is clearly split, so move quickly, review the data itself and weigh both sides of the story. To frame that decision with a clear view of both risk and potential upside, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Christian Dior?
If Christian Dior has you rethinking value and risk, do not stop here. The wider market still holds plenty of overlooked opportunities that could reshape your portfolio.
- Target steady compounding potential by scanning companies that score highly on resilience through the 227 resilient stocks with low risk scores.
- Hunt for quality at a markdown by reviewing the 181 high quality undervalued stocks that pair strong cash flows with disciplined balance sheets.
- Spot financially healthy operators by checking the list of solid balance sheet and fundamentals (202 results) and avoid missing businesses that keep their foundations tight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com