
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Boyd Group Services Stock (TSX:BYD) $1 Billion Revenue Quarter
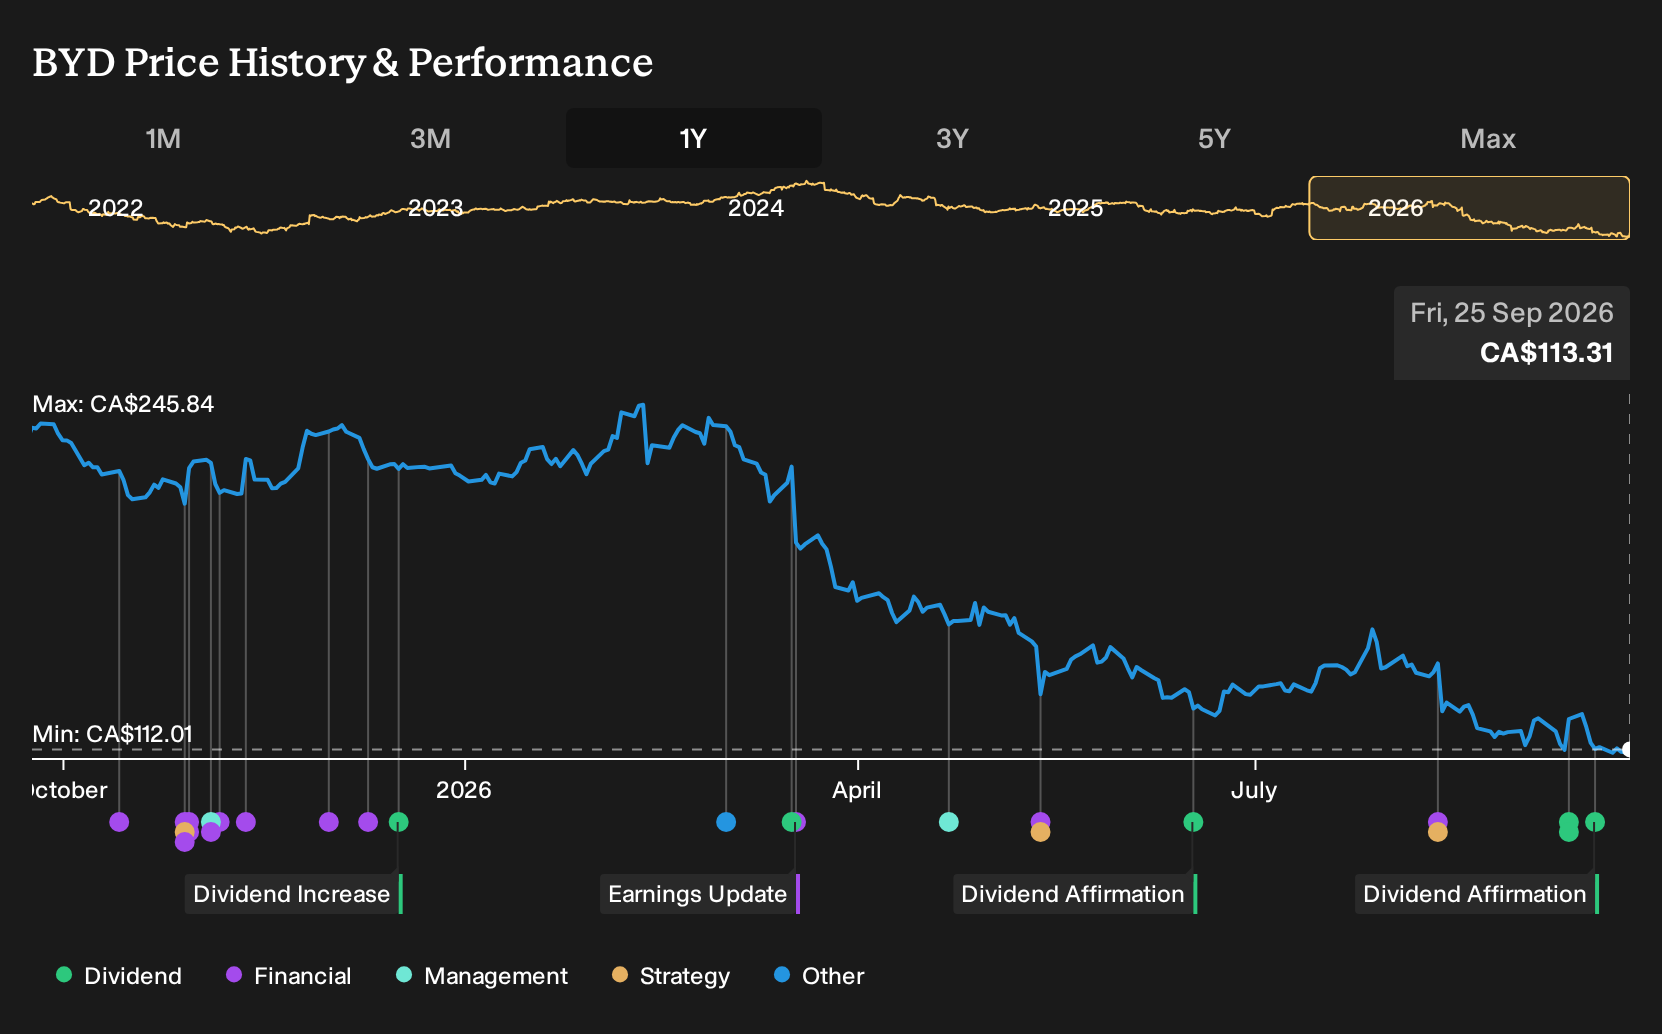
- Boyd Group Services announced a CAD 0.156 per share Q3 2026 cash dividend, alongside a normal course issuer bid to cancel up to 2,779,352 shares, which is 9.98% of its issued equity as of early September 2026.
- Surpassing $1 billion in quarterly revenue while seeing net earnings drop due to acquisition and facility related costs highlights how Boyd Group Services is prioritizing near term scale and integration progress over immediate profit.
- We will now explore how Boyd Group Services' $1 billion quarterly revenue milestone could influence the investment narrative around scale and profitability.
Scan how Boyd Group Services' latest dividend and buyback stack up against peers by reviewing a curated list of 1 dividend fortresses with similar income and capital return profiles.
Boyd Group Services Investment Narrative Recap
To own Boyd Group Services, you need to buy into a simple idea: scale and process work matter more than short term net earnings. The recent quarter showed more than $1b in revenue and a hit to profit from acquisition and facility costs, which keeps the near term focus firmly on integration and execution rather than headline EPS.
For the next stretch, the key swing factor is whether new locations and Project 360 style efficiencies translate into cleaner margins while repair volumes hold up. The biggest risk remains cost pressure, from technician wages to equipment and IT, combining with insurer bargaining power to keep margins thin just as debt servicing needs attention.
The fresh normal course issuer bid to cancel up to 2,779,352 shares sits right beside those operating questions. It trims the share count ceiling while the business works through higher non operating and capital structure costs tied to acquisitions and facility growth.
For you, the relevance is less about signalling and more about capacity. Boyd Group Services still has to fund equipment, training and site expansion in a sector with rising repair complexity and tight labor. Execution on cost savings and integration remains the real near term catalyst, while any strain on interest coverage or industry accident volumes stays the key operational overhang.
What Boyd Group Services' Analyst Forecasts Are Pricing In
Boyd Group Services' narrative projects $4.9b revenue and $258.2 million earnings by 2029. That path builds on analysts' assumption of 10.7% yearly revenue growth and implies an earnings increase of about $249.2 million from $9.0 million today.
Uncover how Boyd Group Services' fair value points to a 96% potential upside to its current price, a discount that could close sooner than many investors anticipate.
Exploring Other Perspectives
One alternate angle focuses on Boyd Group Services’ cost program as the real swing factor. The most optimistic analysts were sketching in $5.3b of revenue and $349.5 million of earnings by 2029, well above consensus. That outlook may now be reassessed, as the new dividend and buyback reshape how you view cash use and future flexibility.
Explore another Boyd Group Services fair value estimate, including one that suggests potential upside of up to 206% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Boyd Group Services research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Boyd Group Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boyd Group Services' overall financial health at a glance.
Looking for more investment ideas beyond Boyd Group Services?
Once you have a view on Boyd Group Services, it helps to widen the lens and compare it with other opportunities that fit different goals for income, value, and risk.
- If you care about stability first, focus on businesses with resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (7 results) that can help anchor your portfolio.
- For investors hunting for value, use the screener to surface 5 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Income focused investors can round out their watchlist by reviewing a targeted 1 dividend fortresses that pairs higher yields with business profiles you can analyze in more detail.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com