
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DoorDash (DASH) Settlement Puts Its Undervalued Narrative To The Test
DoorDash (DASH) is in focus after agreeing to a US$131.5 million settlement with New York City over alleged delivery worker underpayments, a move that coincided with a roughly 3% slide in the stock.
The DoorDash share price has been under pressure recently, with a 1-month share price return down 18.4% and the year-to-date share price return down 12%. However, the 3-year total shareholder return is up about 143%, which signals longer-term momentum that contrasts with the recent pullback around the settlement and a run of product, partnership and expansion announcements.
Scan how DoorDash compares to other delivery and platform businesses by reviewing a curated set of 16 high quality undiscovered gems that may be flying under most investors' radar.DoorDash now trades well below its recent peak after the settlement-driven pullback, yet still has a 3-year total return above 140%. Does that mix of drawdown and past gains still tilt the risk reward toward buyers?
Most Popular Narrative: 24% Undervalued
On the Simply Wall St narrative, DoorDash screens as undervalued, with a fair value of about $254 against the last close at $193.36, which frames the recent settlement pullback against a much higher long term earnings and cash flow story.
Rapid expansion into new verticals (grocery, retail, convenience, pharmacy) and international markets is yielding faster growth rates and improving unit economics, which should diversify and accelerate topline revenue while supporting net margin expansion.
Strategic investments in AI and automation, such as enhanced search, personalization, logistics optimization, and autonomous or robotic delivery, are expected to lower fulfillment costs per order over time, driving sustained improvements in operating leverage and net margins.
See why 75 investors see DoorDash as 24% undervalued.
Result: Fair Value of $254 (UNDERVALUED)
Still, DoorDash faces real pressure from higher labor and regulatory costs around gig work, as well as execution risk as it expands into more countries and categories.
Find out about the key risks to this DoorDash narrative.
Another View: DoorDash Through The P/E Lens
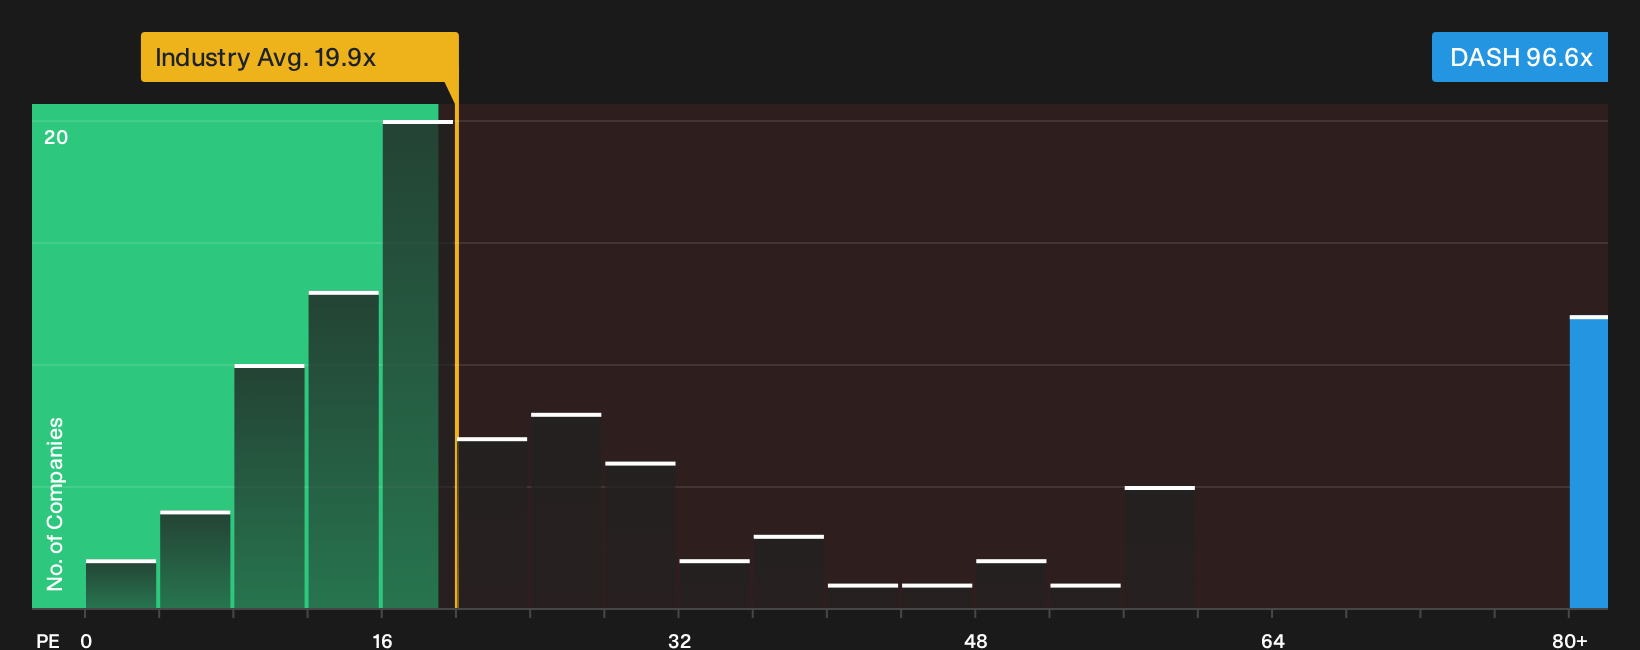
The earlier Simply Wall St fair value of $254 leans on long term earnings and cash flow assumptions for DoorDash. A simple market multiple check tells a different story. The stock trades on a P/E of 99.6x, while the US Hospitality industry sits at 19.9x and the fair ratio is 45.9x. That gap suggests investors today are paying a very full price for each dollar of current earnings. It is therefore worth considering how comfortable you are with that premium if growth or margins come in below expectations.
See what the numbers say about this price in our valuation breakdown, and how they compare to peers and the fair ratio, by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
DoorDash clearly splits opinion, with a rich P/E on one side and that discounted fair value on the other, so move fast and weigh the trade off yourself by drilling into the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond DoorDash?
Do not stop your research with DoorDash. Broaden your watchlist with focused stock ideas that match how you like to balance return potential and risk.
- Target potential underpriced opportunities by reviewing a curated 31 high quality undervalued stocks that couples quality fundamentals with attractive valuations.
- Strengthen the income side of your portfolio by examining a set of 8 dividend fortresses built around higher yields and dependable payouts.
- Dial back volatility risk by scanning a hand picked 29 resilient stocks with low risk scores designed for investors who value resilience alongside returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com