
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Cheniere Energy (LNG) Still Undervalued After Corpus Christi Progress?
Cheniere Energy has delivered a powerful long term share price run, and that leaves investors asking whether the current valuation still lines up with the earnings behind the story.
- Over the past 5 years, Cheniere Energy has returned 197.3%, which puts real weight on the question of what level of earnings can justify today's price.
- New liquefaction capacity and BASF's Durasorb technology at the Corpus Christi facility can affect the timing and stability of future cash flows, which matters directly for how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Cheniere Energy worth weighing. See what analysts think Cheniere Energy's shares could be worth.
The stock's next move may depend on whether the current share price fairly reflects Cheniere Energy's earnings power today and the profit stream investors expect it to produce.
If you are weighing Cheniere Energy against other opportunities tied to global energy demand, it can help to compare it with a wider set of 39 power grid technology and infrastructure stocks
Is Cheniere Energy a Bargain on Earnings?
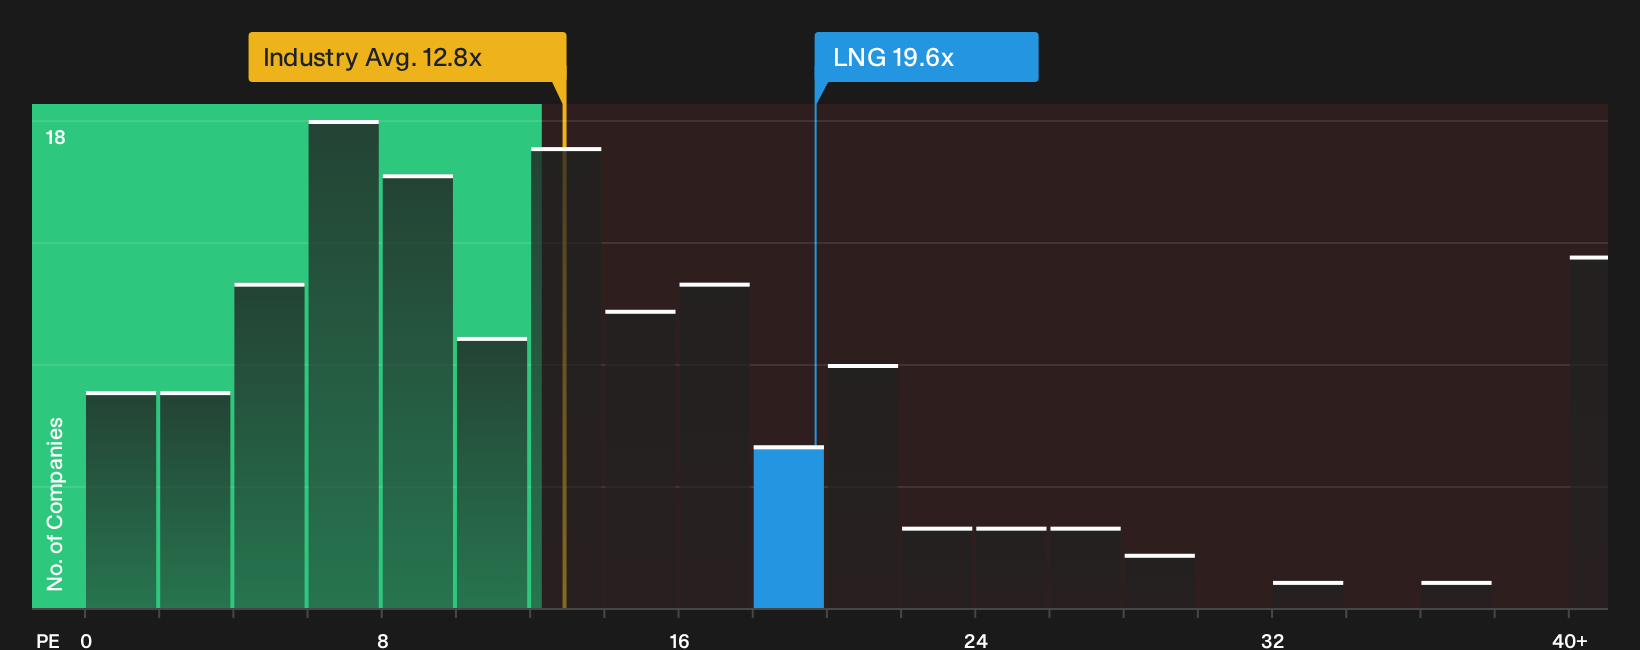
The P/E ratio is a useful starting point for Cheniere Energy because earnings are now a key focus for how investors frame this liquefied natural gas exporter. Cheniere trades on about 19.6x earnings, slightly above the peer group at 18.4x and well above the broader Oil and Gas industry on roughly 12.8x. That puts the LNG specialist on a richer earnings tag than many traditional producers, which often carry more commodity price exposure and different capital needs.
Because the current multiple sits below what a tailored fair P/E would suggest for Cheniere’s profile, the stock screens as undervalued on this framework. Recent commissioning of BASF’s Durasorb technology at the Corpus Christi facility is part of the picture investors are weighing, because reliability and uptime can influence how much confidence the market has in those earnings. Comparing this P/E to the modelled fair level can help you assess whether the current price reflects Cheniere Energy’s specific mix of LNG assets, contract structure and execution risks. Explore the numbers behind Cheniere Energy's P/E valuation.
The Cheniere Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives continue where the valuation puzzle for Cheniere Energy leaves off by explaining what kind of future earnings, growth and margin profile would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today on the current P/E. Rather than relying on a single multiple or model output, each Narrative sets out the assumptions behind its view of fair value so you can compare them with actual results as they are reported on Cheniere Energy's Community page.
One of the top community narratives on Cheniere Energy: 14% undervalued
"Think of it as a toll road. Cheniere gets paid a fixed fee per unit of LNG processed regardless of commodity prices…"
Discover why this Narrative puts Cheniere Energy at 14% undervalued.
One more thing to check on Cheniere Energy before you act
Before you lean too heavily on the P/E and earnings profile, it is worth knowing that Simply Wall St's broader checks have flagged specific concerns that could matter for Cheniere Energy's risk picture. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com