
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Canon And 2 Other Japanese Undervalued Stocks To Watch
Japanese government bond yields recently reached a 30 year high as part of a global bond selloff, which has pushed up discount rates and pressured many share prices. That kind of backdrop can leave solid Japanese companies with healthy cash generation trading below their estimated fair value. This article breaks down three cash flow focused Japanese stocks from our valuation screen that currently appear mispriced based on their future cash potential.
The three stocks highlighted below are only a small sample. The full cash flow screen surfaces 37 more Japanese companies that share similarly compelling valuation stories but are not covered here.
If you want to identify and analyze those additional ideas for yourself, head straight into the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Overview: Canon develops and sells printing systems, document solutions, cameras, medical imaging gear, and industrial equipment that together generate global equipment and service revenue.
Market Cap: ¥3.92t
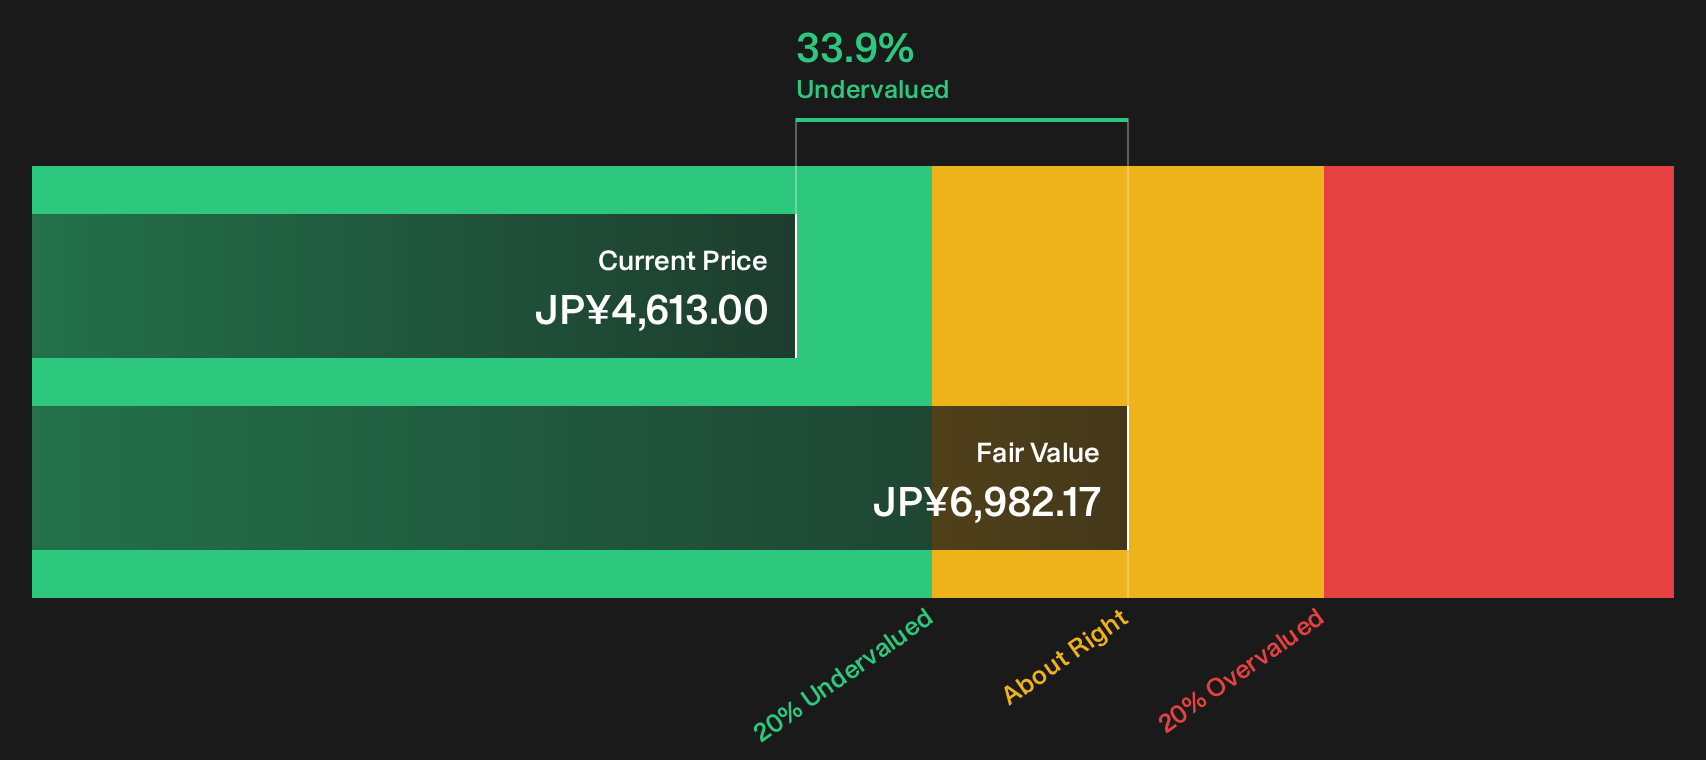
Canon sits in this cash flow screen because its Printing Business Unit, especially office multifunction devices and document solutions, generates recurring income from hardware, consumables, and service contracts. The stock trades about 33.9% below an internal fair value estimate and on an 11.3x P/E, so the appeal for value-focused investors now depends on how one unseen pressure shapes future margins.
That margin wildcard is exactly what sits behind the DCF valuation analysis for Canon, where the cash flow math shows how small shifts in profitability could reshape Canon’s valuation story.
Terumo (TSE:4543)
Overview: Terumo is a global medical technology group that supplies devices like prefilled syringes, contract manufacturing services, and cardiovascular instruments that feed recurring cash flow from hospitals and drug companies.
Operations: Terumo generates about ¥706.7b from Cardiac and Vascular, ¥240.2b from Blood and Cell Technologies, and ¥222.3b from Medical Care Solutions, with Japan and Europe as key reported regions.
Market Cap: ¥3.39t
Terumo matters for this cash flow focused screen because its syringe contracts and high volume cardiovascular tools keep hospitals and pharma clients coming back, which is the kind of repeat business that can turn stable demand into long term cash generation.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects and positioning the company for future revenue growth in this key emerging market."
The key variable for Terumo is how a shift in pricing power across its everyday consumables could affect future cash conversion.
That pricing shift is exactly what sits inside the full narrative for Terumo, which explains in detail how Terumo’s contracts, capital needs, and risk trade offs could reshape its cash story.

PAL GROUP Holdings (TSE:2726)
Overview: PAL GROUP Holdings manufactures and sells clothing brands and private label apparel in Japan, alongside a smaller general merchandise retail business.
Operations: PAL GROUP Holdings generates about ¥146.9b from Clothing Business and ¥90.1b from Miscellaneous Goods Business, almost entirely in Japan at ¥237.3b.
Market Cap: ¥254.0b
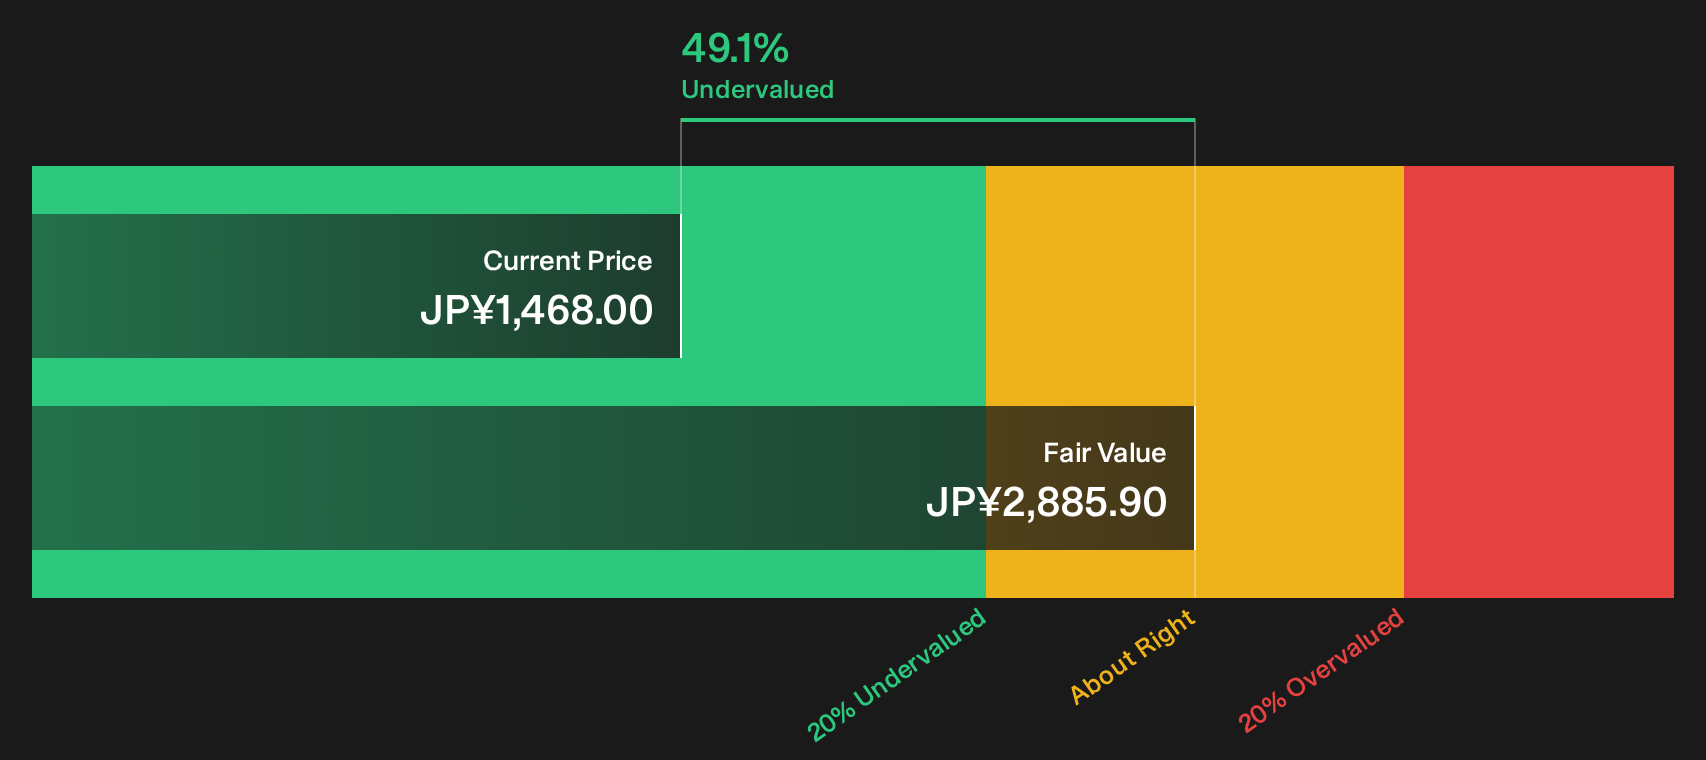
PAL GROUP Holdings anchors this cash flow focused screen through its apparel business, where clothing and private label lines drive the DCF valuation. However, the share price trades around 49% below that fair value estimate and continues to lag sector peers. The key issue now is how one pressure point may influence the durability of those apparel driven cash flows.
That cash question is exactly what the DCF valuation analysis for PAL GROUP Holdings unpacks, showing where PAL GROUP Holdings’ apparel cash flows could be mispricing the next leg of the story.
Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move first. Breakout moves, early momentum and quietly flying under the radar are usually caught before the crowd, while it matters. Scan the next wave and act now.
- Spot high yielders before the income chase heats up by scanning the 14 dividend fortresses built to surface payouts that still look sustainable and resilient.
- Track the companies quietly wiring the future of electricity with the 39 power grid technology and infrastructure stocks and see which operators could benefit if grid spending accelerates.
- Zero in on financially solid operators using the list of solid balance sheet and fundamentals (22 results) so you focus on businesses with the strength to handle surprises without scrambling.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com