
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Firefly Aerospace (FLY) Expands Cleanroom Footprint After Undervalued Narrative Gains Attention
Firefly Aerospace (FLY) just cut the ribbon on a new ISO Class 8 cleanroom in Texas, quadrupling its existing footprint and aiming to support up to 12 lunar and orbital vehicles in parallel.
That new cleanroom arrives at a tense moment for Firefly Aerospace shares, with the stock up 5.43% on a 1-day share price return and 6.31% over 7 days, yet still down 9.59% on a 90-day share price return and 38.69% on a 1-year total shareholder return. This suggests that recent momentum is starting to rebuild even as investors remain cautious after a tough year.
Scan other space and defense plays showing similar manufacturing momentum with the 30 resilient stocks with low risk scores that filters for resilience alongside potential upside.
Firefly Aerospace is trying to prove this cleanroom buildout reflects a sturdier business, not just a mood swing in the chart. Are investors finally paying for fundamentals, or just chasing a short bounce into valuation talk?
Most Popular Narrative: 40% Undervalued
Firefly Aerospace last closed at $23.09, while the most followed narrative anchors its fair value at $38.60. This frames the cleanroom expansion against expectations for much stronger future cash generation.
A growing focus on national security space and missile defense, including the planned US$175b Golden Dome program, positions Firefly’s Alpha, Elytra and SciTec software to compete across launch, space interceptors and fire control, which can influence long term revenue visibility and backlog conversion.
See why 38 investors see Firefly Aerospace as 40% undervalued.
Result: Fair Value of $38.60 (UNDERVALUED)
Still, Firefly Aerospace carries real execution risk, with continued GAAP net losses and recent Alpha launch issues that could pressure contracts and delay revenue recognition.
Find out about the key risks to this Firefly Aerospace narrative.
Another View: Firefly Aerospace Through Sales Multiples
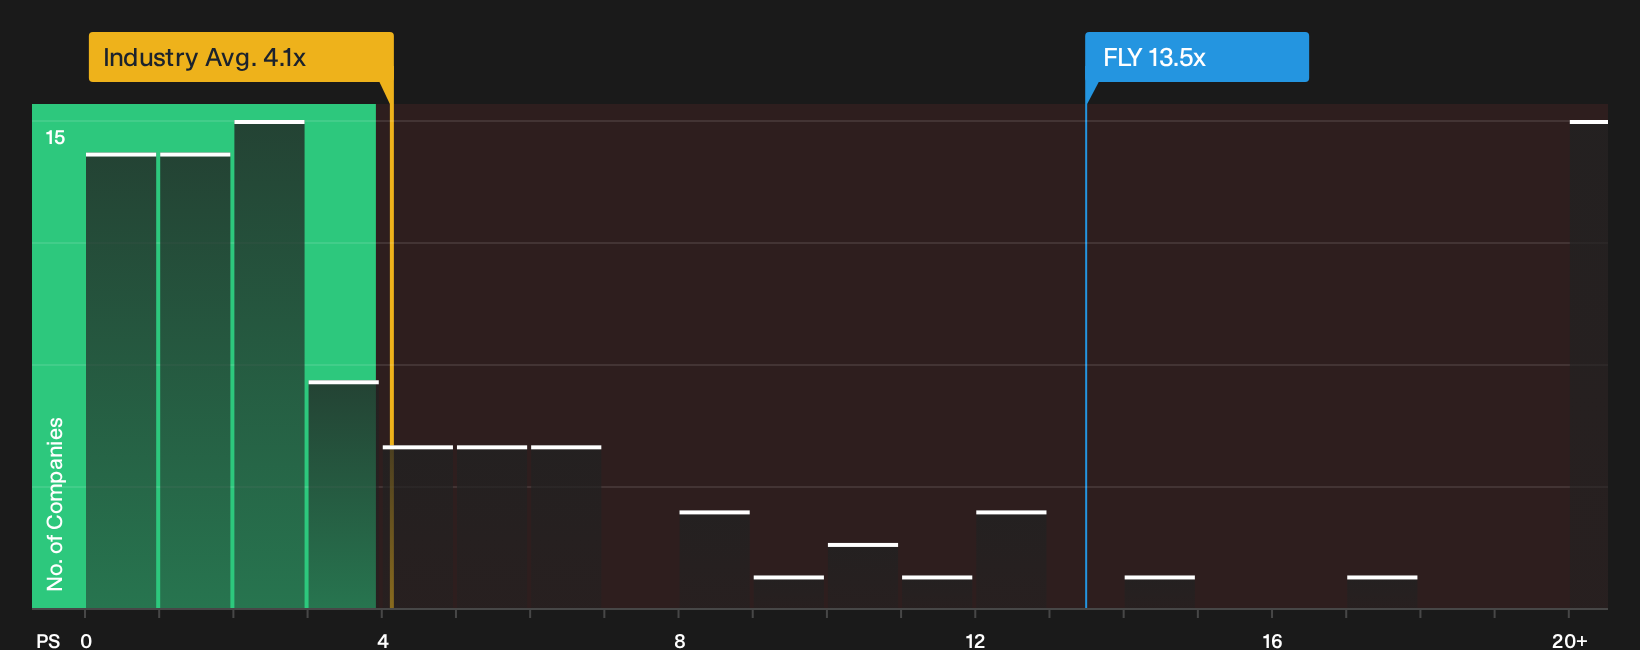
Firefly Aerospace screens as deeply undervalued on headline fair value numbers, yet the P/S ratio tells a very different story. The stock trades at 13.5x sales, while the US Aerospace & Defense group sits near 4.1x and the fair ratio points closer to 6x.
That gap suggests investors are already paying a heavy premium relative to sector peers, even if some models argue the shares are cheap against future cash flows. For a business still reporting large losses and forecast to remain unprofitable, how comfortable are you with a revenue multiple this far above where the market could move toward?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Firefly Aerospace so far. If you want to move quickly and judge the balance for yourself, start by weighing the 3 key rewards and 2 important warning signs.
Looking For More Firefly Aerospace Style Ideas?
If Firefly Aerospace has your attention, do not stop with a single ticker. Broaden your watchlist with a few focused sets of stocks that share clear, data backed traits.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) which is built to surface companies with staying power.
- Hunt for mispriced opportunities by working through the 30 high quality undervalued stocks that highlights stocks trading below their assessed quality and fundamentals.
- Lock in income focused ideas by reviewing a curated 8 dividend fortresses that concentrates on higher yield payouts supported by underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com