
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
US Foods (USFD) Stock Looks About Right At Today’s Price
US Foods Holding has delivered very strong gains over the past several years, which puts fresh attention on what investors are paying for its earnings today. After that kind of run, the key issue is whether the current valuation still lines up with what the business is generating in profit.
- Over the past 5 years the stock has returned about 171%, which makes the current price level an important reference point for how much of US Foods Holding’s earnings story is already reflected in the share quote.
- The group’s model as a large foodservice distributor means profitability, cash conversion and day to day execution on costs can shape how much earnings support investors may see behind the present market valuation.
- The analysts covering US Foods Holding have run their own numbers. See what analysts think US Foods Holding's shares could be worth.
The stock’s next move may depend on whether US Foods Holding’s recent share price can be explained by the earnings power that investors are currently paying for.
If you are weighing whether US Foods Holding still justifies its current P/E, it can help to compare it with a focused list of 30 high quality undervalued stocks as another starting point for deeper research.
Does US Foods Holding Look Fairly Valued on Earnings?
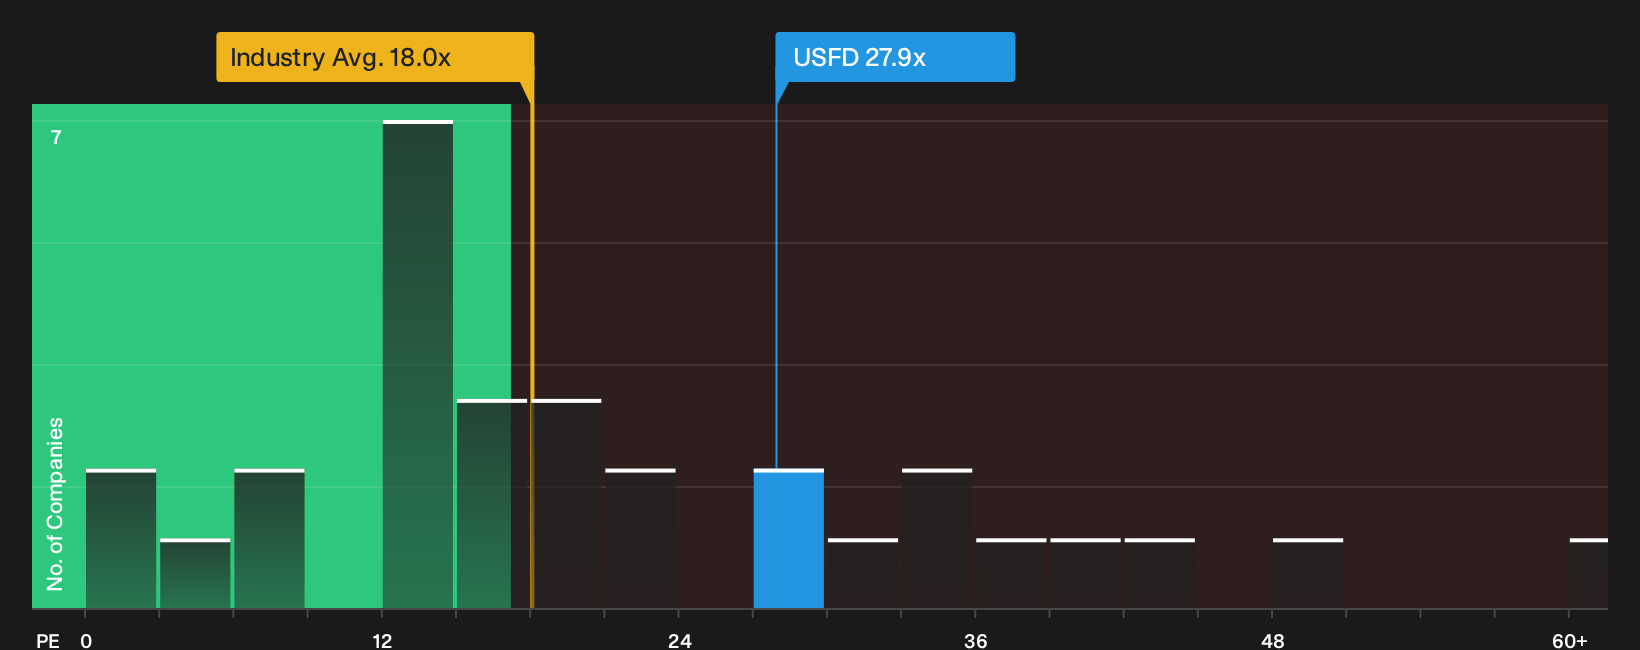
The P/E ratio works well for US Foods Holding because investors often anchor on earnings when judging a mature distributor with an established footprint. The stock currently trades at about 27.9x earnings, which is above the consumer retailing industry average of roughly 18.0x. That puts a clear earnings premium on the shares compared with the broader sector.
A more tailored yardstick, which factors in US Foods Holding’s own growth profile, profitability and risk, points to a P/E that is only slightly higher than where the shares change hands today. On that basis the current multiple sits close to what this framework would expect for the business, without pointing to the stock as obviously cheap or clearly expensive. Investors weighing this valuation may want to think about how resilient they believe the company’s earnings will be across a cycle, and how that compares with their other options in the sector. Explore the numbers behind US Foods Holding's P/E valuation.
The US Foods Holding Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle leaves off for US Foods Holding by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth much more or meaningfully less than it is today on the Community page. Each scenario links a fair value to a specific mix of potential catalysts and key risks, so you can track over time which version of US Foods Holding's story is actually unfolding.
Community views on US Foods Holding split between self help upside and concern that execution risk and higher costs could cap what the current valuation delivers.
Bull case: 19% undervalued
"US Foods' accelerated investment in digital platforms and supply chain automation, such as the MOXe platform and Descartes routing, has driven record operational efficiency..."
Discover why this Narrative puts US Foods Holding at 19% undervalued.
Bear case: 9% overvalued
"Rising fuel costs, only partially offset by surcharges that recover about 30% to 40% of fuel increases and subject to a timing lag, combined with a larger truck fleet to support Pronto and Pronto Next Day expansion, could keep distribution costs structurally higher..."
Explore why this Narrative puts US Foods Holding at 9% overvalued.
One more forward check for US Foods Holding
Price multiples tell you what is happening today, but the projections that analysts publish for US Foods Holding a few years out give you a different reference point to compare with the current market view. Explore where analysts expect US Foods Holding to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com