
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Is CAVA Group (CAVA) Back In The Spotlight?
CAVA Group (CAVA) drew fresh attention on September 18 after its board approved the company’s first share repurchase program, a US$100 million buyback funded with cash and operating cash flow.
CAVA Group’s buyback comes after a choppy stretch for the shares, with the 30-day share price return down 22.77% and the 90-day share price return down 35.84%. At the same time, the 3-year total shareholder return sits at 71.56%, and shorter-term momentum has picked up with a 4.49% 7-day gain. Investors are now weighing whether the new repurchase plan signals a reassessment of risk around the story.
Compare CAVA Group’s buyback story with other consumer-focused companies under pressure by scanning our hand picked 30 high quality undervalued stocks that are also pairing share price setbacks with solid fundamentals.
CAVA Group has a falling share price, a fresh US$100 million buyback and solid reported revenue and net income growth. Does that mix still leave the risk reward tilted toward buyers at today’s valuation?
Most Popular Narrative: 36% Undervalued
The most followed narrative pegs CAVA Group’s fair value at $83.72, well above the last close at $53.51. This frames the buyback against a valuation gap that some investors will want to stress test.
Rapid geographic expansion into new and underserved markets, supported by strong new unit performance and a robust target of at least 1,000 restaurants by 2032, is likely to accelerate systemwide sales and drive higher topline revenue growth.
Growing consumer demand among younger demographics for healthy, flavorful, and customizable dining, especially Mediterranean cuisine, positions CAVA to benefit from increased customer traffic and enhanced brand equity, supporting both revenue and long-term pricing power.
See why 73 investors see CAVA Group as 36% undervalued.
Result: Fair Value of $83.72 (UNDERVALUED)
Still, CAVA Group’s heavy focus on Mediterranean fare and an ambitious push to at least 1,000 restaurants could invite saturation, higher costs, and thinner returns if demand disappoints.
Find out about the key risks to this CAVA Group narrative.
Another View: CAVA Group Looks Expensive On Earnings
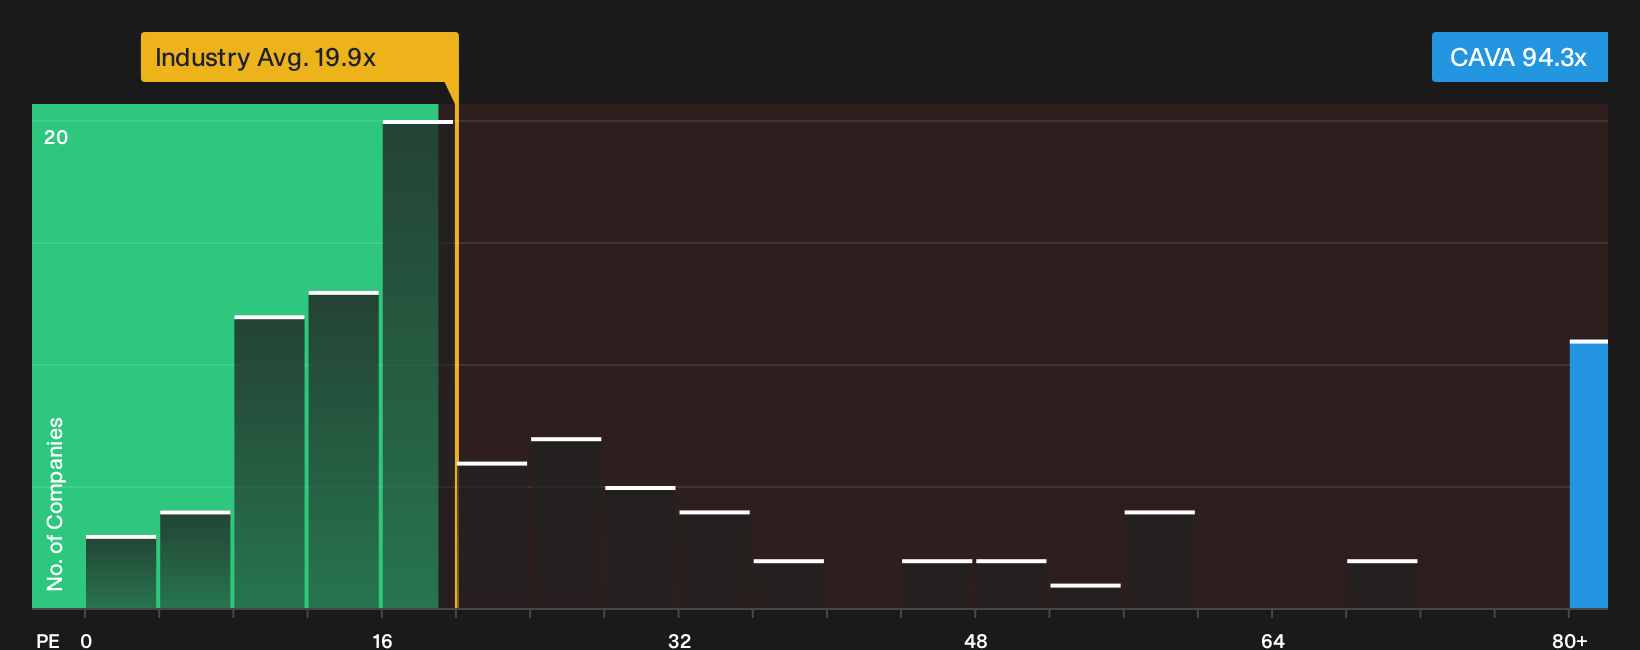
The 36% undervalued fair value narrative leads to a very different conclusion when you look at CAVA Group through its P/E ratio. The shares trade at about 94.3x earnings, compared with a peer average of 30.9x and a US Hospitality industry average of 19.9x.
The fair ratio for CAVA Group is estimated at 28.3x. This is roughly where the multiple could trend over time if sentiment cools. That gap points to meaningful valuation risk if growth or margins fall short of expectations, so the question for investors is how much optimism they are really willing to pay for today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on CAVA Group’s valuation and sentiment make this a stock where your own work matters. Move quickly, review the key upside and downside factors, and then weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond CAVA Group?
If CAVA Group’s buyback story has you thinking harder about price, quality and risk, broaden your search and stress test your ideas against other opportunities.
- Target potential mispricings by scanning a focused set of quality companies using the 30 high quality undervalued stocks.
- Prioritize resilience and capital strength by reviewing a list of solid balance sheet and fundamentals (24 results) to see which businesses hold up under pressure.
- Hunt for under-the-radar opportunities before they become crowded by running through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com