
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks for Higher Rates and Data Center Demand
AI infrastructure is pulling huge amounts of capital into chips, data centers, and energy just as Bill Ackman questions whether higher interest rates still cool inflation in a post‑ChatGPT world. If borrowing costs stay elevated yet investment in compute keeps flowing, some stocks exposed to this debate could look mispriced. This article examines the current setup and discusses 3 AI infrastructure stocks that appear positively exposed to this news shock.
The three stocks below are just a sample from this theme. The full screen surfaced 39 more AI infrastructure companies with equally detailed stories that are not covered here. To go straight to the source and identify your own highest conviction ideas, analyze the full AI stack using the AI Infrastructure (Semiconductors, Data Centers, and Energy Providers) screener.
FormFactor (FORM)
FormFactor plugs into the AI infrastructure theme as a behind the scenes supplier, providing test gear that helps high end chips for data centers and advanced computing get out of the fab and into servers.
FormFactor generates most of its roughly US$900 million in sales from Probe Cards at about US$747 million, with Systems contributing about US$155 million, and the business carries a market value of roughly US$10.1b.
"Accelerating adoption of generative AI, high-performance computing, and HBM DRAM in data centers is driving substantial increases in test complexity and intensity. FormFactor's differentiated probe cards and early leadership in HBM4 chiplet testing position the company to benefit from higher ASPs and revenue growth as these markets scale."
What happens to FormFactor’s earnings power if a single pressure point around product mix and test intensity moves in its favor.
That hinge point on earnings power is exactly what sits at the center of the full narrative for FormFactor, which maps how AI test intensity could reshape FormFactor’s upside profile.

AP Memory Technology (TWSE:6531)
AP Memory Technology designs custom memory ICs used in AI accelerators, GPUs, and high performance computing gear, tying it directly into AI infrastructure. The business generated about NT$7.8b from semiconductors and carries a market value near NT$162b.
AP Memory Technology is connected to the AI infrastructure theme through tailored memory chips for accelerators and data center compute, supported by recent earnings momentum and high margins. Investors tracking AI hardware capacity may pay close attention to how any shift in currently unseen pressures on pricing and demand could affect the business environment.
Those hidden pressures make it worth seeing the 3 key rewards and 1 important major warning sign before sentiment around AP Memory Technology and AI demand shifts again.

Ingenic Semiconductor (SZSE:300223)
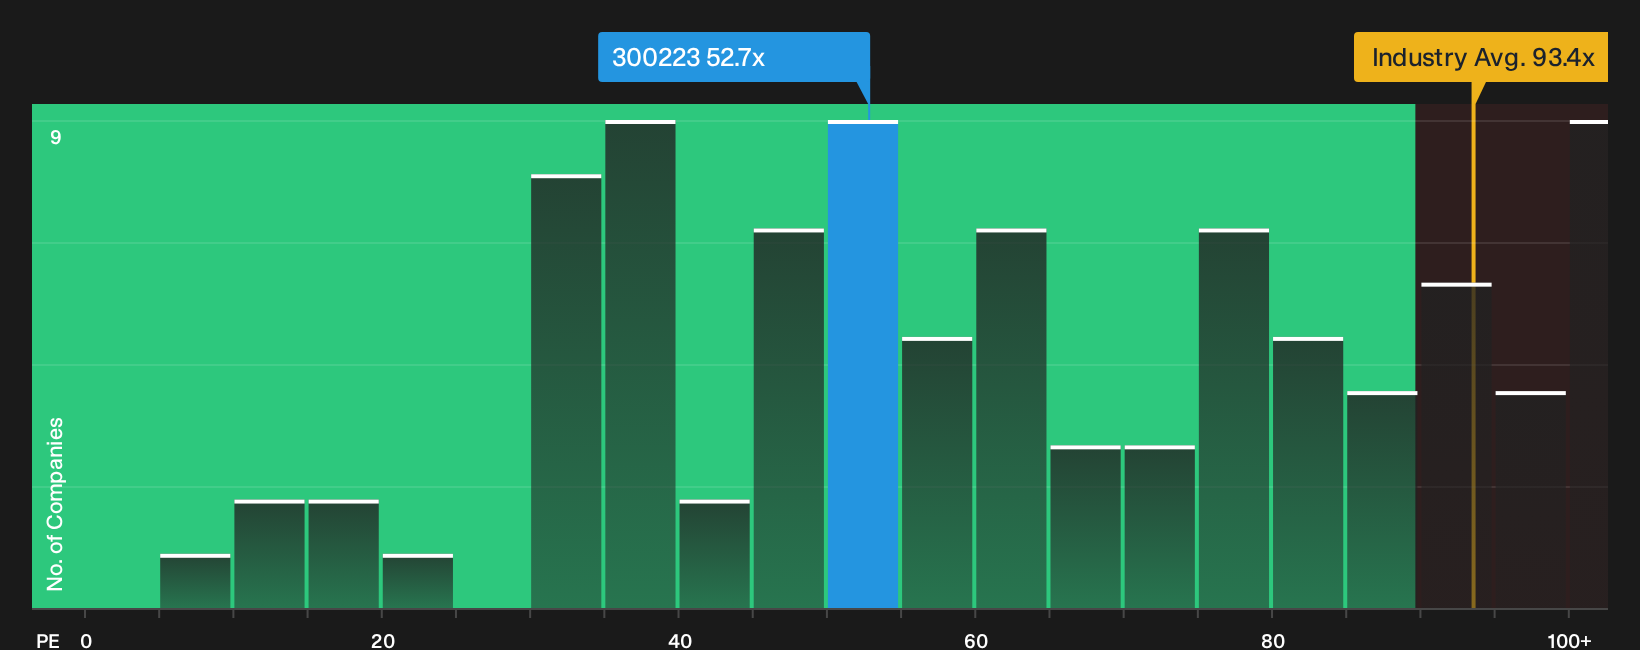
Ingenic Semiconductor designs system on a chip processors and video chips that sit inside AI capable devices. This ties it neatly into the AI infrastructure theme on the compute side, and the stock carries a market value of about CN¥70.5b.
Ingenic Semiconductor provides direct exposure to AI capable chips at the device level, supported by a CN¥70.5b market cap and a P/E below the broader semiconductor peer group. A key variable for investors is how one currently unseen pressure on AI driven chip demand ultimately resolves.
That unresolved demand question makes it worth reviewing the 4 key rewards and 1 important major warning sign to see how Ingenic Semiconductor’s risk profile and upside case could be shifting.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. By the time momentum hits the headlines, the cleanest entry points can be gone. Scan curated AI and infrastructure plays that are under the radar for now and consider acting before they become widely followed.
- Look for early breakout potential in capital efficient businesses by scanning the 30 high quality undervalued stocks while prices and expectations still appear out of sync.
- Track rising momentum in real world automation by checking the curated 93 robotics and automation stocks before more industrial adoption stories are reflected in valuations.
- Identify cash generating companies with durable balance sheets by working through the hand picked list of solid balance sheet and fundamentals (24 results) while it remains less visible in many screens.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com