
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Peugeot Invest (ENXTPA:PEUG) Stock Trails Revenue Drop Despite Stronger Profit
Peugeot Invest Société anonyme came into this earnings release with a low 5.5x P/E and a share price that has drifted over the past three months, even though the stock is roughly flat over the last week. The headline from H1 2026 is simple: profit power is doing the heavy lifting. Net income of €135.8m sits against revenue of €148.9m, which keeps trailing net margin very high and reinforces the valuation gap to peers that trade on roughly double the earnings multiple.
Love Peugeot Invest Société anonyme's high net margin but worried that a low 5.5x P/E could signal a value trap rather than a bargain? Compare this setup with our curated list of 180 high quality undervalued stocks
H1 2026 Earnings Summary
- Revenue (H1 2026 vs. H1 2025): €148.9m vs. €250.7m (meaningful decline in top line)
- Net Income (Excl. Extra Items, H1 2026 vs. H1 2025): €135.8m vs. €121.5m (profit higher despite lower revenue)
- Basic EPS (H1 2026 vs. H1 2025): €5.45 vs. €4.90 (earnings per share improved)
- Trailing Net Margin (TTM vs. prior year): 91.3% vs. 23% (very large margin expansion on a trailing basis)
If you prefer clear visuals to dense earnings tables and extensive footnotes, explore Peugeot Invest Société anonyme's full financial picture, including how the current valuation compares with recent profit levels, in our company report for Peugeot Invest Société anonyme.
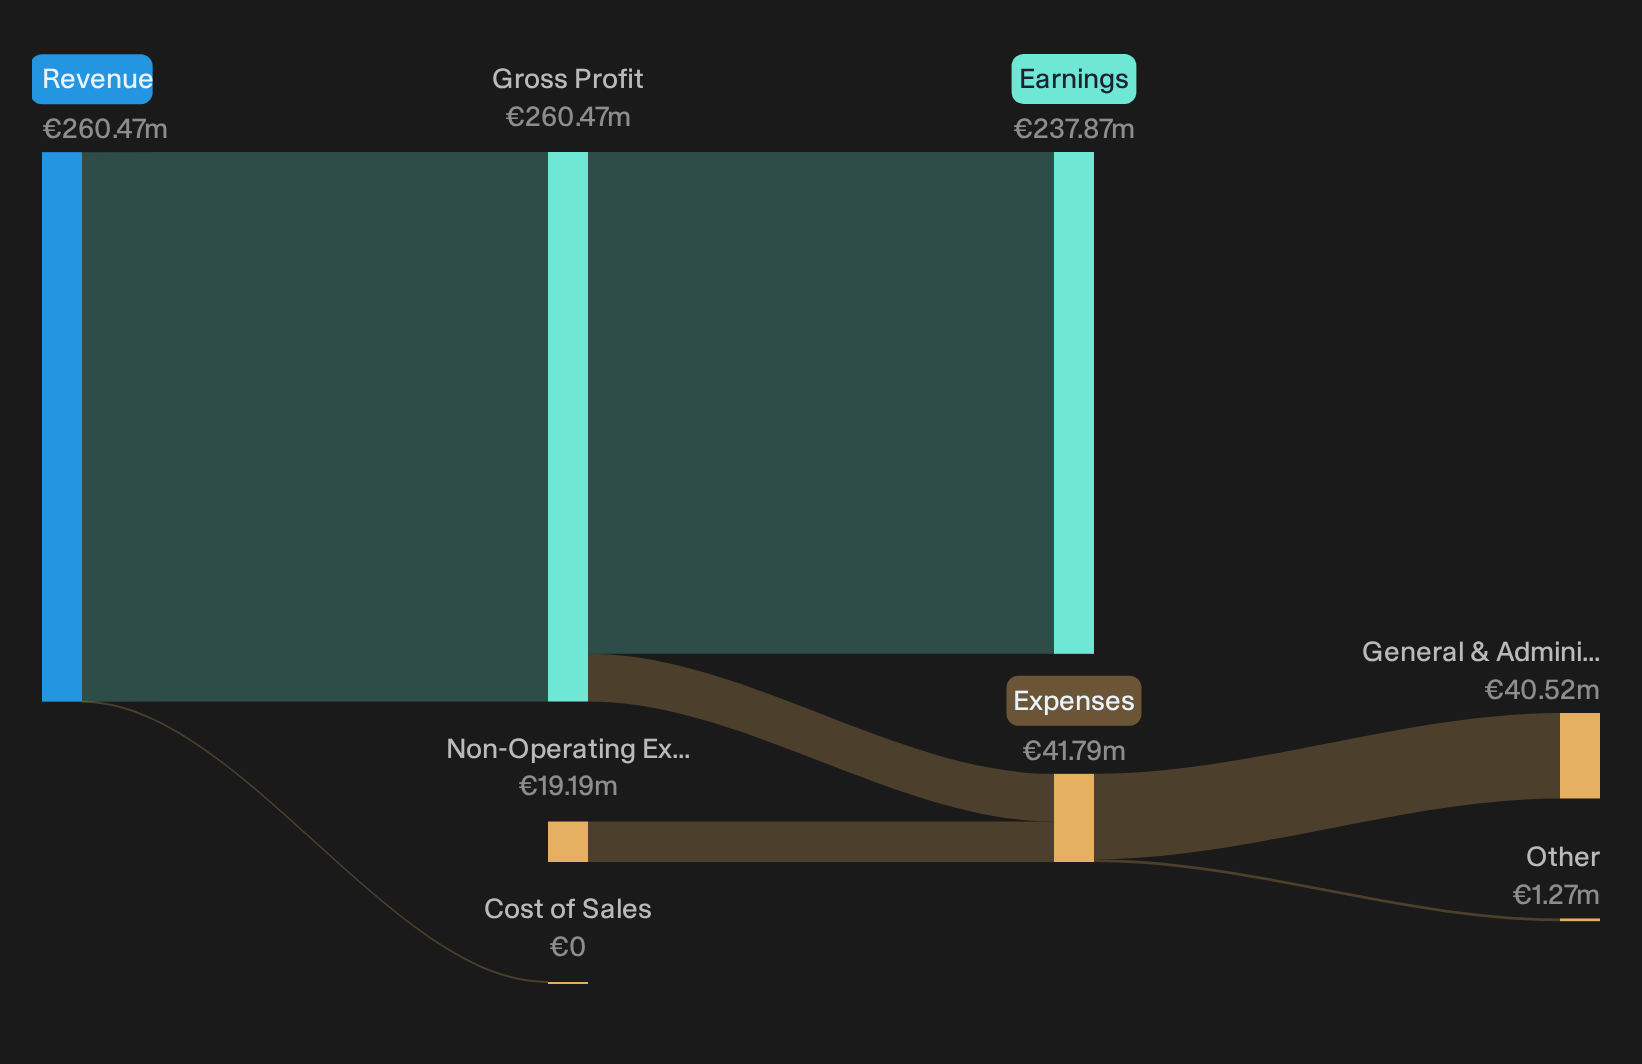
Profit Power And Peugeot Invest’s Upside Story
For a bullish angle on Peugeot Invest Société anonyme, the earnings mix matters more than the revenue line. H1 2026 revenue is well below H1 2025, yet net income excluding extra items is higher and basic EPS has improved. Very high trailing net margin above 90% points to a model where investment gains and efficient cost control drive results. That pattern fits a narrative of a conservative holding company that can convert a relatively modest top line into substantial profits when underlying assets perform.
Where The Cautious View Still Has Teeth
The bear case leans on two pressure points. First, the sharp drop in H1 2026 revenue against H1 2025 reminds you that Peugeot Invest Société anonyme depends heavily on inherently volatile investment income. Second, the recent share performance, with the stock down over the past 30 and 90 days, hints that investors are not fully embracing the recent profit strength. That combination supports concerns about earnings quality and sustainability, even if the current net margin looks impressive on paper.
Compare Peugeot Invest Société anonyme's profit heavy story with what the street is signaling at €52.6 per share. See the consensus price target analysis for Peugeot Invest Société anonyme to check how current analyst targets line up with this mix of strong earnings and cautious market sentiment.Stay Ahead With Simply Wall St
If Peugeot Invest Société anonyme's high net margin and low 5.5x P/E have your attention, register for free with Simply Wall St and add it to your Watchlist to track the share price against fair value and watch for a more attractive entry point. After you decide to take a position, use the Portfolio Command Center to keep your holdings organised and surface only the most important updates instead of getting lost in daily headlines. For a longer term view, tap into the crowd insight inside our Community and see how other investors are thinking about the same risks and opportunities. That way you spot hidden catalysts and potential red flags sooner and keep your decisions a step ahead of the wider market.
Seeking Alternatives Beyond Peugeot Invest?
Fresh ideas can move fast, and early momentum often gets caught before it shows up in headlines. Scan under the radar for now, while it matters, and consider your options.
- Explore potential rebound opportunities in beaten down value names by scanning our curated pool of 227 resilient stocks with low risk scores that aim to keep downside pressure in check while sentiment is still fragile.
- Review the momentum of structural themes shaping future infrastructure by running through carefully filtered 39 power grid technology and infrastructure stocks that focus on businesses tied to critical upgrade and resilience spending.
- Assess possible upside in reshoring and electrification by reviewing a tight selection of 17 top copper producer stocks built around producers linked to long term metal demand and capital discipline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com