
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tower Semiconductor (TSEM) Joins A Major Chip Index, Is It Still Below Fair Value?
Tower Semiconductor (TSEM) has just been added to the PHLX Semiconductor Sector Index, is ramping high-volume silicon photonics shipments with NewPhotonics for AI-focused optical interconnects, and is preparing broader technology showcases at ECOC 2026.
Recent trading has been choppy for Tower Semiconductor, with the share price down 5.74% over the last day and 13.06% over three months, yet still up 78.48% on a year to date share price return and supported by a very large 1-year total shareholder return of about 3x. This suggests that the index inclusion and AI photonics announcements are being weighed against a reassessment of near term risk and expectations.
Scan for more Tower Semiconductor style plays in AI infrastructure and advanced connectivity by checking the hand picked 87 AI infrastructure stocks now shaping datacenter and photonics demand.
Index inclusion, AI photonics momentum and a very strong recent shareholder return all point to a solid Tower Semiconductor story. The harder question is whether the current US$217 share price reflects that strength or overreaches it.
Most Popular Narrative: 31% Undervalued
On the most followed view, Tower Semiconductor's fair value of about $314 per share sits well above the recent $217.28 close. This perspective puts a lot of weight on its silicon photonics story and future earnings power.
The rapid ramp-up in silicon photonics shipments, including expansion from transmit-only to both transmit and receive functions, higher bandwidth modules (up to 1.6T with 3.2T on the roadmap), and adoption by Tier 1 customers, positions Tower to further penetrate the growing optical transceiver market, supporting future revenue acceleration and increased average selling prices.
See why 31 investors see Tower Semiconductor as 31% undervalued.
This storyline uses a 14.27% discount rate and assumes Tower Semiconductor can grow revenue to roughly $4.1b and earnings to about $1.3b by 2029 while lifting profit margins from 16.9% to 32.9%. Analysts backing this framework also look for earnings to compound at 50.6% per year over the next three years and for the business to sustain a higher margin mix in silicon photonics, Silicon Germanium and other specialty processes.
Under those inputs, the gap between the narrative fair value of $314.36 and the last close suggests investors are being asked to weigh a high growth and high margin path against risks such as over $1.15b of committed CapEx through 2026, customer concentration in AI and optical transceivers, and a P/E of 84.8x that already runs above the US Semiconductor industry average. The result is a valuation story that leans heavily on continued execution in AI optics, expanding 300mm capacity and the ability to hold pricing power as more foundries target similar high value niches.
Result: Fair Value of $314.36 (UNDERVALUED)
Still, the Tower Semiconductor thesis hinges on heavy CapEx actually filling and on AI focused photonics demand not slowing or shifting to rival foundries.
Find out about the key risks to this Tower Semiconductor narrative.
Another View: Tower Semiconductor Through The P/E Lens
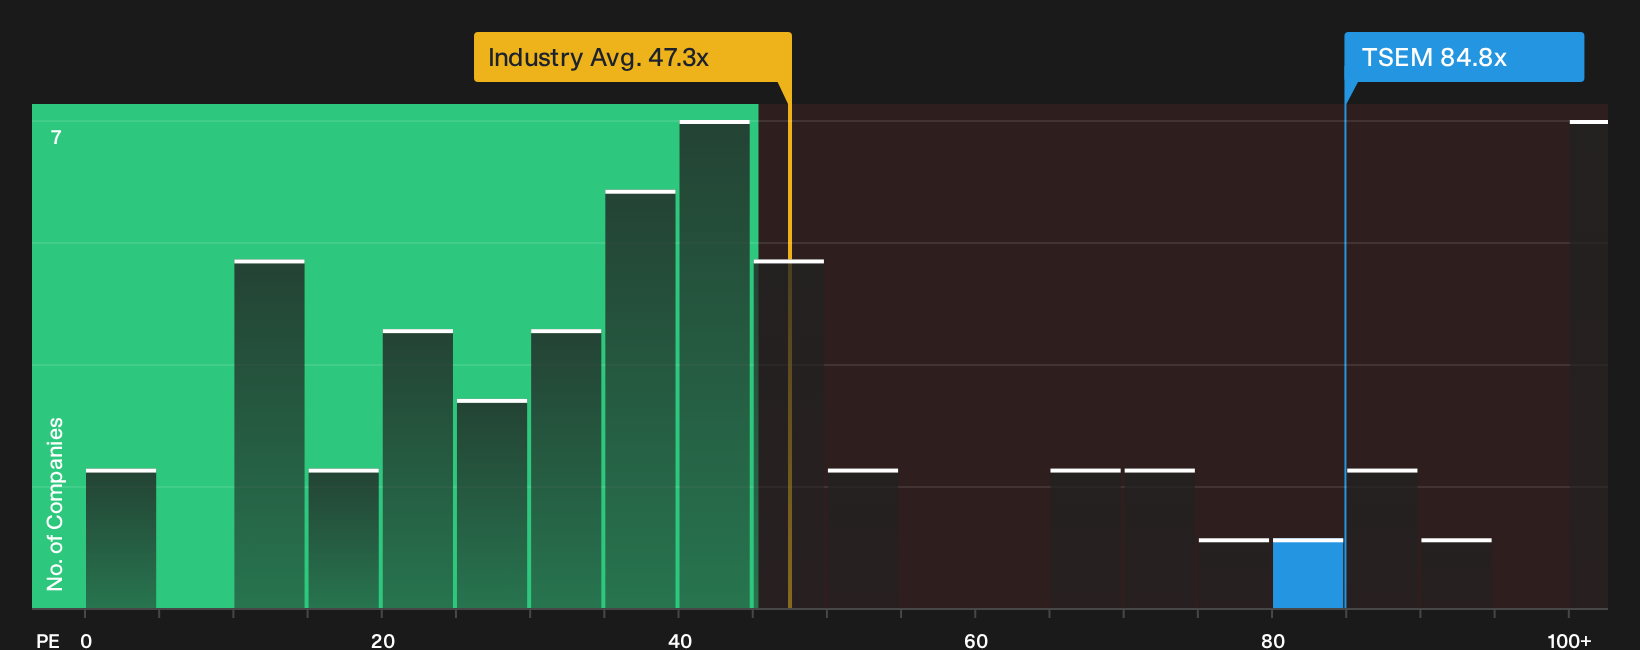
The bullish Tower Semiconductor story on future cash flows runs into a very different picture when you look at today’s earnings multiple. The stock trades on a P/E of 84.8x, compared with a fair ratio estimate of 53.1x, the US Semiconductor industry at 47.3x and peers at 49.4x.
That is a wide premium. It suggests investors are already paying up heavily for the silicon photonics and AI optics narrative, which raises the question of how much upside is really left if growth or margins land closer to the middle of the analyst range.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Tower Semiconductor after all that data. If you want to move quickly and judge the balance of concerns and potential yourself, take a close look at the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Tower Semiconductor?
If Tower Semiconductor has caught your attention, do not stop here. Broaden your watchlist with a few focused idea lists tailor made for different goals.
- Target steadier compounding by reviewing a 30 resilient stocks with low risk scores that keeps volatility in check while you focus on the long game.
- Hunt for quality at a discount by scanning a 30 high quality undervalued stocks that screens for strong fundamentals trading below intrinsic estimates.
- Build a sturdier core to your portfolio by checking a list of solid balance sheet and fundamentals (24 results) that filters for healthier leverage and liquidity profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com