
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asset Sale Might Change The Case For Investing In Plains All American Pipeline Stock (PAA)
- Plains All American Pipeline recently completed the sale of its Canadian NGL operations and is directing roughly US$3.3b of proceeds into U.S. crude oil infrastructure and related projects, consistent with its fee-based midstream focus.
- This shift concentrates Plains All American Pipeline more heavily in crude oil, which could sharpen its cost and throughput priorities while reducing diversification from NGL exposure.
- We will now see how Plains All American Pipeline's investment narrative could evolve as it recycles Canadian NGL sale proceeds into U.S. crude assets.
Scan other midstream income plays that are moving on fresh capital plans and throughput projects by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) alongside Plains All American Pipeline's latest repositioning move.
Plains All American Pipeline Investment Narrative Recap
For a unitholder in Plains All American Pipeline, the core belief is that a focused crude oil midstream portfolio can keep generating steady fee based cash flows while big capital programs are executed without stretching the balance sheet. The short term swing factor is still how well volumes and tariffs across key crude systems hold up as capital is recycled into U.S. assets.
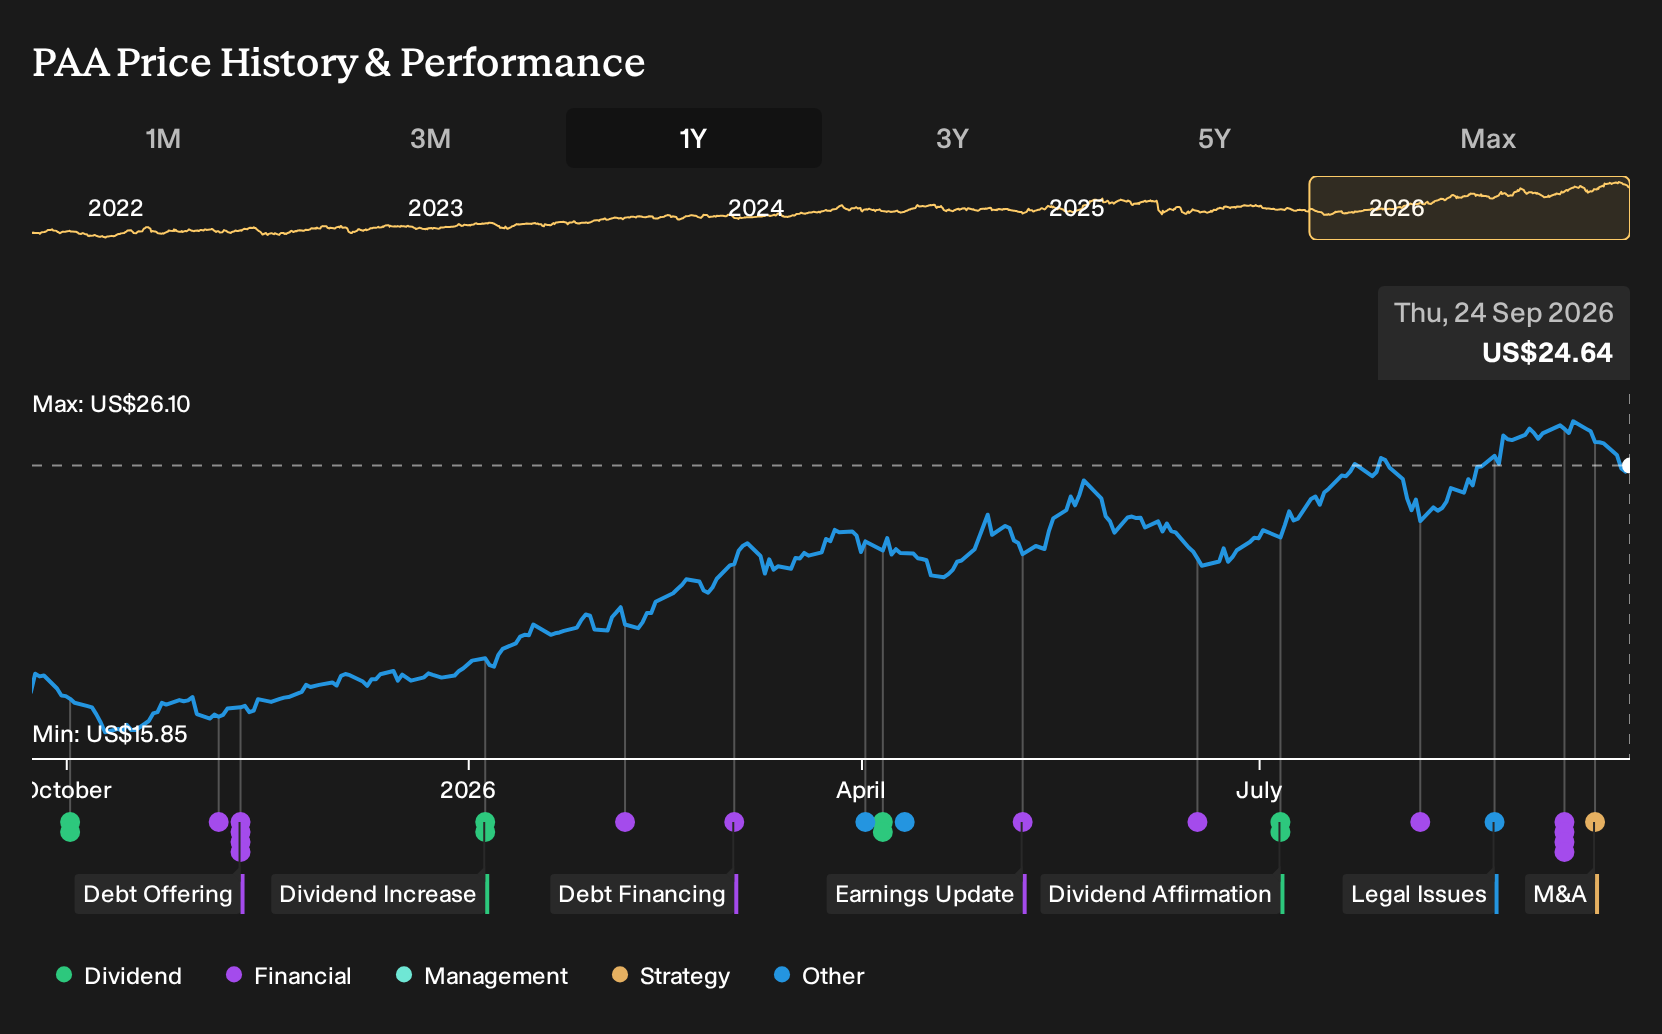
The main risk right now is that higher 2026 growth spending and the Cactus III and Powder River projects do not deliver the expected returns or are delayed, which would pressure free cash flow and limit room to manage debt or distributions. The recent pullback in the unit price does not materially change that execution question.
The clearest recent move that ties into this is the roughly US$3.3b redeployment plan following the sale of the Canadian NGL operations. Plains All American Pipeline is pushing harder into crude oil infrastructure and aiming for leverage around 3.3x, which tightens the link between crude throughput, earnings and financial flexibility.
That shift makes upcoming project delivery and the targeted US$100m of annual cost efficiencies even more central to the story. Investors now have a simpler set of levers to watch: crude volumes on assets like Cactus III, realized tariffs, capital discipline and debt metrics. Together, these factors will shape how durable current returns and future distribution capacity look.
Plains All American Pipeline's current analyst storyboard points to revenues of $63.8 billion and earnings of $1.6 billion by 2029. This projection is based on a 6.8% yearly revenue growth assumption and an earnings increase of about $779 million from the $821.0 million reported today.
Uncover why Plains All American Pipeline's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Plains All American Pipeline between US$26 and about US$74 per unit, which is a wide spread for just a pair of views. Those retail investors have not yet updated for the NGL sale or higher 2026 capital plan, so use them as starting points and seek out more viewpoints.
Explore another Plains All American Pipeline fair value estimate, including one that suggests as much as 202% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Plains All American Pipeline research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Plains All American Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plains All American Pipeline's overall financial health at a glance.
Looking For More Ideas Beyond Plains All American Pipeline?
If you want to round out your watchlist beyond Plains All American Pipeline, the Simply Wall St Screener can help you zero in on other opportunities that fit your risk tolerance and income goals.
- For investors who care most about balance sheet resilience and solid fundamentals, start with this hand picked list of solid balance sheet and fundamentals (24 results) that meet stricter financial quality checks.
- If value is your priority and you are searching for quality businesses trading below their estimated worth, take a look at 30 high quality undervalued stocks that pass both cash flow and balance sheet filters.
- Income focused readers who want payout strength paired with staying power can review 30 resilient stocks with low risk scores that screen for lower risk profiles alongside consistent performance markers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com