
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Earnings Beat Altering The Investment Case For Dropbox Stock (DBX)?
- Dropbox reported a recent quarter in which revenue, operating income, and billings all came in ahead of analyst expectations, bringing the company’s collaboration platform and subscription model back into focus for investors.
- The stronger quarter also highlighted how Dropbox’s P/E valuation still sits at a discount to many peers, which shifts attention toward execution around monetization, efficiency, and user engagement rather than just headline growth.
- This article explores how Dropbox's investment narrative is influenced by this earnings beat, particularly the outperformance in revenue and billings.
Scan how Dropbox’s earnings beat compares with other potential opportunities by running the same lens over a curated set of 30 high quality undervalued stocks that combine quality with compressed P/E multiples.
Dropbox Investment Narrative Recap
To own Dropbox, you need to believe the collaboration platform can offset pressure in its mature cloud storage base with better monetization, new tools, and disciplined cost control. The recent earnings beat on revenue, operating income, and billings supports that thesis in the near term, since it points to healthy demand for the core subscription business.
In the short term, the key catalyst is execution on AI driven products like Dash and better engagement that can lift ARPU without accelerating churn. The biggest risk is that user counts and annual recurring revenue keep slipping while pricing pressure from cheaper plans and large suite competitors weighs on margins, which this quarter alone does not resolve.
With no fresh product specific announcements tied directly to this earnings release, the most relevant context is Dropbox’s existing push into AI powered tools such as Dash and its focus on converting and retaining paying subscribers. The latest beat matters because it gives management more room to invest in those projects while still defending profitability.
For you as an investor, that leaves the story centered on whether Dropbox can use its large registered user base and integrations to support higher value tiers over time. The operational risk is clear. If new offerings like Dash fail to gain traction or if churn accelerates, then flat to declining revenue trends and high competitive pressure could remain the dominant narrative.
Dropbox Forecasts and What the Earnings Beat Really Implies
Analyst models around Dropbox are not built on rapid revenue expansion. Consensus assumes revenue stays fairly flat over the next three years while profit margins edge up from 17.5% today to 18.3% by 2029. That setup leans more on efficiency, buybacks and product mix than on raw top line growth.
On earnings, the group of forecasters expects profit to move from US$442.8 million today to US$458.3 million by 2029. That is an earnings increase of about US$15.5 million, which is modest in absolute terms and places more weight on how the collaboration platform manages costs, pricing tiers and AI products like Dash than on a surge in new users.
Valuation assumptions sit in the middle of this picture. To match the analyst price framework, Dropbox would need to trade at a P/E of 16.5x on those 2029 earnings, compared with 17.9x today and below the US software industry P/E of 29.5x. Forecasts also bake in a 7% yearly decline in share count over the next three years, which means per share metrics could look firmer than the relatively flat revenue profile suggests.
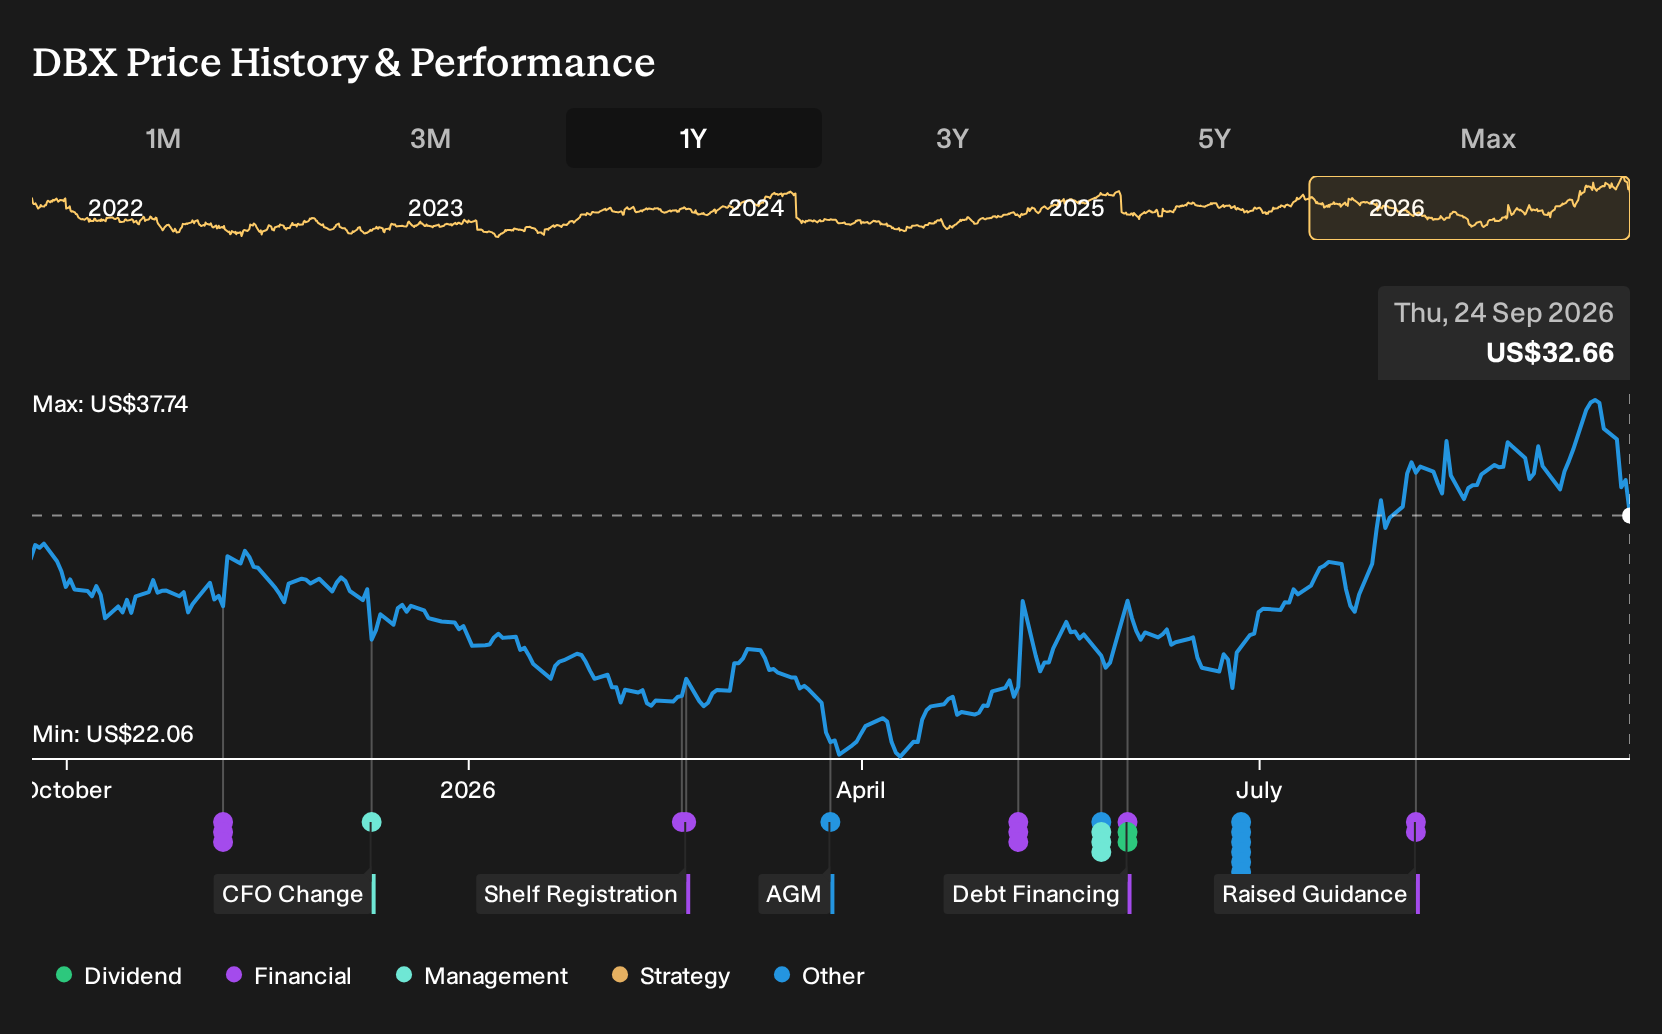
Consensus targets highlight that not every analyst reads the same story. The average price target sits at US$32.60, with the most optimistic at US$42.00 and the most cautious at US$23.00. With the share price quoted at US$36.48 against that US$32.60 midpoint, the analyst view implies the market already prices in more progress on margins, AI adoption and retention than the current earnings path alone might justify.
Dropbox's narrative projects US$2.5b revenue and US$458.3 million earnings by 2029. This requires fairly flat yearly revenue growth and an earnings increase of about US$15.5 million from US$442.8 million today.
Uncover why Dropbox's fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate angle on Dropbox focuses on AI as a much bigger catalyst than consensus assumes. Bullish analysts were already penciling in roughly US$2.5b of revenue and US$501.2 million of earnings by 2029, with margins reaching 20%. That is a far more optimistic story than the flat-growth baseline. This earnings beat might push some forecasts closer to that upper band, or it might prompt you to question whether those higher expectations still feel realistic.
Explore 2 other Dropbox fair value estimates, including one that suggests as much as 123% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dropbox research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dropbox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dropbox's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dropbox?
If this Dropbox earnings story has you rethinking what value looks like, it can help to line it up against other companies with different strengths. Use the Simply Wall St Screener to compare business quality, balance sheet resilience, and P/E compression across a broader watchlist.
- If you want potential upside without only chasing headlines, scan a curated set of 16 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- For investors who care most about capital protection and steadier profiles, focus on a 30 resilient stocks with low risk scores that filters for resilient businesses with lower risk scores.
- When balance sheet strength is non negotiable, build a shortlist using a list of solid balance sheet and fundamentals (24 results) so you can concentrate on companies with financial foundations that match your tolerance for volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com