
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Data Breach Could Be A Big Test For Astrana Health Stock (ASTH)
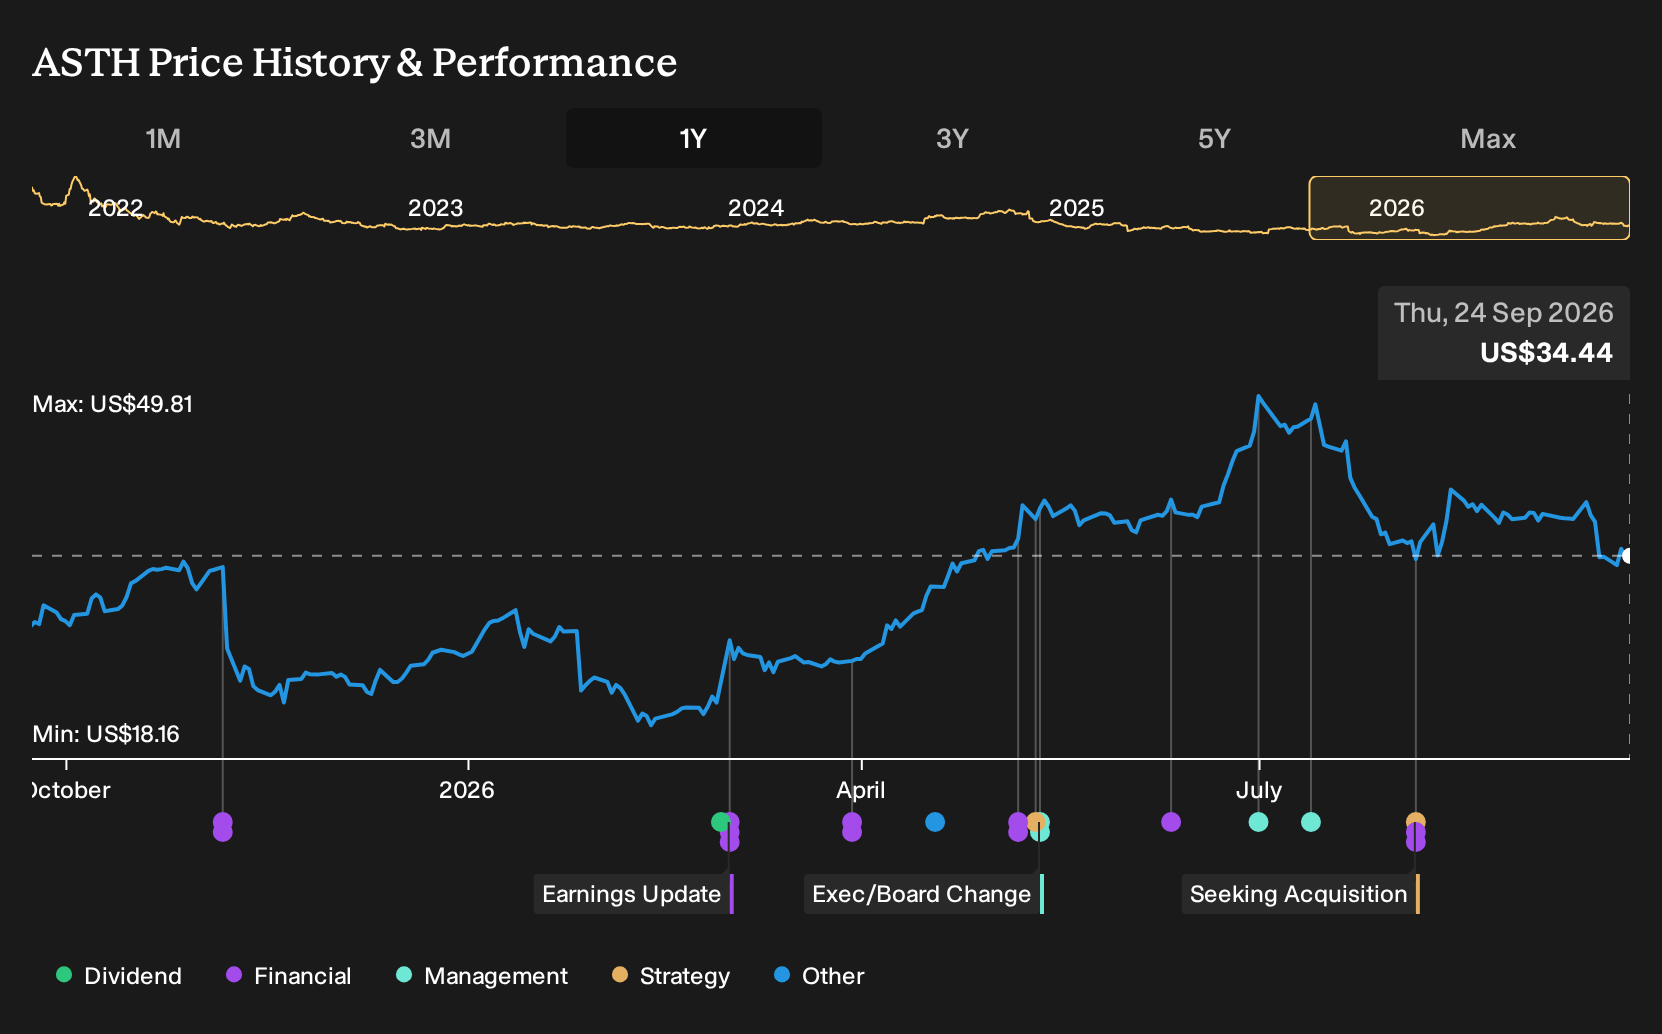
- Astrana Health recently reported a material cybersecurity incident and data breach at its Astrana Health Management subsidiary, adding a new operational risk related to data security and privacy controls.
- The disclosure highlights scrutiny of Astrana Health’s systems, compliance processes, and incident response capabilities in supporting a business that already faces significant regulatory and legal oversight.
- This raises questions about how Astrana Health's investment narrative could be affected by the material cybersecurity breach at its management subsidiary.
Stress test your exposure to Astrana Health style event risk by scanning a curated 30 resilient stocks with low risk scores designed to prioritize resilience when headlines turn hostile.
Astrana Health Investment Narrative Recap
For Astrana Health, the core belief is that a growing share of care can be managed under full risk, value based contracts while keeping medical costs in check. That story leans heavily on execution in Medicare and Medicaid, as well as integration of assets like Prospect Health. The cybersecurity incident introduces an additional operational burden but does not directly alter reimbursement or volume trends.
The more immediate swing factor appears to be how well Astrana Health handles regulatory complexity, including 2027 Medicare changes and ongoing scrutiny of its acquisition approach. The biggest risk now is stacked execution pressure, with cybersecurity, compliance, integration, and funding costs all pulling on management focus at the same time.
One of the most relevant threads tied to this breach is the existing securities law investigation into Astrana Health’s acquisition activity and related party loan. That inquiry has already placed a spotlight on internal controls, governance, and disclosure practices. A material data incident now brings those same systems into sharper focus for regulators and counterparties.
For potential catalysts, the key question is whether Astrana Health can keep growing earnings, which analysts forecast at 29% a year, while tightening risk management. Progress on integrating Prospect Health, capturing the US$12 million to US$15 million synergy target, and handling regulatory and cybersecurity oversight without large additional costs would be important signals for the resilience of that earnings profile.
Astrana Health's narrative projects US$4.8b revenue and US$144.6m earnings by 2029. This assumes 10.7% yearly revenue growth and requires about a 4.8x earnings increase from US$30.2m today.
Uncover why Astrana Health's fair value points to a 46% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
You now see how quickly the story around Astrana Health can shift. The most cautious analysts were already bracing for reimbursement and utilization risk, even while penciling in about US$5.0b revenue and US$118.1m earnings by 2029. That is a much cooler outlook than consensus, and the fresh cyber issue could push those views even further apart.
Explore 3 other Astrana Health fair value estimates, including one that suggests it could be worth just $50.12!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Astrana Health research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astrana Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astrana Health's overall financial health at a glance.
Looking For More Astrana Health Style Investment Ideas?
If the Astrana Health situation has you rethinking concentration risk, it can help to widen your watchlist to companies with different profiles and balance sheet characteristics. The Simply Wall St Screener lets you filter for specific traits so you can stress test your portfolio against a range of scenarios, not just healthcare and not just one operational playbook.
- For investors who care most about quality at a sensible entry point, scan a focused set of 30 high quality undervalued stocks that combine fundamentals with more conservative pricing.
- If consistent income is your priority, review a curated group of 8 dividend fortresses that aim to keep distributions front and center.
- When capital preservation and balance sheet strength come first, turn to a targeted list of solid balance sheet and fundamentals (24 results) to locate businesses with room to absorb shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com