
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should German Satellite Deal Require Action From Planet Labs (PL) Investors?
- Planet Labs PBC has secured an exclusive contract with Germany’s Federal Ministry of the Interior to operate a dedicated satellite constellation serving more than 400 civil institutions, and has also opened a 5,700-square-meter Berlin facility that can produce up to 60 Pelican satellites per year.
- This combination of a long-term government customer base and localized European manufacturing points to heavier upfront investment, but also greater operational control, potentially influencing how Planet Labs PBC balances capital intensity with more recurring, institutional demand.
- This article examines how Planet Labs PBC's investment narrative is shaped by the German government constellation contract and the Berlin factory.
Planet Labs PBC Investment Narrative Recap
To own Planet Labs PBC, you need to believe that high cadence, increasingly precise Earth imagery and analytics can support a large, sticky base of government and enterprise customers. The key near term swing factor remains whether recent contract wins and constellation upgrades translate into steadier, higher value solution deals without overwhelming the balance sheet with spending on new fleets and factories.
The biggest risk still sits in capital intensity and execution. Pelican upgrades, the Berlin build out and the German constellation all demand cash and flawless delivery. If launch schedules slip, AI capabilities take longer to monetize or larger account focus slows new customer adds, revenue predictability and the path toward better cash flow could come under pressure.
The Pelican 12 update is the clearest operational link between Planet Labs PBC’s German commitments and its broader catalyst story. A Gen 2 satellite that tightens imagery to 30 cm class, improves data relay and adds on orbit AI through NVIDIA Jetson directly supports the pitch of higher value, solution style contracts rather than just raw pixels.
For you as a shareholder, the relevance is in execution quality and unit economics. Faster iteration from Pelican 11 to Pelican 12, efforts to cut latency with intersatellite links and on board inference all speak to a push for more actionable data that can justify larger deals like JSAT or government constellations. Any technical setbacks or weaker than expected demand for these higher end capabilities would weigh on the core growth and margin thesis.
Planet Labs PBC’s current analyst narrative points to forecast revenues of $791.4 million and earnings of $54.3 million by 2029, based on an assumed 27.9% yearly revenue growth rate and an earnings move of about $414.2 million from a loss of $359.9 million today.
Uncover why Planet Labs PBC's fair value indicates a 93% potential upside to its current price that may not last much longer.
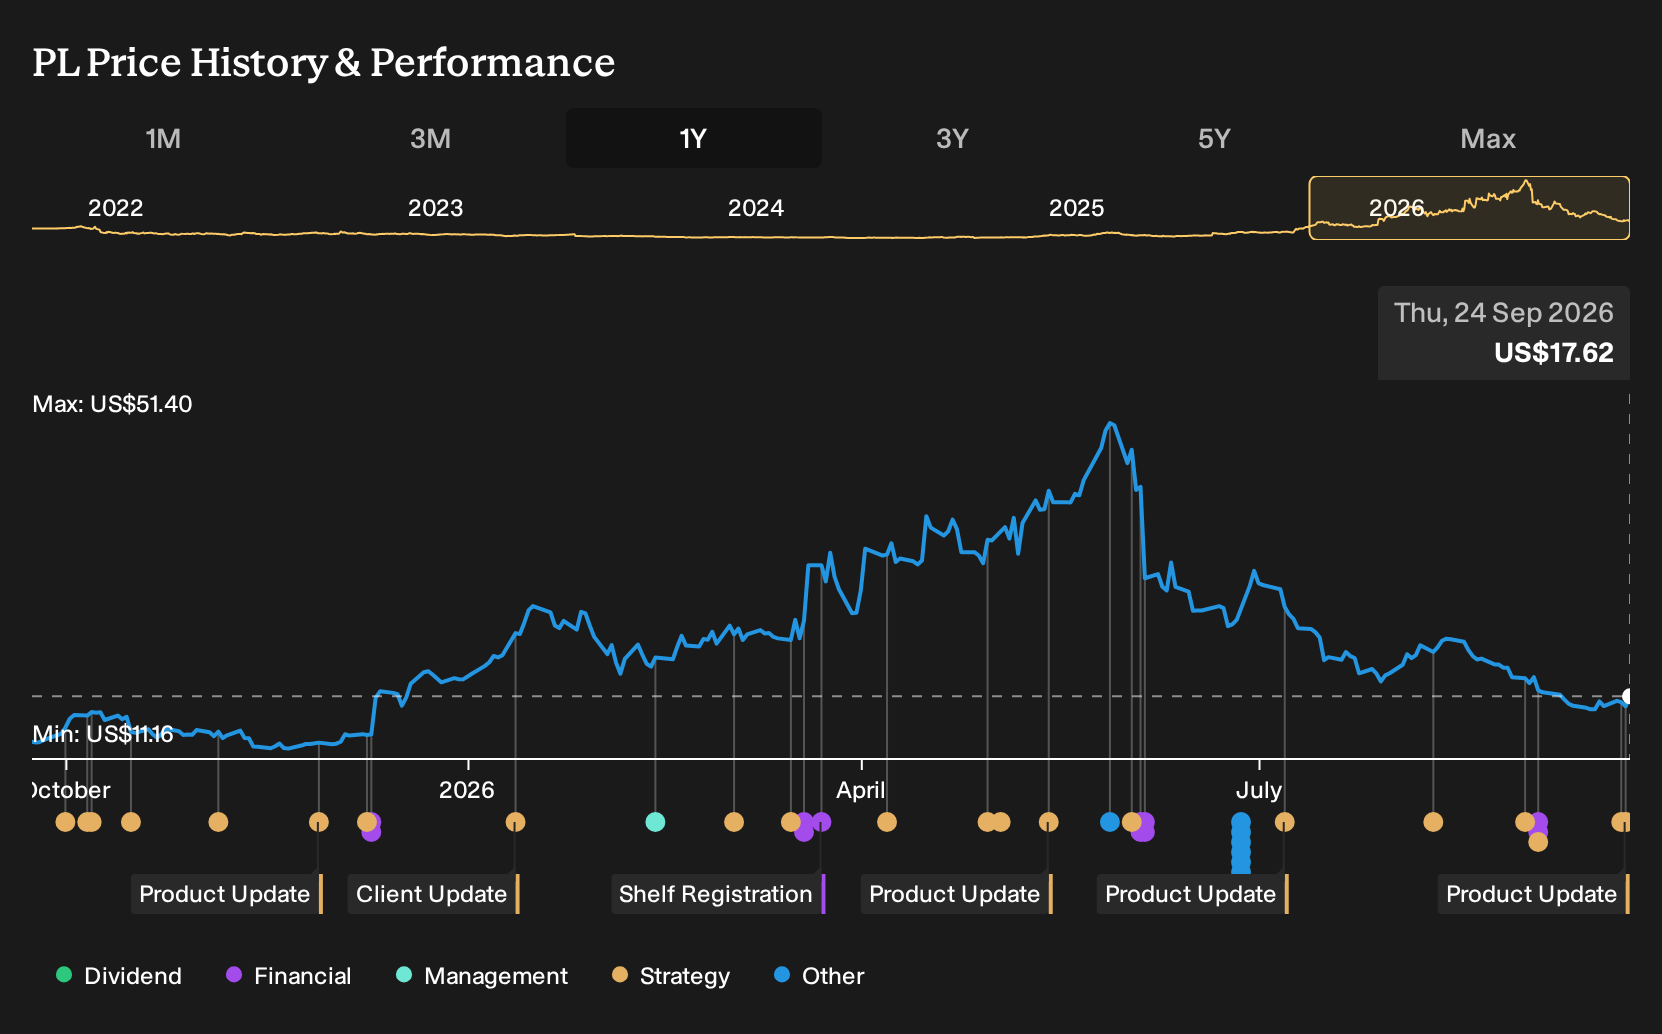
Exploring Other Perspectives
One alternate angle around Planet Labs PBC focuses on concentration risk from big sovereign deals like Germany. The most optimistic analysts were already penciling in revenue of about $896.3 million and earnings of $65.8 million by 2029 before this news. Those figures assume repeat government contracts keep compounding, which may or may not hold as narratives adjust to Pelican and Berlin developments.
Explore 8 other Planet Labs PBC fair value estimates, including one that suggests as much as 201% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Planet Labs PBC research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Planet Labs PBC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Planet Labs PBC's overall financial health at a glance.
Looking for more investment ideas beyond Planet Labs PBC?
If the Planet Labs PBC story has sharpened your thinking about risk, cash generation and long term potential, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want potential upside without ignoring financial resilience, scan through our 16 high quality undiscovered gems that combine quality metrics with under the radar profiles.
- If capital preservation and steadier fundamentals matter most to you, focus on our list of solid balance sheet and fundamentals (24 results) to see businesses with stronger financial footing.
- For those who prefer stability and income as a starting point, weigh Planet Labs PBC against companies in our 8 dividend fortresses that offer higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com