
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tokio Marine Holdings And 2 Other Japanese Dividend Stocks To Own
Japanese government bond yields recently touched a 30 year high as part of a broader global bond sell off. When bond payouts climb, income focused investors often start comparing those coupons with the regular cash cheques from dividend rich Japanese companies. That puts reliable payers with yields above 3% firmly on the radar. This article walks through three such dividend stocks from Japan and explains why they may merit closer consideration.
The three stocks covered below are just a sample. The full Dividend Powerhouses screen surfaced 539 more income ideas with yields above 3% and compelling backstories that do not fit into a short article.
If you want to identify, analyze and rank your own shortlist of higher conviction dividend payers, head straight into the Dividend Powerhouses (3%+ Yield) screener
Tokio Marine Holdings (TSE:8766)
Overview: Tokio Marine Holdings is a global insurer whose non-life and life underwriting businesses generate recurring cash flows that support its dividend.
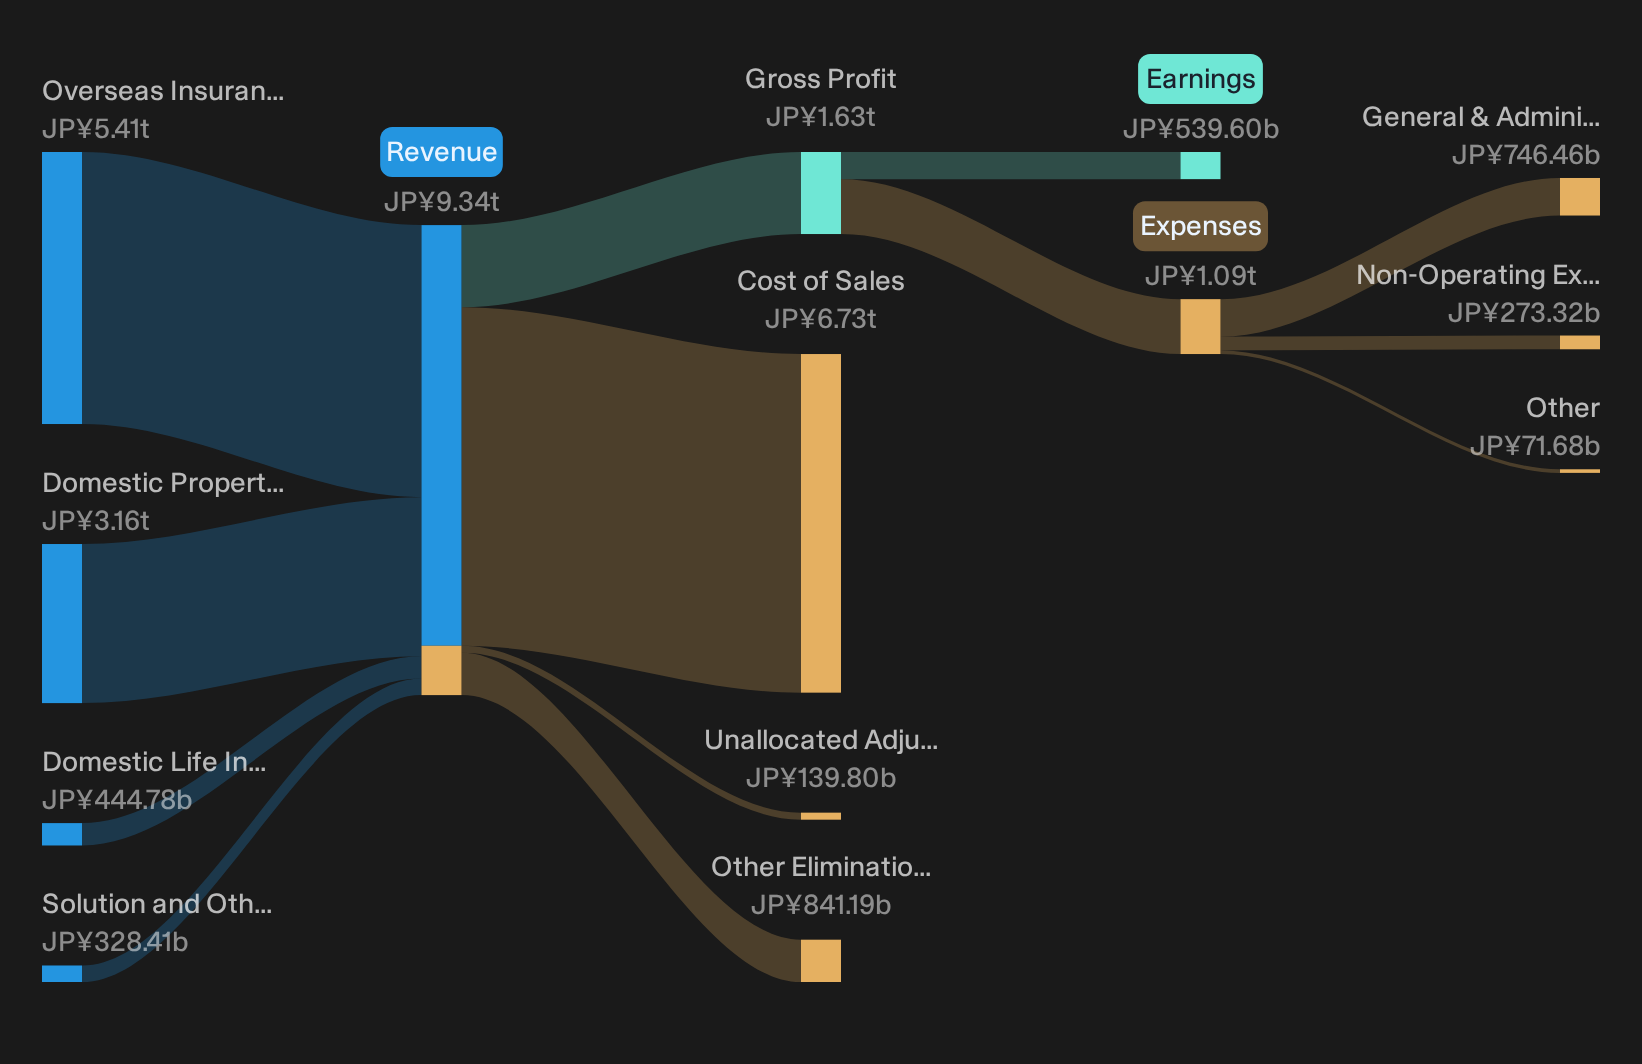
Operations: Tokio Marine earns most revenue from overseas insurance at ¥5.4t and domestic property and casualty at ¥3.2t, with smaller life and solutions units.
Market Cap: ¥15.1t
Tokio Marine Holdings matters for a dividend screen like this because its insurance engines convert regular policy premiums into recurring cash that can fund payouts.
"The Re-New initiative in their Japan P&C business aims to achieve sustainable profit growth by increasing premiums and enhancing insurance solution offerings, potentially improving underwriting profits and net margins."
Changes in any unseen pressures on those cash flows will be important in determining how durable that yield is.
Those hidden pressures and supports sit at the center of the full narrative for Tokio Marine Holdings, which explores the factors that may be accelerating or quietly capping Tokio Marine Holdings’ dividend story.
Daiichi Life Group (TSE:8750)
Overview: Daiichi Life Group is a Tokyo based insurer that uses recurring life insurance premiums and investment income, mainly in Japan, to support shareholder dividends.
Operations: Daiichi Life Group generates about ¥9.3t from Domestic Insurance Business, ¥3.7t from Overseas Insurance Business, and ¥0.6t from Other Business, before group adjustments.
Market Cap: ¥6.7t
Daiichi Life Group matters for this Dividend Powerhouses screen because its domestic life insurance arm throws off recurring cash flows that can underpin a 3%+ payout even as the group reshapes itself overseas.
"Expansion in international business, particularly in Asia and Australia, is delivering strong profit growth and improving diversification, reducing reliance on Japan's mature insurance market, and supporting higher consolidated revenue and earnings stability."
The real swing factor for Daiichi Life Group’s income story now is how one quiet shift in its earnings mix plays out.
That quiet earnings shift is exactly what the full narrative for Daiichi Life Group unpacks, revealing how Daiichi Life Group’s overseas mix could be accelerating or quietly masking its dividend story.

Japan Tobacco (TSE:2914)
Overview: Japan Tobacco is a Tokyo based tobacco group that uses its global cigarette and reduced risk brands to generate the cash flows backing its dividend, while a smaller processed food arm plays a supporting role.
Operations: Japan Tobacco generates about ¥3.6t from Tobacco, ¥162b from Processed Food and ¥5.6b from Others, with further geographic detail reported separately.
Market Cap: ¥12.2t
Japan Tobacco matters for this Dividend Powerhouses screen because its tobacco franchise provides recurring cash that supports a higher yield, while reduced risk products give the payout story more room to evolve.
"Expansion of harm-reduction products like Ploom AURA and EVO addresses evolving consumer preferences for reduced-risk options, with segment share gains and plans for accelerated international rollout supporting sustained future revenue growth and improved net margins over the medium term."
The impact on dividend strength if that shift in cash conversion and funding costs moves in the wrong direction will be crucial.
If that cash conversion shift is on your mind, the full narrative for Japan Tobacco shows where Japan Tobacco’s dividend story might be accelerating or quietly stalling next.

Seeking Alternatives Before The Crowd Moves
Fresh ideas rarely stay under the radar for long. Once momentum builds, the best entry points can become harder to access. Scan these breakout lists and consider acting before they are widely noticed.
- Look for resilient compounding stories before headlines catch up by scanning the 21 resilient stocks with low risk scores. This tool filters for durability and steadier performance while ideas are still less discussed in the broader market.
- Focus on real businesses behind the AI buzz by using the 37 profitable AI stocks that aren't just burning cash. It highlights companies already translating algorithms and data infrastructure into cash flow, not just presentations.
- Monitor the build out of tomorrow’s energy backbone through the 19 nuclear energy infrastructure stocks. It brings together infrastructure players positioned around long term power demand while they are still relatively overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com