
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For TE Connectivity Stock Could Change Following Earnings Estimate Upgrades
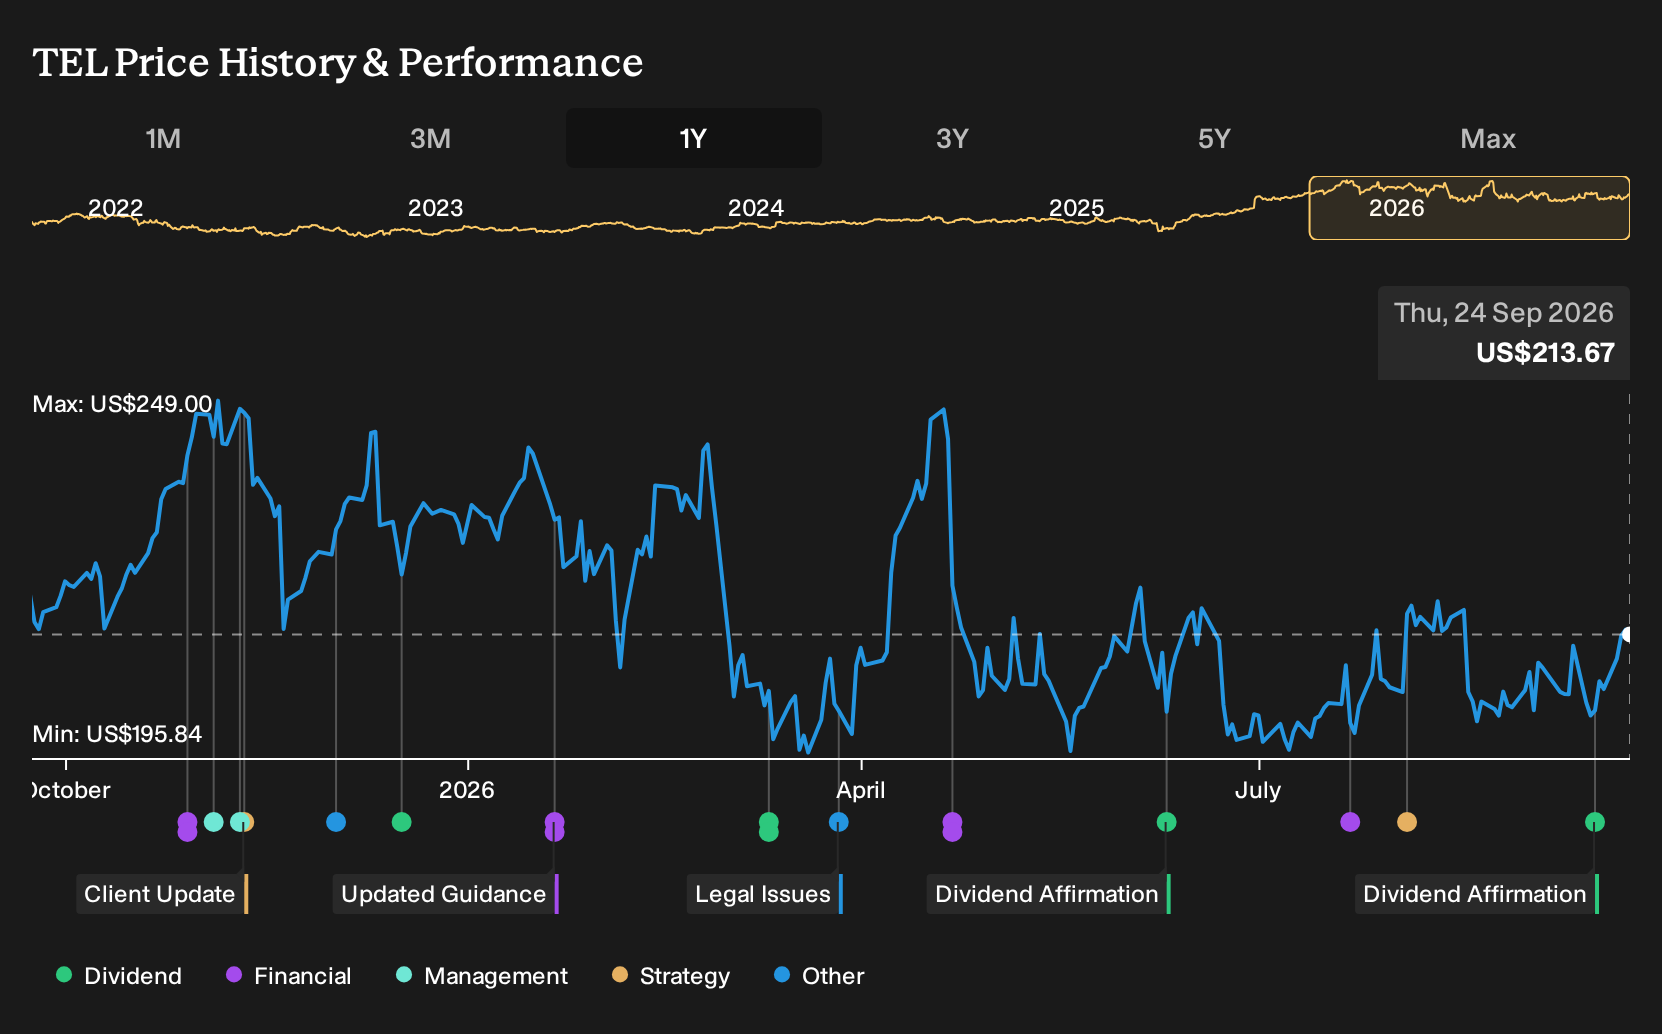
- TE Connectivity declared a regular quarterly cash dividend of US$0.78 per share for December 2026 and is showcasing its connectivity and sensor portfolio at industry events in wind energy and medical technology in Germany and Ireland.
- The confirmed dividend and presence at sector conferences highlight how TE Connectivity is balancing cash returns to investors with ongoing engagement in high-spec industrial and healthcare applications.
- We will now see how TE Connectivity's confirmed US$0.78 dividend and earnings outlook could influence the broader investment narrative.
See how TE Connectivity's latest dividend and earnings sentiment compare with other income ideas in our curated list of 8 dividend fortresses.
TE Connectivity Investment Narrative Recap
To own TE Connectivity, you need to be comfortable with a business tied tightly to AI data infrastructure, vehicle electrification, and energy grid work. That story is still about execution in Transportation and Industrial Solutions and how efficiently TE can run a localized manufacturing footprint. The fresh US$0.78 dividend declaration does not materially change those operating priorities.
The key near term swing factor remains how consistently orders convert into high margin projects in data centers, autos, and energy. The biggest risk is concentration in those same segments and regions. Any slowdown in AI, Asian transportation, or grid projects could pressure utilization and temper recent earnings momentum.
The regular US$0.78 quarterly dividend payable in December 2026 is the clearest new data point. It indicates that TE Connectivity is returning cash while also funding capacity, acquisitions, and factory optimization across its two main divisions. That balance matters if you care about both income and reinvestment discipline.
This payout sits alongside a backdrop of rising earnings and solid free cash flow conversion highlighted in earlier analysis. For catalysts, execution in AI data centers, vehicle electronics, and energy grids remains central. The dividend fits into a broader capital allocation approach rather than serving as a new driver of the business story.
TE Connectivity's current analyst story points to US$24.7b revenue and US$4.4b earnings by 2029, based on an assumed 8.5% yearly revenue growth rate and an earnings increase of about US$1.4b from US$3.0b today.
Uncover why TE Connectivity's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest TE Connectivity analysts focus on technology disruption risk. They worry that rapid shifts in connectors and sensors could leave parts of the portfolio pressured, which is why their 2029 expectations sit nearer US$24.2b revenue and US$4.2b earnings. These pre-dividend views may shift, so explore several angles before deciding what matters most to you.
Explore 4 other TE Connectivity fair value estimates, including one that suggests it could be worth just $215.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your TE Connectivity research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for TE Connectivity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate TE Connectivity's overall financial profile at a glance.
Looking For More TE Connectivity Investment Ideas?
If TE Connectivity has sharpened your view on dividends, cash returns, and earnings quality, it can be useful to compare that profile with other listed businesses that share some of those traits. The Simply Wall St Screener lets you scan the market using fundamentals, not noise, so you can build a watchlist that fits your own risk and income preferences.
- If you care most about capital strength and steady fundamentals, review our list of solid balance sheet and fundamentals (24 results) to see which businesses might offer a sturdier financial footing than the broader market.
- If value is your priority, check out the 30 high quality undervalued stocks that match stronger cash flows with what our models flag as potentially mispriced shares.
- If you want ideas that the market may be overlooking, scan the 16 high quality undiscovered gems that pair financial quality with relatively low current visibility among investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com