
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Methanex (TSX:MX) Has Drawn Fresh Attention, What Is The Market Weighing?
Methanex (TSX:MX) has been drawn into the spotlight after M&G Investment Management disclosed ongoing engagement with the board and executives on issues such as capital structure, governance, and potential directions for improving shareholder value.
Recent trading has been strong for Methanex, with the share price up 24.1% over the past 90 days and a 50.9% year to date share price return. The 1 year total shareholder return of 60.6% suggests momentum has been building ahead of M&G’s engagement and the recent partial bond redemption announcement.
Scan how Methanex compares with other materials players showing strong price action and potential value gaps through the curated 5 high quality undervalued stocks.
The share price has already run hard and activist pressure is now on the table. Does Methanex still offer an appealing trade off between upside potential and downside risk at this valuation?
Most Popular Narrative: 7% Undervalued
On the latest numbers, the most followed narrative pegs Methanex’s fair value at CA$91.07 against a last close of CA$84.47. This frames the current activist interest against a valuation that still screens as discounted on those assumptions.
Methanex expects methanol demand to grow in 2025, driven by traditional chemical and energy applications, which could boost revenues.
Increased production at key facilities, such as Geismar and Chile, along with improved operational efficiency, positions the company to capitalize on favorable pricing, potentially enhancing net margins and earnings.
See why 15 investors see Methanex as 7% undervalued.
The fair value of CA$91.07 comes from a discounted cash flow style narrative that applies a 7.66% discount rate to forecast earnings and cash generation. That framework assumes Methanex can lift profit margins into the high teens, keep capacity well utilized and convert a large portion of operating income into free cash flow over time.
Under that storyline, the current CA$84.47 price sits below the CA$91.07 assessment. This reflects expectations for earnings to grow meaningfully faster than the broader Canadian market, even as past five year profit trends have been weak and recent margins have compressed. Activist engagement, debt reduction plans and production decisions, such as idling higher cost Trinidad plants, all sit in the background of this thesis because they influence whether those cash flow forecasts can be met.
Result: Fair Value of CA$91.07 (UNDERVALUED)
Still, the narrative can unravel if contracted gas supplies tighten further or the OCI integration drags, which could put both Methanex volumes and margin ambitions under pressure.
Find out about the key risks to this Methanex narrative.
Another View On Methanex’s Valuation
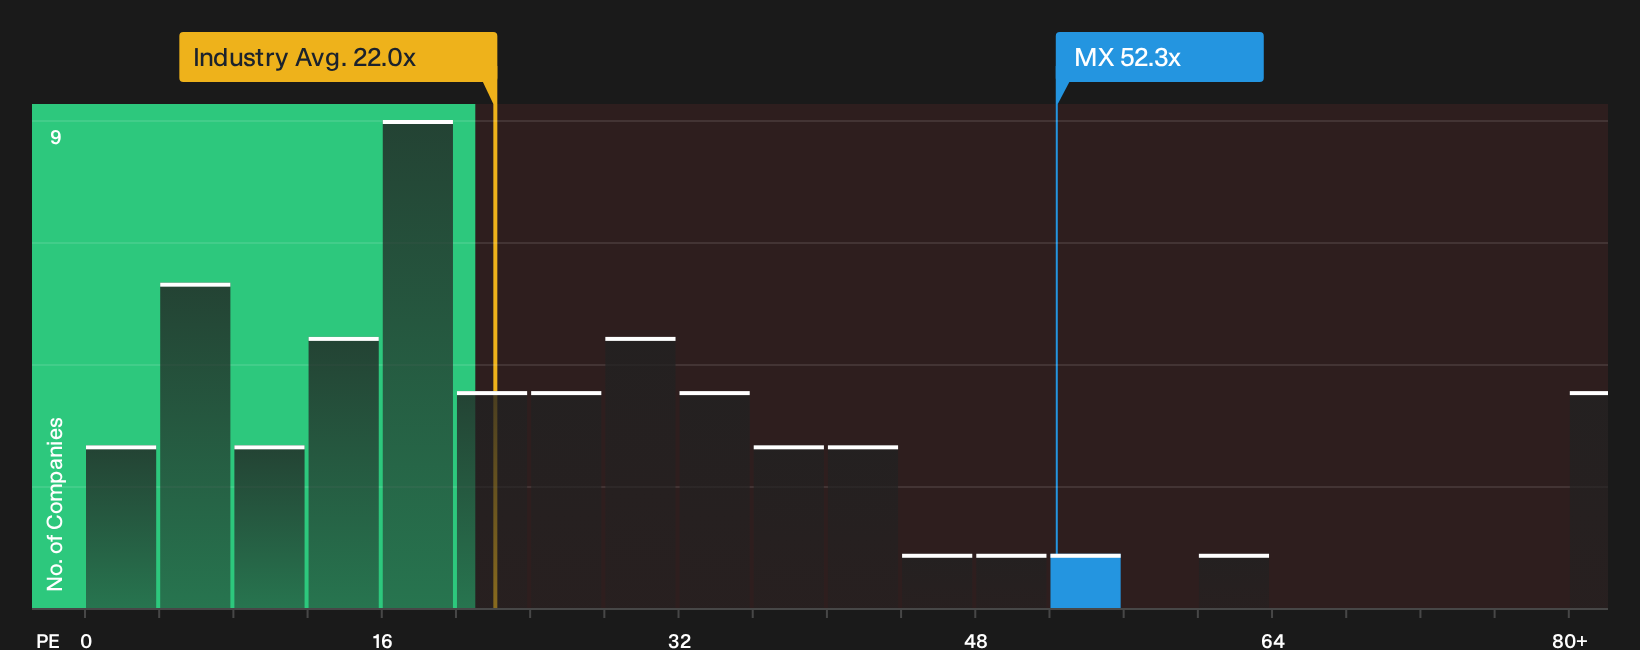
The earlier fair value story leans on rich cash flow forecasts and margin repair. A very different picture comes from today’s earnings multiple. Methanex trades on a P/E of 52.3x, which looks expensive beside the Chemicals industry at 22.3x, the peer average at 41x, and a fair ratio of 21x. That kind of gap can either narrow through price, or through future profit catching up. Which outcome do you think is more realistic?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Methanex now in focus and opinions clearly split, move quickly from narrative to numbers and shape your own view by weighing the 2 key rewards and 4 important warning signs.
Looking for more Methanex-like investment ideas?
If you want more potential opportunities beyond Methanex, use the Simply Wall Street Screener to quickly surface fresh ideas that match your own risk and return preferences.
- Hunt for quality at a discount by scanning companies that currently screen as promising value opportunities through the curated 5 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses that show strong financial footing and clean balance sheets using the targeted list of solid balance sheet and fundamentals (7 results).
- Spot early-stage potential by filtering for smaller companies with robust financial characteristics and room to grow through the focused 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com