
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PNC Financial Services Group (PNC) Pullback Puts Its AI Efficiency Narrative And Valuation In Focus
Recent trading in PNC Financial Services Group (PNC) has caught attention after a slide of about 8% over the past month and close to 9% over the past 3 months, prompting fresh questions on valuation and risk.
Across a longer window, the picture is more mixed. PNC Financial Services Group’s share price is still up 5.62% year to date and the 1-year total shareholder return sits at 13.79%. However, the recent 7-day and 3-month pullback suggests momentum is fading as investors reassess growth prospects and risk around the current US$223.34 level.
Compare PNC Financial Services Group’s recent pullback with other banks that screen well on balance sheet strength and fundamentals by scanning our curated list of solid balance sheet and fundamentals (24 results) today.
PNC Financial Services Group now trades at a clear discount to both analyst targets and one intrinsic value estimate after that recent drop. Is this caution about the bank’s outlook sensible, or has pricing moved beyond fair value?
Most Popular Narrative: 19.6% Undervalued
On the most followed view of PNC Financial Services Group, the fair value estimate of about $277.73 sits well above the recent $223.34 close, so the key question is whether the long term efficiency and growth plan behind that figure holds up.
PNC Financial Services Group expects its multi year AI and automation program, which targets about 40 points of operating leverage from 2025 to 2030 on top of earlier gains and focuses on roughly 171 opportunities and US$1.4b of addressable spend, to further support net margins and earnings.
What is behind that confidence in PNC Financial Services Group’s efficiency plan 48 investors see PNC Financial Services Group as 20% undervalued.
Result: Fair Value of $277.73 (UNDERVALUED)
Still, PNC Financial Services Group’s story can break if fee based businesses slow materially or if credit costs jump and compress the margins that underpin those valuation assumptions.
Find out about the key risks to this PNC Financial Services Group narrative.
Another View On PNC Financial Services Group’s Valuation
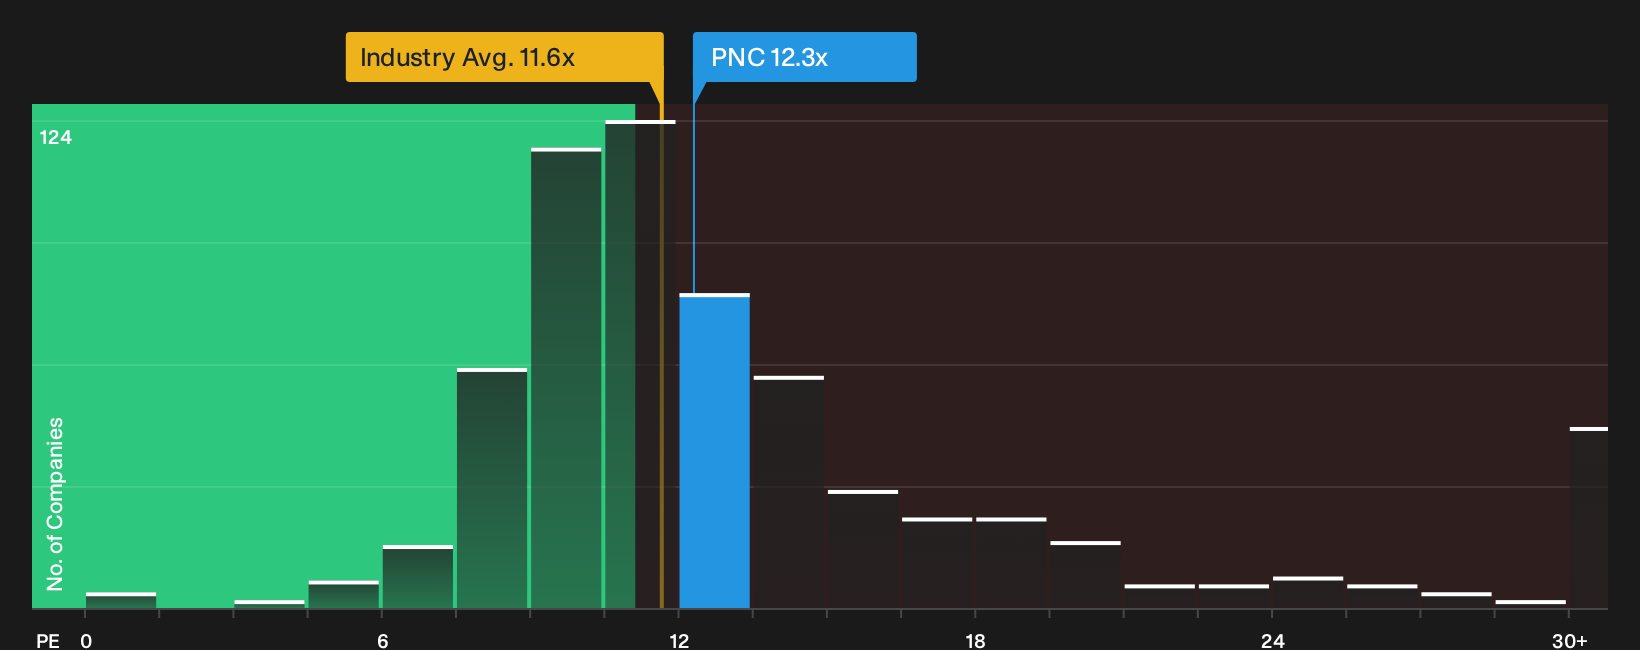
The earlier fair value of $277.73 leans on long term earnings forecasts. A simpler lens looks at today’s P/E of 12.3x, which is higher than the US Banks industry at 11.6x, yet below a fair ratio of 14.2x. That contrast highlights both valuation risk and potential upside. Which side appears more convincing to you?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around PNC Financial Services Group is clearly split, so consider acting promptly, review the full picture, and shape your own stance by weighing both upside and downside using 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond PNC Financial Services Group?
If PNC Financial Services Group has sharpened your focus on valuation and risk, you can use that momentum to scan fresh opportunities across sectors and business models.
- Shift your watchlist toward potential mispricings by reviewing our curated set of 30 high quality undervalued stocks that pair solid fundamentals with market skepticism.
- Strengthen your income stream by checking out 8 dividend fortresses that combine higher yields with payout profiles worth a closer look.
- Dial down portfolio volatility by screening 30 resilient stocks with low risk scores built around resilient financials and milder historical drawdowns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com