
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Veeva Systems Stock's AI Study Tool Launch Means For Shareholders
- Veeva Systems recently introduced Veeva Study Builder Agent to configure EDC and data quality setups from study protocols, and Oxford Biomedica selected Veeva Quality Cloud to consolidate quality, content, and training on a single platform.
- Together, the new AI driven study configuration tool and the Oxford Biomedica Quality Cloud rollout highlight how Veeva is pushing deeper into workflow automation for clinical development and manufacturing clients.
- The focus now turns to how Veeva Systems' expanding AI agents and Quality Cloud adoption could influence the long term investment narrative.
Veeva Systems Investment Narrative Recap
To own Veeva Systems, you need to believe life sciences clients keep standardizing critical workflows on its cloud, from clinical data to quality and commercial engagement. The near term story hinges on whether new AI agents like Study Builder Agent translate into real usage across existing customers rather than just pilot buzz. The latest launches point in that direction but do not fundamentally change the near term setup yet.
The biggest operational risk still sits with customer adoption and potential agent fatigue, especially as competitors such as Salesforce and Microsoft push deeper into healthcare workflows. Heavy spend on AI, new suites, and consulting could also weigh if uptake slows or biopharma budgets tighten. These announcements help the narrative around product depth, but the key proof remains execution and renewals.
Among the recent updates, Oxford Biomedica’s decision to roll out Veeva Quality Cloud looks most relevant to the current news stream. It shows how Veeva Systems is not only adding AI agents on the R&D side but also trying to become the central system for quality, content, and training in complex manufacturing environments such as cell and gene therapy.
For catalysts, a successful Quality Cloud deployment at Oxford Biomedica would support the thesis that customers consolidate more workflows on Veeva platforms, which can help stickiness and cross sell potential. The flip side is clear. If large reference clients struggle to standardize processes on Veeva or resist further expansion into AI driven products, that would reinforce concerns about adoption risk and future ROI on the company’s heavier product investment.
Veeva Systems' current analyst storyline points to revenues of $4.7b and earnings of $1.4b by 2029, built on an assumed 12.7% yearly revenue growth rate and an earnings move of roughly $458.3m from $941.7m today to that 2029 consensus level.
Uncover why Veeva Systems' fair value indicates a 9% potential downside to its current price, suggesting that the current premium may not be sustainable.
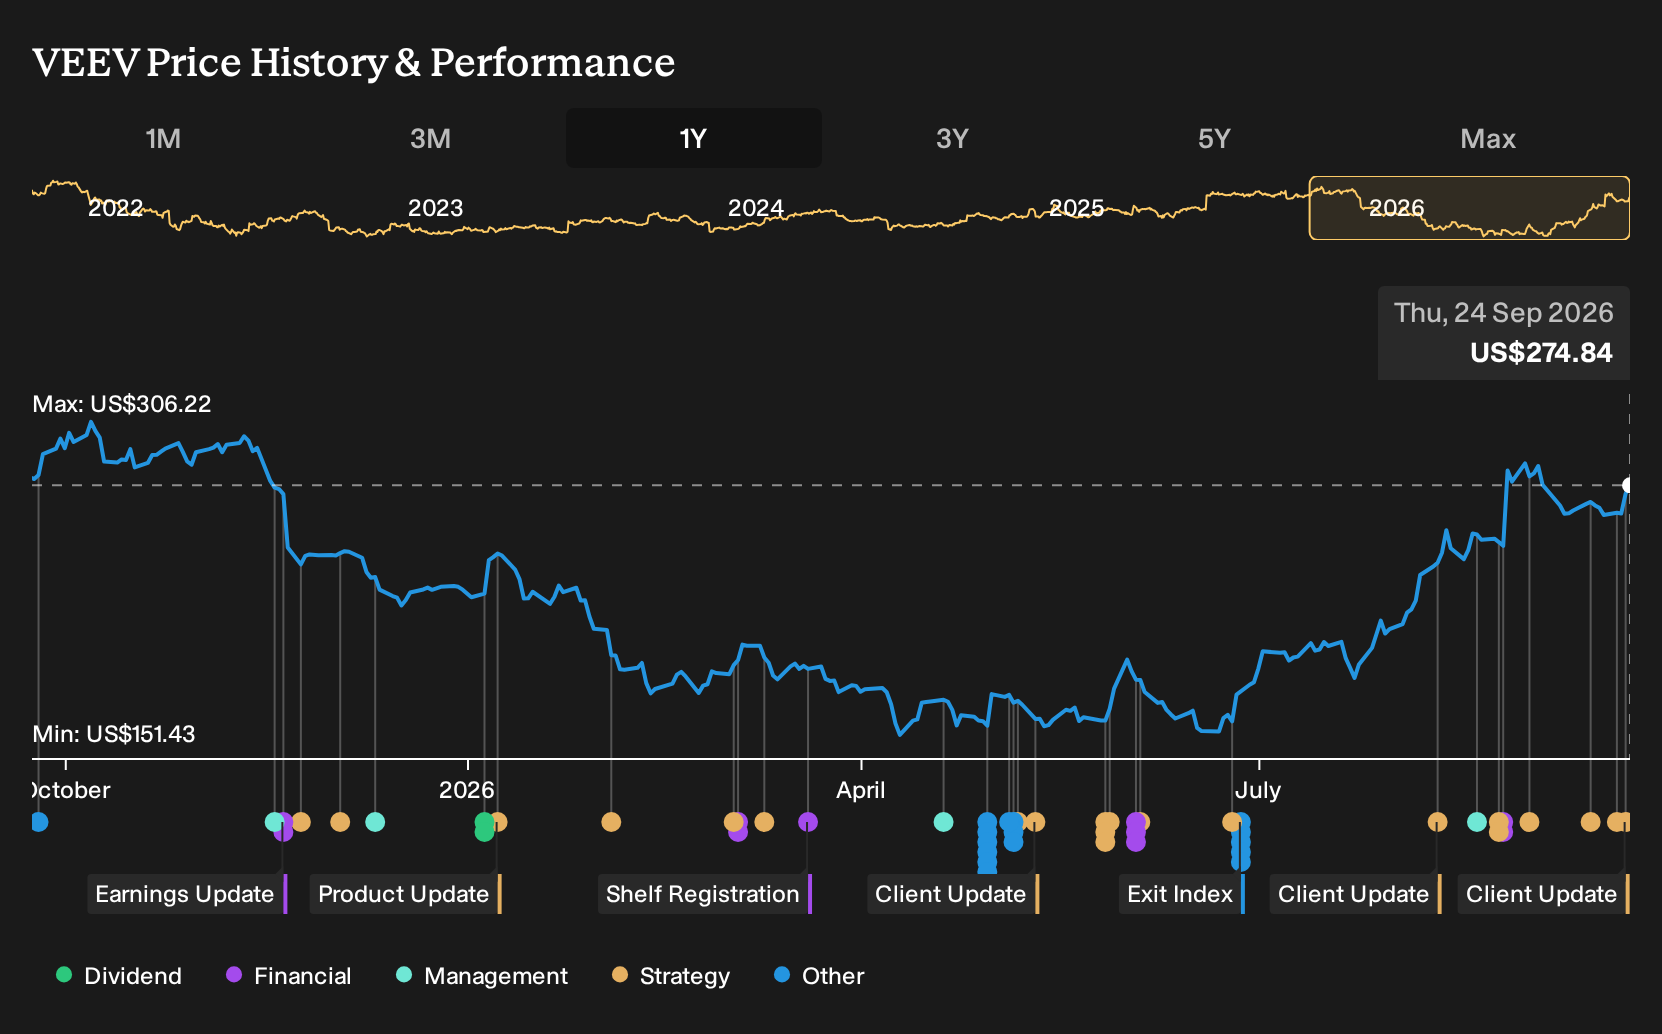
Exploring Other Perspectives
Some of the most optimistic analysts lean into Quality and manufacturing as the swing factor for Veeva Systems. They had been modeling revenue of about $5.1b and earnings near $1.6b by 2029 before this news. You can see how Study Builder Agent and the Oxford Biomedica rollout might push those already upbeat views even further, or challenge them if adoption proves slower than hoped.
Explore 7 other Veeva Systems fair value estimates, including one that suggests potential upside of as much as 39% from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Veeva Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Veeva Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veeva Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Veeva Systems?
If the Veeva Systems story has you thinking about where else workflow automation, strong balance sheets, or dependable cash flows might show up, the Simply Wall St Screener can help you widen the net while still keeping your process disciplined.
- For investors hunting for mispriced quality, start by scanning a 30 high quality undervalued stocks that pair solid fundamentals with more modest expectations baked into their prices.
- If capital preservation and smoother ride potential are higher on your list, filter for 30 resilient stocks with low risk scores that may offer more resilient profiles through different market conditions.
- When the goal is to back robust finances first and stories second, zero in on a list of solid balance sheet and fundamentals (24 results) that can give you more confidence in a company’s ability to absorb setbacks and fund its own growth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com