
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lamb Weston Holdings (LW) Files ESOP Shelf Registration, Is The Stock A Bargain?
Lamb Weston Holdings (LW) filed a shelf registration for about $182.9 million in common stock tied to an employee stock ownership plan, giving investors fresh context for thinking about dilution, liquidity, and long term incentives.
Over the past month, Lamb Weston Holdings has seen its share price fall about 19.9%, with the 7 day share price return also declining 4.5%. The stock is still slightly positive year to date with a 4.9% share price gain, while the 1 year total shareholder return is down 13.4%. This suggests that recent momentum has been fading even after earlier strength and may reflect investors reassessing growth potential and dilution risk following the Q2 earnings reaction and this new ESOP related shelf registration.
Spot similar stories of fading momentum and dilution risk across our curated 30 high quality undervalued stocks, which still pair cash flow strength with balance sheet resilience.Lamb Weston Holdings now trades well below both its analyst target and internal fair value estimates after a sharp pullback. Does that gap reflect opportunity, or a reset that still has further to run before value feels clear?
Most Popular Narrative: 20% Undervalued
Lamb Weston Holdings closed at $44.37, while the most widely followed narrative pegs fair value at $55.25 using a 7.24% discount rate. That gap puts the focus squarely on whether the cost savings and international reset story gets delivered as laid out.
The multi year cost savings program targeting at least US$250 million of annualized run rate savings by fiscal 2028 has already surpassed the first year US$100 million milestone, and further execution on operational streamlining and supply chain efficiency could lift net margins and EBITDA.
See why 22 investors see Lamb Weston Holdings as 20% undervalued.
Result: Fair Value of $55.25 (UNDERVALUED)
Still, the Lamb Weston Holdings story can unravel if international earnings stay weak under excess fry capacity, or if ERP related class actions escalate legal and operational costs.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Multiples Paint A Tougher Picture
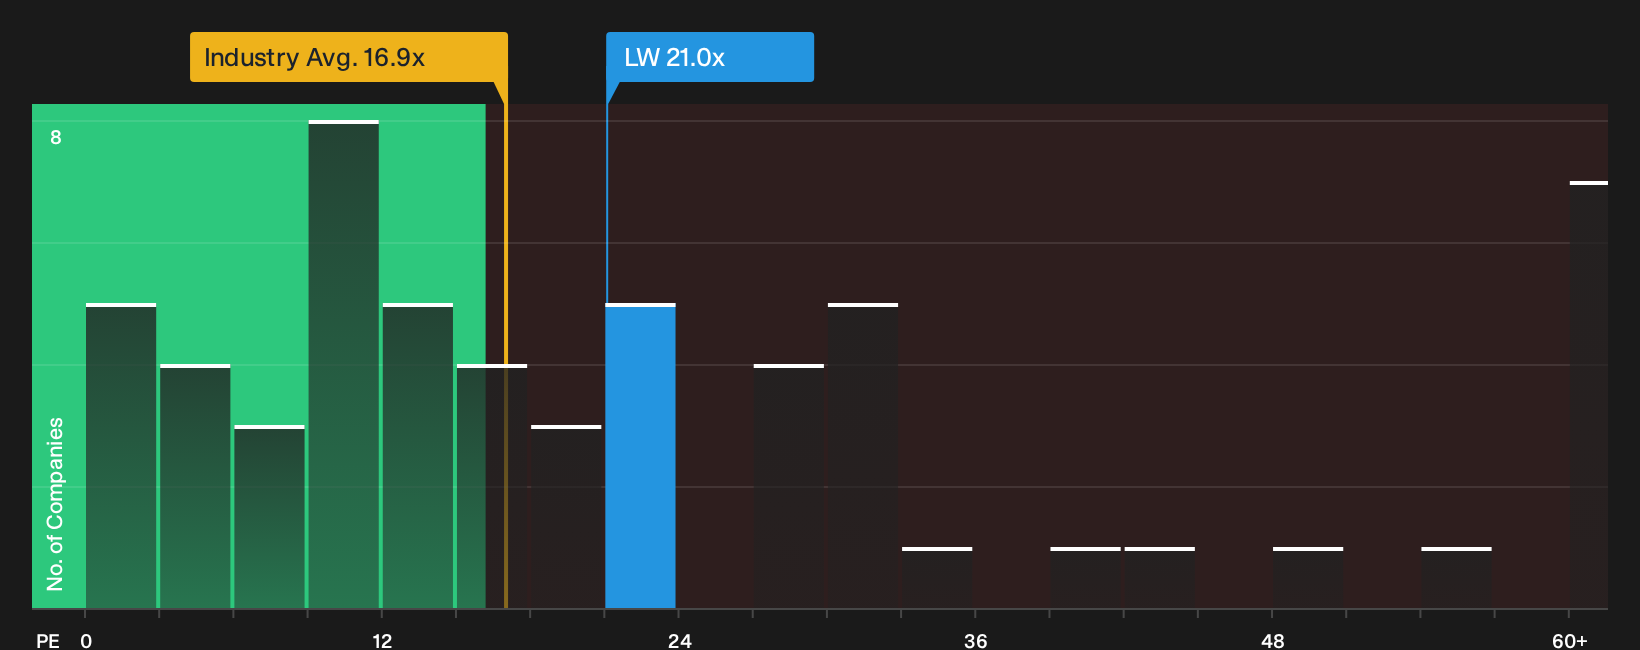
The DCF work around Lamb Weston Holdings points to value, yet the simple earnings multiple tells a tougher story. The stock trades on a P/E of 21x, which is higher than the US Food industry at 16.9x, the peer average at 9.9x, and even above its own 20.8x fair ratio. That gap suggests investors are already paying up for execution to improve, so it may be worth considering how comfortable you feel underwriting that premium if the narrative takes longer to play out.
For a closer look at what the numbers imply about that premium, and whether it may compress or persist, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Lamb Weston Holdings' story so far. If you want to move fast and form your own view based on both caution and optimism, take a closer look at the 4 key rewards and 2 important warning signs.
Looking for more Lamb Weston Holdings sized ideas?
Round out your watchlist with a few fresh angles. The right mix of quality, resilience, and upside potential often starts with a smart screening process.
- Zero in on resilient businesses by checking the 30 resilient stocks with low risk scores that keep volatility in check while still offering room for thoughtful growth.
- Hunt for quality at a discount by scanning the 16 high quality undiscovered gems that pair solid fundamentals with limited current attention.
- Build a sturdier core for your portfolio by reviewing the list of solid balance sheet and fundamentals (24 results) that prioritise financial strength before headlines move.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com