
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Thomson Reuters (TSX:TRI) Lifts 2026 Outlook, Is It Still 20% Below Fair Value?
Thomson Reuters (TSX:TRI) has become a talking point after updating its 2026 outlook, highlighting organic expansion and new AI tools, while investors weigh rising AI competition and a recent C-Track platform data breach.
Recent trading has been choppy for Thomson Reuters, with the share price rising 2.26% over the last day and 1.97% over the past week, while slipping 1.59% over 30 days and declining 19.52% year to date. That shorter term momentum contrasts with a stronger 90 day share price return of 19.25%. Total shareholder return is down 33.89% over one year but still positive at 10.29% over five years, which indicates that sentiment has cooled recently as investors weigh the longer term track record alongside AI ambitions, competitive pressures and the C Track incident.
Scan beyond Thomson Reuters and see how other AI focused information and software providers are priced and positioned using our curated list of 9 high quality undiscovered gems.
Bulls point to Thomson Reuters’ organic expansion, AI push and updated 2026 plans. Bears focus on the share price slide, rising AI rivals and the C Track breach. Which side does the current valuation lean toward?
Most Popular Narrative: 20% Undervalued
On the most followed view, Thomson Reuters screens as undervalued, with a fair value of about CA$178.25 against a last close of CA$141.95. This puts AI execution, legal tech competition and capital deployment under the spotlight.
The company's proprietary, authoritative content and integrated product suite positions it as a trusted platform, benefiting from the global proliferation of data and increasingly complex regulatory environments. This "category leader" status, combined with tight workflow integration, supports higher client retention and market share gains, boosting long-term recurring revenues.
See why 27 investors see Thomson Reuters as 20% undervalued.
The narrative is built using a 6.72% discount rate and projects revenue growth of roughly 8.3% a year and earnings expansion of 11.8% a year, which together underpin a fair value estimate around CA$178.25. That compares to the current CA$141.95 share price and implies the stock trades at a 20.4% discount to this fair value marker based on Simply Wall St's model.
Analysts in this framework also assume profit margins move from 21.4% toward about 24.0%, with earnings reaching roughly US$2.4b by 2029 and the shares trading on a forward P/E of about 27x. Those assumptions sit above the current US Professional Services P/E level of 16.6x, which means this thesis leans on Thomson Reuters continuing to justify a premium through content depth, AI workflow tools and recurring subscription strength.
For investors weighing the recent share price slide against the updated 2026 outlook and the C Track breach, the key question is whether those growth, margin and valuation assumptions feel realistic given rising AI rivals and higher compliance costs. The model does not remove risk, but it gives a concrete set of revenue, earnings and multiple outcomes you can test against your own expectations for Thomson Reuters.
Result: Fair Value of CA$178.25 (UNDERVALUED)
Still, this hinges on Thomson Reuters defending its premium against fast moving AI competitors and avoiding costly integration missteps that could drag on margins.
Find out about the key risks to this Thomson Reuters narrative.
Another View On Thomson Reuters Valuation
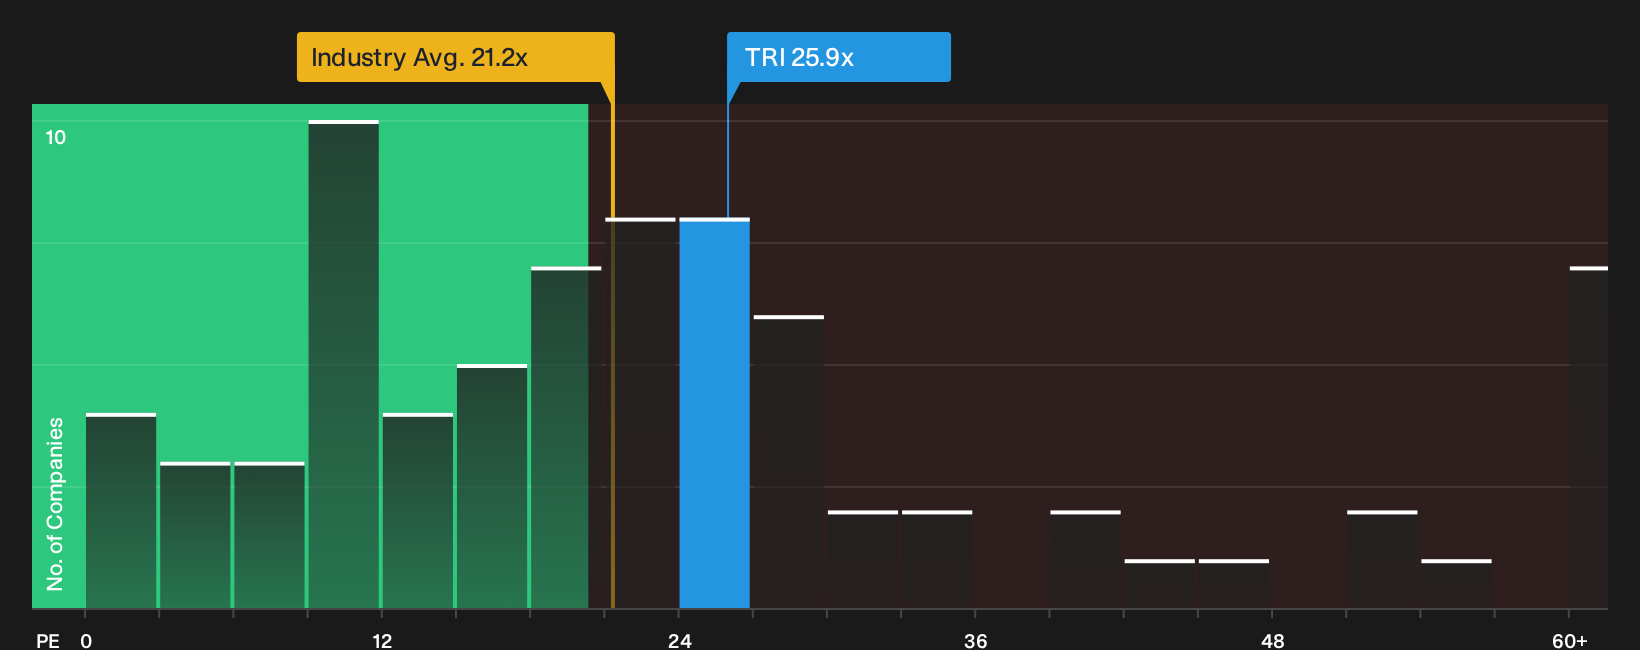
On simple earnings multiples, Thomson Reuters does not look cheap. The shares trade on a P/E of 25.9x, above both the North American Professional Services average of 21.2x and direct peers at 21.8x. Yet the fair ratio sits higher at 31.4x, which points to possible upside if the market leans toward that benchmark. How much weight do you give that gap versus the premium already in the price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Thomson Reuters only matters if you act on it quickly and test the assumptions yourself before the next catalyst lands. To weigh both the potential upsides and the concerns already on investors’ radar, start by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Thomson Reuters?
If you stop at Thomson Reuters, you only see one angle. Broaden your watchlist now and you might catch opportunities before everyone starts paying attention.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through our 5 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding payers using the 1 dividend fortresses.
- Dial down downside risk by focusing on resilient businesses with strong risk scores through the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com