
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GEO Group (GEO) Stock Looks Above Fair Value Following Its 328% Run
GEO Group has turned into a high profile prison and detention operator for equity markets after a long stretch of strong share price gains. This naturally raises a harder question for you as an investor: Is the current US$31.96 price being backed up by the company’s earnings power, or has the stock price moved ahead of what the underlying business is generating today?
- Over the past 5 years, GEO Group has returned about 327.8%, which puts a lot of pressure on today’s valuation to be grounded in its earnings rather than just sentiment.
- The business model is heavily tied to long term correctional and detention contracts, which can support relatively visible revenue streams and put the focus on how efficiently those earnings are being converted into cash.
- Your read on GEO Group is one view; the desks covering it have another. See what analysts think GEO Group's shares could be worth.
The issue now is whether GEO Group’s current share price is justified by what its earnings suggest the company is worth.
If you are weighing whether GEO Group’s US$31.96 price is genuinely supported by its earnings, it can help to compare that question across 30 high quality undervalued stocks.
Does GEO Group Look Pricey on Earnings?
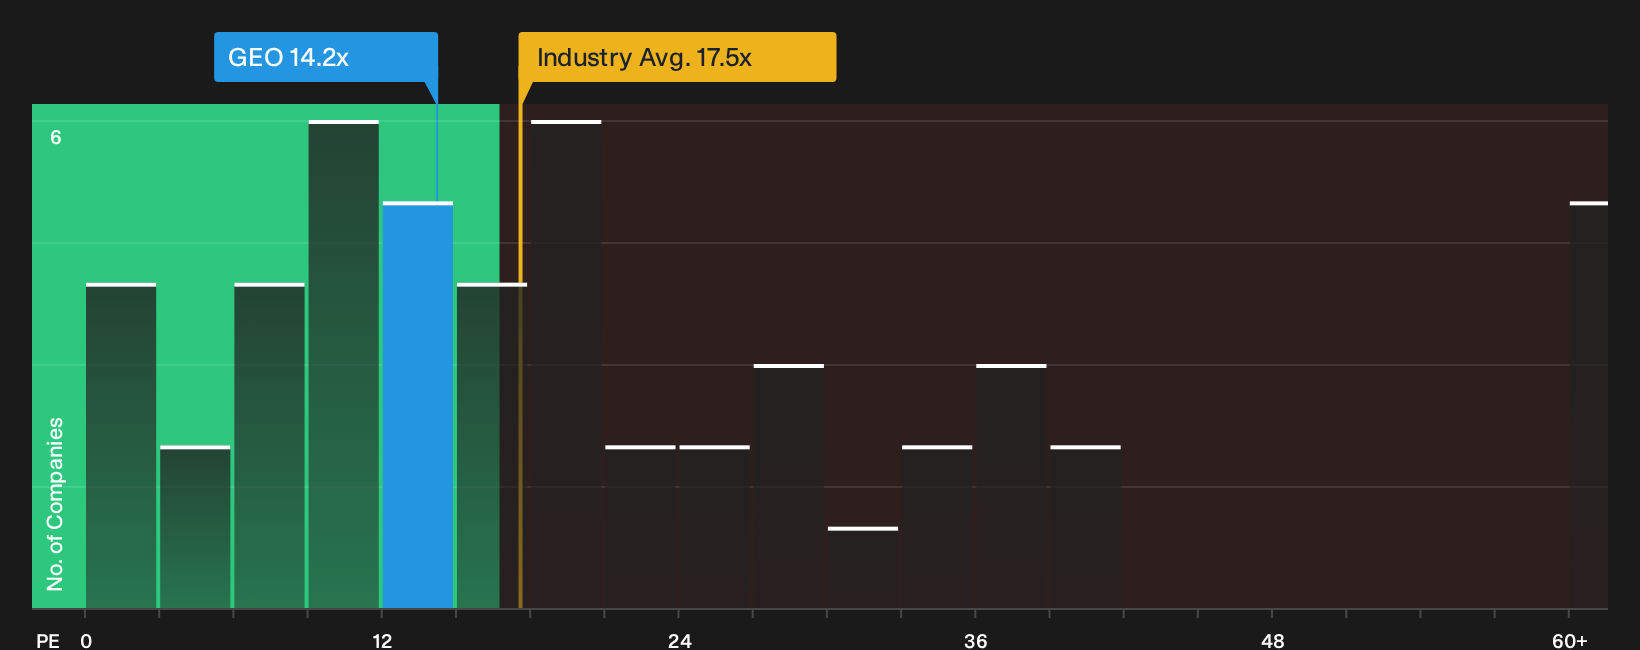
The P/E ratio is a useful lens for GEO Group because earnings are a key yardstick for a contracted, cash focused operator. At about 14.2x earnings, GEO Group trades below the Commercial Services industry average P/E of roughly 17.5x and also below the broader peer group at about 27.5x. This points to a lower earnings multiple than many comparable stocks.
The fair P/E suggested by a more tailored model that blends GEO Group’s profitability profile, risk and scale sits above the current 14.2x level. On this framework the shares screen overvalued even though they look cheaper than sector and peer averages. That mix leaves you weighing whether the discount to the industry reflects caution about GEO Group’s specific risk profile or whether the model is being conservative about the quality and durability of its earnings power. Explore the numbers behind GEO Group's P/E valuation.
The GEO Group Narrative: What Would Justify Today's Price?
Narratives on GEO Group pick up where this valuation puzzle leaves off by explaining which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each scenario links GEO Group's potential value to a specific storyline about its contracts, political risk and balance of opportunities and threats on Simply Wall St’s Community page, so you can see over time which version of events aligns more closely with reality.
GEO Group draws out two very different angles from the community, with one side seeing more upside in the existing assets than the other.
Bull case: 15% undervalued
"The company's recent substantial debt reduction, refinancing at lower rates, and asset sales, together with a newly authorized $300M share repurchase program, reinforce a positive long-term outlook for earnings per share and financial resilience..."
Discover why this Narrative puts GEO Group at 15% undervalued.
Bear case: roughly fairly valued
"Reliance on government funding and contract expansions is tempered by high execution risks, political shifts, and ongoing criminal justice reform pressures threatening future demand..."
Explore why this Narrative puts GEO Group at roughly fairly valued.
One more GEO Group question before you make a move
There is a separate lens that compares where GEO Group trades today with where professional analysts expect earnings and cash generation to sit a few years from now. That extra layer can shift how this valuation feels once you see it. Explore where analysts expect GEO Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com