
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lennox International Stock: Is LII Underperforming the Industrial Sector?
Lennox International Inc. (LII), headquartered in Richardson, Texas, designs, manufactures, and markets products for the heating, ventilation, air conditioning, and refrigeration markets. Valued at $12.9 billion by market cap, the company sells its products and services through direct sales, distributors, and company-owned parts and supplies stores.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and LII perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the building products & equipment industry. LII excels in the HVACR industry with its flagship brand, known for quality and reliability. By focusing on North America, the company has streamlined operations and reinforced its market position, leveraging strong brand recognition and customer loyalty.
Despite its notable strength, LII slipped 37.4% from its 52-week high of $587.27, achieved on Jul. 1. Over the past three months, LII stock has declined 33.3%, underperforming the State Street Industrial Select Sector SPDR ETF’s (XLI) 6.3% losses during the same time frame.
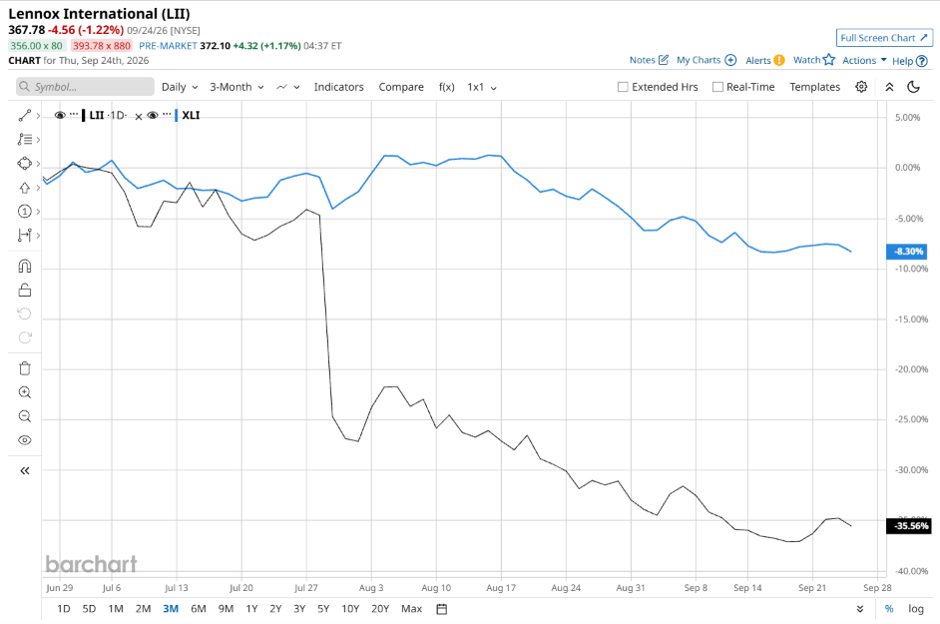
In the longer term, shares of LII fell 24.3% on a YTD basis and dipped 29.6% over the past 52 weeks, notably underperforming XLI’s YTD gains of 8.8% and 10.9% returns over the last year.
To confirm the bearish trend, LII has been trading below its 50-day and 200-day moving averages since late July.
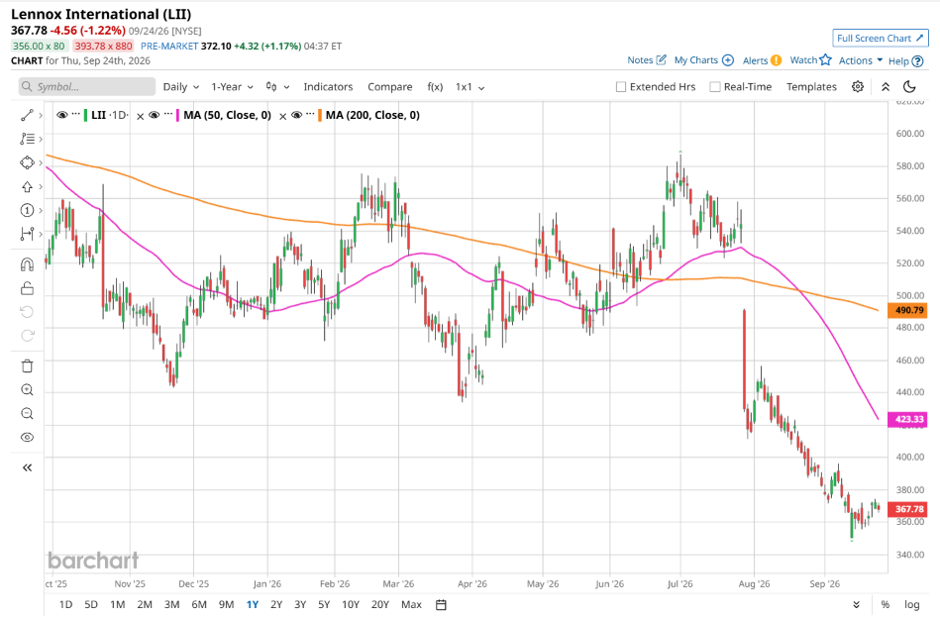
LII’s underperformance was driven by weak residential demand and a cut to profit guidance. CEO Alok Maskara noted "end-market recovery remains muted" as affordability pressures, inflation and soft consumer sentiment hurt Home Comfort Solutions, compounded by LII's strategic exit from low-margin new construction business which created fixed-cost absorption headwinds. CFO Michael Quenzer said the lower earnings outlook is "primarily driven by lower net volume expectations," but free cash flow targets remain intact, supported by pricing actions, tariff refund timing, and working capital discipline. Management now expects residential recovery to be pushed to 2027, with near-term focus on commercial momentum, cost control, and investments in digital and product innovation.
In the competitive arena of building products & equipment, Trane Technologies plc (TT) has taken the lead over LII, with 12.7% gains on a YTD basis and an 8.5% uptick over the past 52 weeks.
Wall Street analysts are reasonably bullish on LII’s prospects. The stock has a consensus “Moderate Buy” rating from the 18 analysts covering it, and the mean price target of $495.54 suggests a notable potential upside of 34.7% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.