
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Western Digital (WDC) Fully Valued As Earnings Optimism Builds?
Renewed attention on Western Digital (WDC) is building ahead of its upcoming earnings report, as investors weigh expectations for higher profit and revenue compared with the previous year against recent share volatility and valuation concerns.
Western Digital’s recent share price tells a story of strong momentum meeting fresh caution, with the stock up 6.24% over the last week and 139.91% year to date, yet down 23.21% over 90 days as some investors reassess valuation and risk ahead of earnings. At the same time, the 1-year total shareholder return of 320.81% and very large 3-year and 5-year total shareholder returns suggest long-term holders have already seen substantial gains, which can amplify sensitivity to any shift in expectations around AI data center demand and profitability.
Scan how Western Digital’s AI storage story compares with other potential breakouts across our hand picked 84 AI infrastructure stocks to see where expectations and pricing look more aligned.
The recent surge in Western Digital, coming after a sharp 90 day pullback, forces a choice: Do you pay up now for the AI storage story or wait for a cooler entry before judging the valuation case?
Most Popular Narrative: 37% Overvalued
Western Digital last closed at $450.31, while the most followed narrative pegs fair value at $329.76, which implies the current AI storage enthusiasm already bakes in a premium to that framework.
The AI storage demand is real and probably durable. The question is not whether the drives get bought, but for how long the two companies making them choose discipline over market share. Almost everything in the valuation flows from that one decision, made quarter after quarter, by people whose incentives can change.
See why 36 investors see Western Digital as 37% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s narrative can crack if the HDD duopoly chases capacity too aggressively, or if cheaper flash and China supply shift storage economics faster than expected.
Find out about the key risks to this Western Digital narrative.
Another View: Western Digital Through The P/E Lens
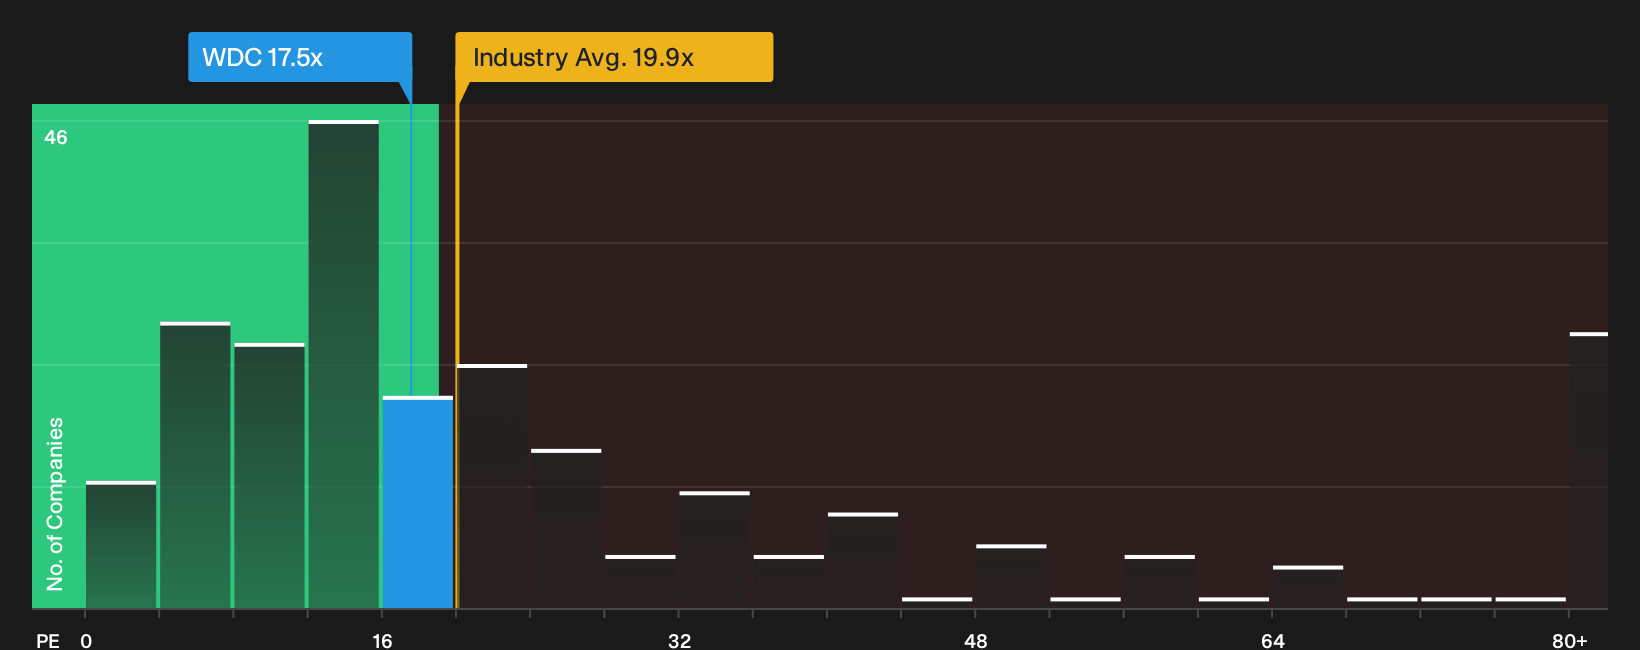
The most followed Western Digital narrative calls the stock 37% overvalued. Yet the current P/E of 17.5x screens cheaper than the global tech average at 19.9x and well below peers near 37.2x, while our fair ratio sits even higher at 46.1x.
That gap between today’s multiple and the fair ratio suggests the market may already be baking in the risk that current margins ease back, rather than assuming the recent AI storage boom lasts unchanged. Which version of Western Digital’s future do you think that P/E really reflects?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about Western Digital after all that. Act quickly, review both sides of the story, then weigh the 4 key rewards and 3 important warning signs.
Looking for more Western Digital sized investment ideas?
Do not stop at Western Digital. Use the Simply Wall Street screener to hunt for fresh opportunities before everyone else chases the same crowded trades.
- Target value first by scanning a curated pool of companies that currently screen as 30 high quality undervalued stocks relative to their fundamentals.
- Prioritise resilience by focusing on businesses in the list of solid balance sheet and fundamentals (24 results) that can better handle shocks without stretching their finances.
- Get in early on under-followed potential by reviewing the 16 high quality undiscovered gems that have quality metrics many investors have not yet priced properly.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com