
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OceanaGold Stock And 2 Canadian Undervalued Stocks
Global bond yields are climbing to multi decade highs, and that move is pulling a lot of attention toward cold, hard cash flow. When borrowing costs rise, investors often look more closely at Canadian businesses that generate solid cash and yet trade at a discount to what their future cash streams suggest. This article highlights three stocks that screen as undervalued on cash flows and explains why they may deserve a closer look.
The three Canadian stocks covered next are only a sample of the opportunities that surfaced, and the full screen flagged 1 more business with equally compelling cash flow stories that are not covered in this article. To go deeper into this idea, head straight into the Undervalued Stocks Based On Cash Flows screener to identify and analyze the highest conviction cash flow plays.
OceanaGold (TSX:OGC)
OceanaGold is a Vancouver based miner focused on producing gold and copper from a cluster of operating assets, with cash flow anchored by its Didipio and Haile mines. Revenue is concentrated at Haile at about $796 million and Macraes at roughly $781 million, with Didipio contributing around $549 million and Waihi about $338 million. The stock carries a market value of roughly CA$8.8b.
OceanaGold gives this cash flow focused screen a real-world backbone, because its producing mines are already throwing off the operating cash that underpins any discounted cash flow view of value.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, and in turn enhance consolidated cash flow and margins."
What really matters now is how one unresolved pressure shapes where those future margins and cash returns ultimately land for shareholders.
That unresolved pressure is exactly what the full narrative for OceanaGold unpacks, separating short term noise from the long term forces that could accelerate OceanaGold's cash story.
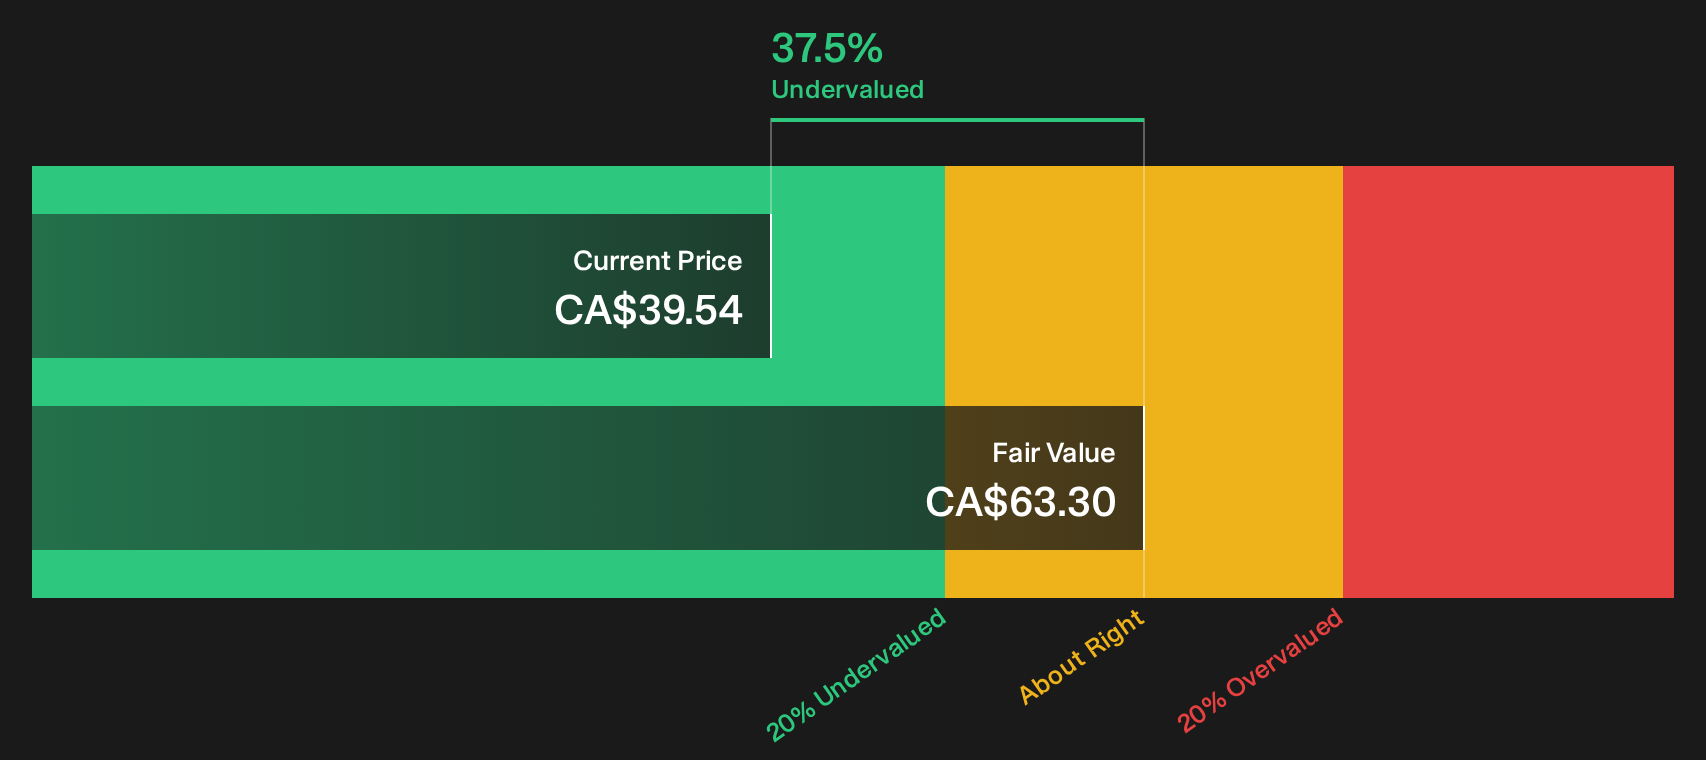
Savaria (TSX:SIS)
Savaria gives this cash flow focused screen a real world angle, because its accessibility equipment and patient handling products turn long term demographic shifts into tangible orders, installations and service work that can be modeled through discounted cash flow rather than pure speculation.
Savaria is a CA$2.1b specialist in mobility and patient handling solutions, with the Accessibility segment generating about CA$739 million and Patient Care contributing roughly CA$209 million in annual revenue, mainly from North America and Europe.
"Ongoing global demographic shifts, namely population aging and increased urban density, are expected to drive a sustained uptick in demand for home accessibility solutions (e.g., elevators, stairlifts). This is anticipated to support Savaria’s revenue over the long term as these trends intensify."
What really shapes the long run cash flow picture for Savaria now is how one quiet pressure on future profitability plays out beneath those demand tailwinds.
That quiet pressure is exactly what the full narrative for Savaria unpacks, mapping how profitability risk, cash generation and valuation could be decoupling in Savaria’s favor over the long run.
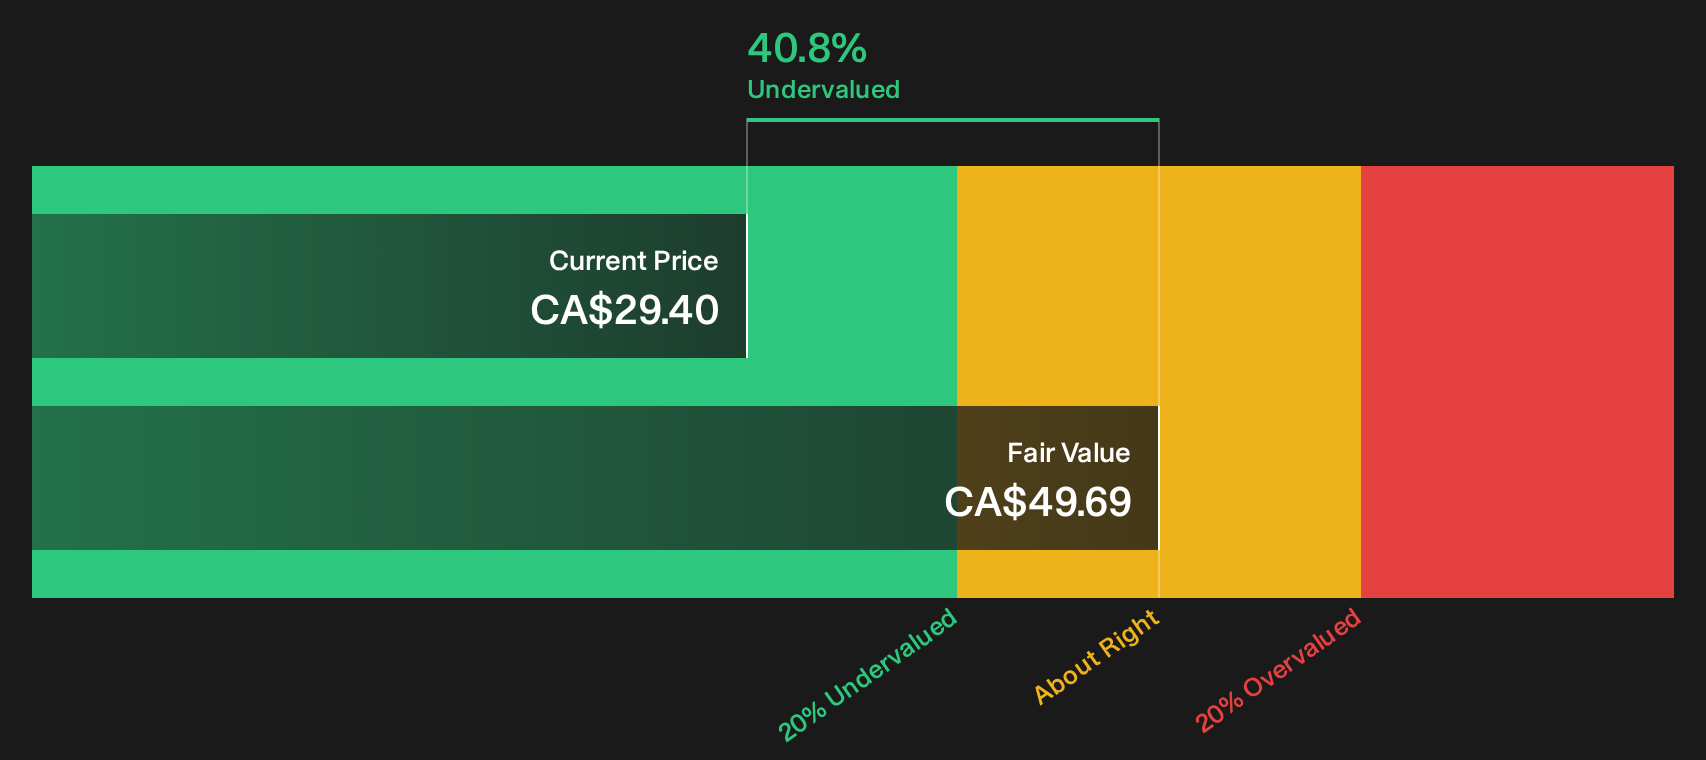
Suncor Energy (TSX:SU)
Suncor Energy is a Calgary based integrated producer that turns long lived Oil Sands bitumen into cash flow, then captures extra economics through refining and fuel retail. Refining and Marketing contribute about CA$36.8b of revenue, Oil Sands about CA$26.9b, Exploration and Production roughly CA$2.5b, and the stock is valued at roughly CA$112.0b.
Suncor Energy taps into this cash flow focused screen through its Oil Sands engine, where long life production backs valuation models with tangible free cash potential, while the downstream network helps smooth out swings in commodity prices.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The real test now is how this pressure on future reliability shapes the gap between today’s cash returns and tomorrow’s margin profile.
To understand how that reliability risk could be masking potential upside in Suncor Energy's cash generation story, read the full narrative for Suncor Energy and identify where the cycle might be turning.

Seeking Fresh Alternatives Before Others?
New ideas move first. By the time momentum is obvious, the best entry points are often gone. Scan these fresh stock themes while they are under the radar and consider them before they become widely followed.
- Identify income workhorses that may offer staying power by checking a curated batch of 1 dividend fortresses before yields potentially get compressed and more investors begin pursuing them.
- Monitor potential automation leaders by scanning 93 robotics and automation stocks while these operators are still treated as niche stories instead of being viewed as part of core infrastructure.
- Review 84 AI infrastructure stocks to evaluate hardware opportunities before spending changes, order activity shifts, and more capital focuses on a narrower group of tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com