
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
MONY Group And 2 British Dividend Stocks To Own
Global bond markets are under pressure as long-term yields in the US and Japan reach multi-decade highs, lifting borrowing costs around the world. For British investors, those higher interest rates make steady income from cash more tempting. That also puts a spotlight on United Kingdom companies that pay sizeable, well covered dividends above 3%. This article walks through three high-yield options from that group that may be worth a closer look.
The three stocks covered below are only a small sample of the opportunity set. The full Dividend Powerhouses screen surfaces 64 more companies that combine higher yields with covered, consistent payouts that are not shown here. To see the broader field and identify which ideas best fit your own income goals, head straight to the Dividend Powerhouses (3%+ Yield) screener
MONY Group (LSE:MONY)
Overview: MONY Group runs MoneySuperMarket, MoneySavingExpert, Quidco and other UK comparison platforms that earn steady commissions and cashback-driven income supporting its dividend profile.
Operations: MONY Group generates about £236.9 million from Insurance, £110.5 million from Money, £54.8 million from Home Services and £49.3 million from Cashback, with £448.1 million of revenue coming entirely from the United Kingdom.
Market Cap: £920 million
MONY Group brings the Dividend Powerhouses theme to life through MoneySuperMarket and its related comparison platforms, where dependable commission inflows help cover a 3% plus yield and underpin a policy of steady payouts to shareholders.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency, evidenced by a 300% improvement in tech productivity and cost reductions from replatforming. This is likely to support sustainable long-term expansion of net margins."
What happens to that income story if one unseen pressure on customer acquisition costs and payout mix starts to bite harder?
If that pressure is building, the full narrative for MONY Group explains how MONY Group’s commission engine, cash returns and customer acquisition trends could be quietly decoupling from headline comparisons.

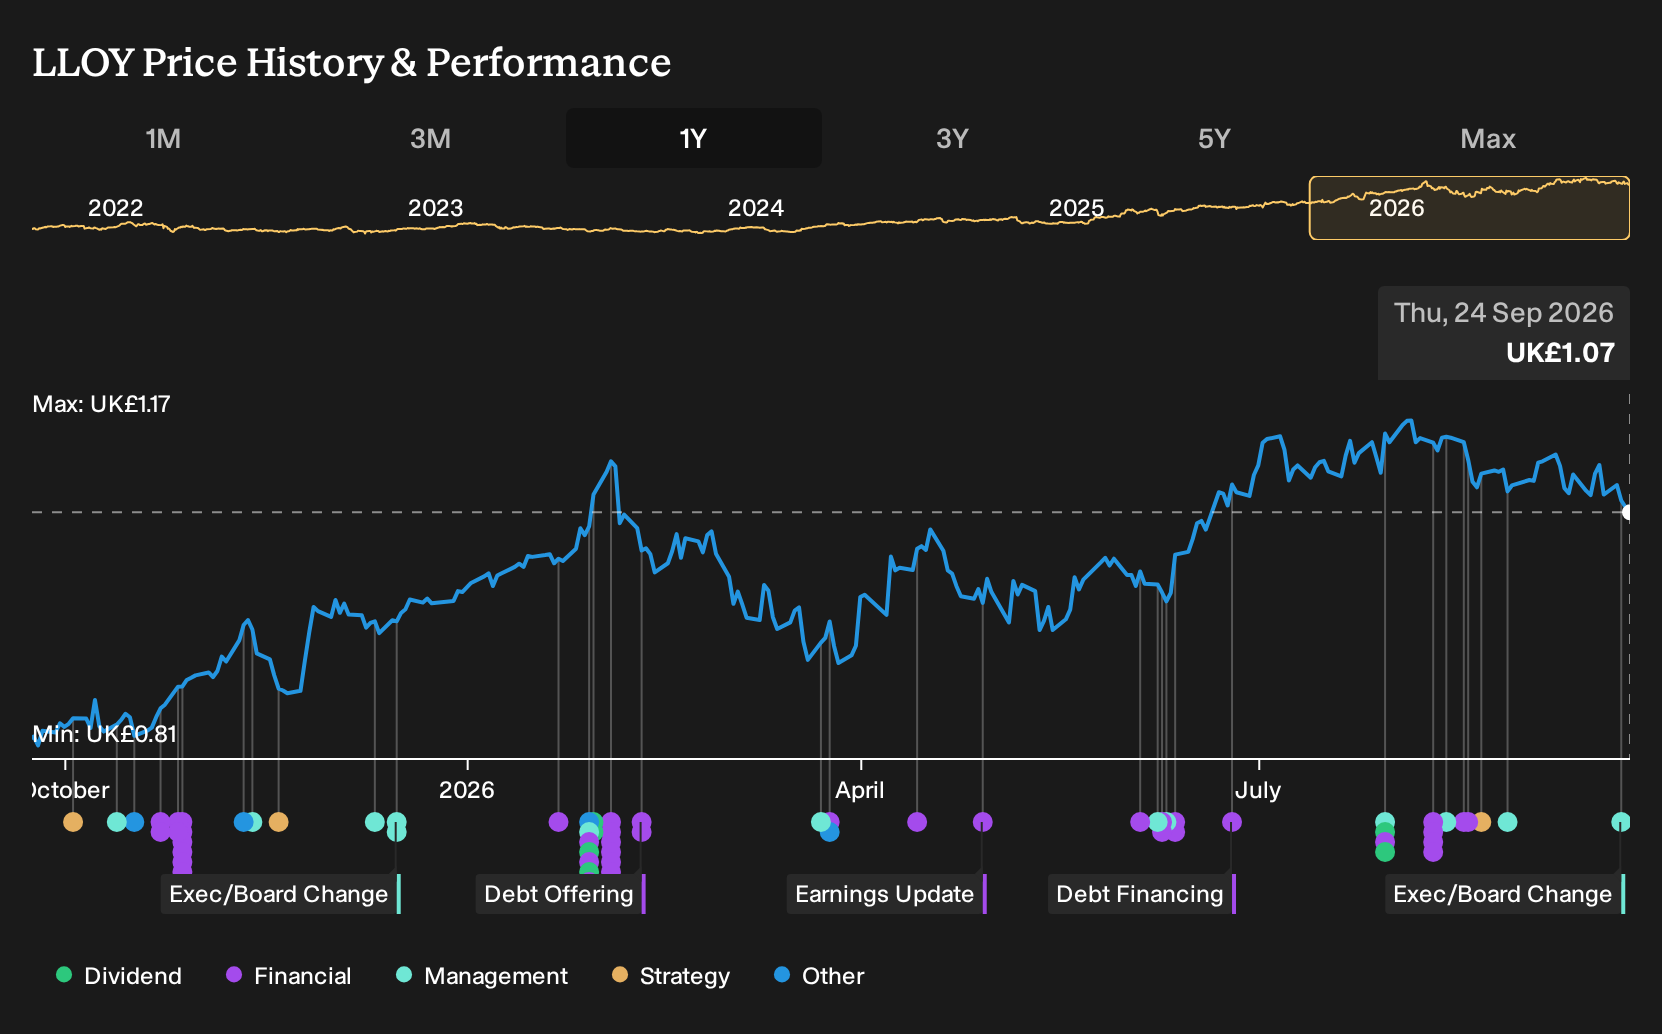
Lloyds Banking Group (LSE:LLOY)
Overview: Lloyds Banking Group is a major UK lender whose retail and commercial banking activities generate the steady cash flows supporting its dividend profile.
Operations: Lloyds Banking Group earns most of its income from Retail including Wealth at £11.9b and Commercial Banking at £5.7b, with £1.4b from Insurance, Pensions and Investments.
Market Cap: £61.6b
Lloyds Banking Group matters for dividend seekers because its everyday banking franchises generate cash that can support a covered income stream even when the wider sector feels more cyclical.
"Digital transformation, including expanding mobile-first services for 21 million users, rolling out a new digital remortgage journey, and leveraging AI innovation, continues to drive operating cost reductions and enhances efficiency, positioning the company to support sustained long-term margin expansion and higher earnings."
What really tests that dividend story is how one unresolved pressure on loan quality and provisions eventually feeds through to those earnings.
If that pressure is building, the full narrative for Lloyds Banking Group shows how loan quality, digital efficiency and capital returns could be quietly re-rating Lloyds Banking Group’s income story.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is a London based asset manager that runs income focused infrastructure funds alongside private equity and venture strategies.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, largely across the United Kingdom and Australia.
Market Cap: £471 million
Foresight Group Holdings matters for this Dividend Powerhouses screen because its income focused infrastructure platforms are built around long term, contract based cash flows that can support covered, growing distributions.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens to that dividend story if one unseen pressure on fee margins and fundraising momentum starts to reshape those cash flows?
If that pressure is rising, the full narrative for Foresight Group Holdings explains how fee resilience, capital recycling and investor demand could be quietly contributing to Foresight Group Holdings’ income potential.

Seeking Fresh Alternatives For Your Income?
Fresh opportunities do not sit still. Breakout themes gain momentum while others get caught dropping off the radar. Scan under the radar for now, act now.
- Spot potential turnaround stories early by scanning the 10 high quality undervalued stocks that filter for strong cash generation and balance sheet strength before the crowd fully catches on.
- Ride structural tech momentum by reviewing the 84 AI infrastructure stocks built around businesses supplying the hardware, energy and data backbone behind AI demand growth.
- Track future industrial demand by checking the 17 top copper producer stocks focused on established producers that could benefit if electrification and grid spending keep building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com