
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hess Midstream (HESM) Stock May Trade At A Discount On Payout Rise
Hess Midstream has delivered a strong 5 year share price run, yet its recent pullback and shifting fundamentals leave an open question about whether today's valuation is still backed by its earnings power. For anyone looking at the pipeline operator now, the core issue is how that price stacks up against what the business earns and can reasonably sustain.
- The stock has returned 100.9% over the past 5 years, which puts real pressure on the current earnings base to justify where the share price now sits.
- Management has raised the quarterly payout even as net income and volumes in key throughput categories have declined, which can focus attention on how resilient earnings and fee-based cash flows need to be to support that stance.
- The analysts covering Hess Midstream have run their own numbers. See what analysts think Hess Midstream's shares could be worth.
The issue now is whether Hess Midstream's current share price is adequately supported by the earnings the partnership is generating today.
If you want to stress test the same earnings question that hangs over Hess Midstream across a wider field, scan companies in the 30 high quality undervalued stocks
Is Hess Midstream a Bargain on Earnings?
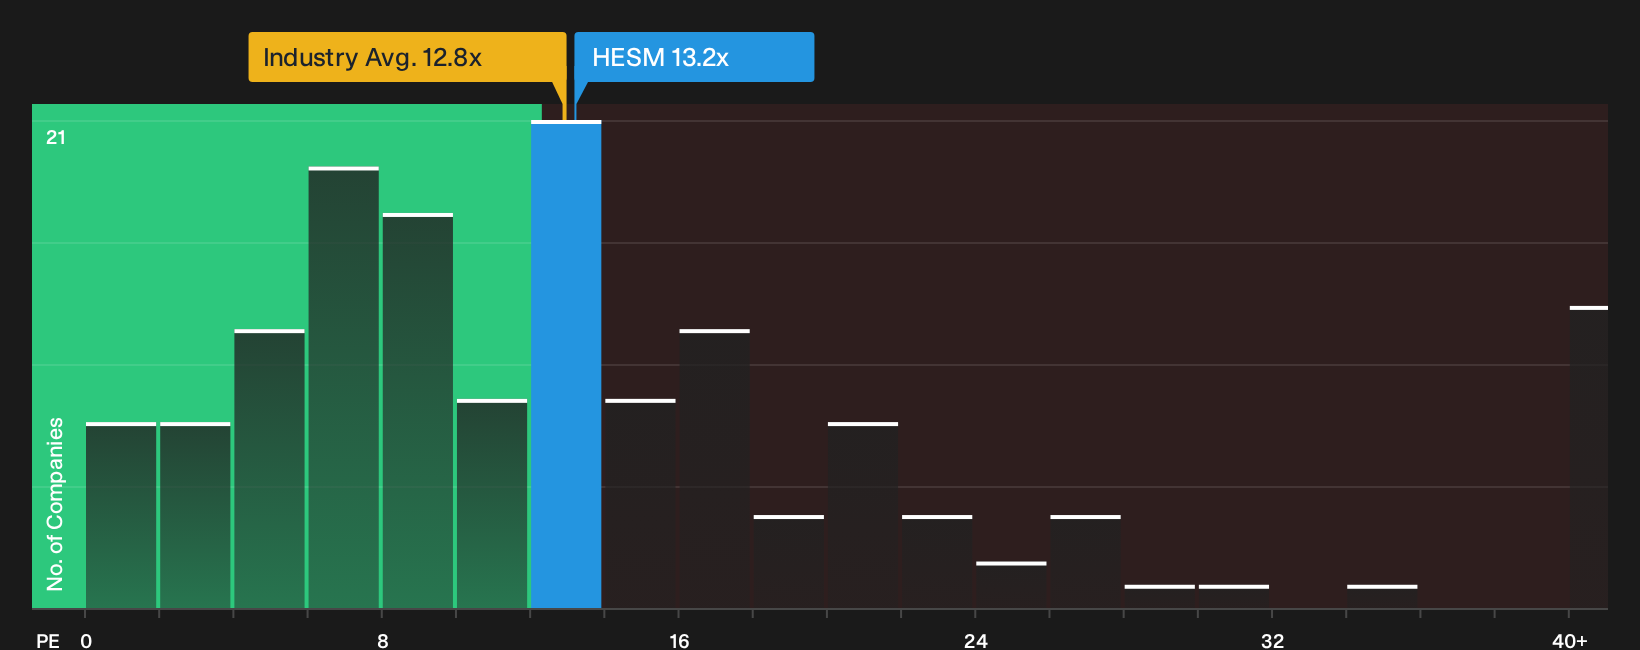
P/E fits Hess Midstream because earnings are the key pool of cash that supports its distributions and underpins what unitholders are really paying for. On that lens, the stock trades on about 13.2x earnings, which is close to the wider Oil and Gas sector at roughly 12.8x. Compared with the peer group on around 20.6x, the partnership changes hands on a noticeably lower earnings multiple.
Recent news around higher payouts despite softer net income and throughput means the market is already weighing how dependable those profits are. Yet the current P/E still sits below what a tailored model suggests would be typical for Hess Midstream given its profile. That gap points to a valuation that screens as undervalued on this metric, even after accounting for sector risks and the partnership structure. Explore the numbers behind Hess Midstream's P/E valuation.
The Hess Midstream Narrative: What Would Justify Today's Price?
Narratives pick up where this P/E puzzle leaves off for Hess Midstream by spelling out which paths for earnings, margins and throughput would need to hold for the units to be worth meaningfully more or less than today. Each one treats fair value as a specific, testable storyline about the partnership's cash generation that you can track over time, and they live on Simply Wall St's Community page.
One of the top community narratives on Hess Midstream: roughly fairly valued
"The current valuation implies the market already treats Hess Midstream as fairly valued with a focus on steady distributions and excess free cash flow..."
Discover why this Narrative puts Hess Midstream at roughly fairly valued.
One more Hess Midstream check that belongs beside the earnings lens
Price and P/E only tell part of the story for Hess Midstream, because the research screen has also flagged specific risk checks that deserve a look before you lean on any valuation takeaway. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com