
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undervalued Small Caps In Global With Insider Action
In recent weeks, the global markets have been marked by volatility, with small-cap stocks in the Russell 2000 Index lagging behind their larger counterparts amid rising interest rates and geopolitical tensions. As investors navigate these turbulent conditions, identifying undervalued small-cap companies with insider activity can offer potential opportunities for those looking to capitalize on market inefficiencies and strategic insights.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| China Aircraft Leasing Group Holdings | 7.2x | 1.0x | 36.31% | ★★★★★☆ |
| Transcontinental | 2.4x | 0.2x | -95.51% | ★★★★☆☆ |
| Franchise Brands | 27.3x | 2.0x | 47.47% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 13.55% | ★★★★☆☆ |
| Saniona | 7.4x | 3.2x | 31.13% | ★★★★☆☆ |
| Linc | 12.1x | 12.6x | 34.15% | ★★★★☆☆ |
| Diversified Royalty | 25.3x | 10.0x | 46.50% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 22.33% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -217.03% | ★★★☆☆☆ |
| Coveo Solutions | NA | 1.8x | -20.29% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
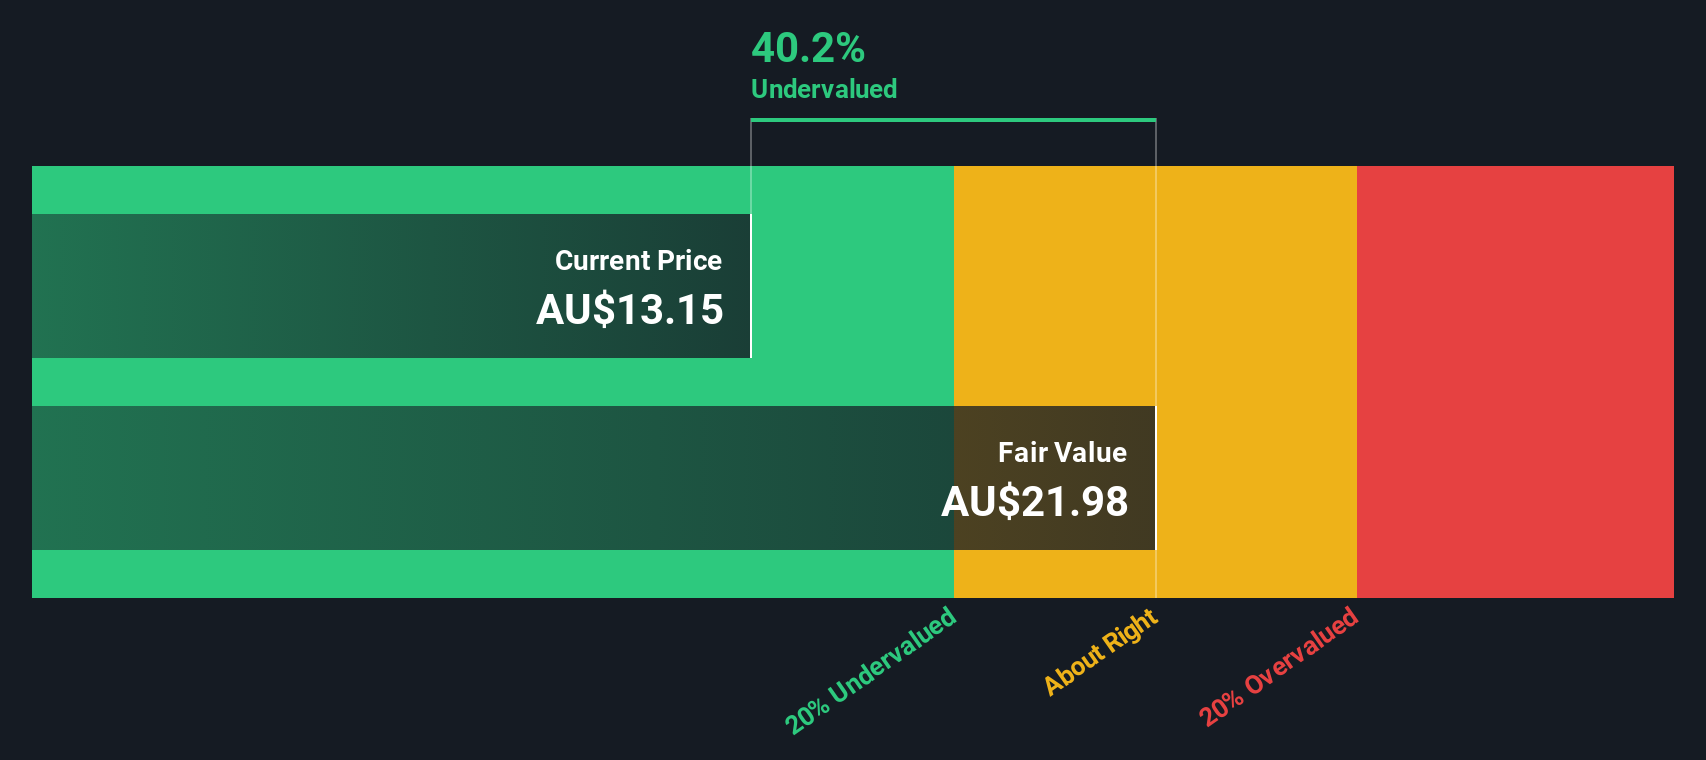
Credit Corp Group (ASX:CCP)
Simply Wall St Value Rating: ★★★★★☆
Overview: Credit Corp Group is a financial services company specializing in debt ledger purchasing and consumer lending, with operations in Australia, New Zealand, and the United States, and a market capitalization of A$2.15 billion.
Operations: Credit Corp Group generates revenue primarily from debt ledger purchasing in the United States and Australia/New Zealand, as well as consumer lending in Australia and New Zealand. The company's net income margin has shown variability, with a peak of 27.61% in December 2021 and a recent decline to 13.36% by June 2024. Operating expenses are significant, with general and administrative costs consistently forming the largest portion of these expenses.
PE: 9.2x
Credit Corp Group, a smaller company in the financial sector, has shown promising earnings growth with net income rising to A$105.51 million for the year ending June 2026 from A$94.1 million previously. Despite relying solely on external borrowing, which adds risk, they project NPAT between A$110 million and A$118 million for FY2027. Insider confidence is evident through share purchases over recent months. The company's dividend increase and guidance suggest potential growth despite challenging US market conditions.
- Navigate through the intricacies of Credit Corp Group with our comprehensive valuation report here.
Examine Credit Corp Group's past performance report to understand how it has performed in the past.
Hanza (OM:HANZA)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Hanza is a manufacturing solutions provider that offers comprehensive services in electronics and mechanics, with a market cap of approximately SEK 2.5 billion.
Operations: Hanza's revenue primarily stems from its Main Markets and Other Markets segments, with the Main Markets contributing SEK 5.32 billion and Other Markets adding SEK 3.13 billion. Over recent periods, the company's gross profit margin has seen fluctuations, reaching as high as 44.98% in June 2026 before slightly declining to around 44.78% by September of the same year. The cost of goods sold (COGS) is a significant expense impacting profitability, consistently increasing alongside revenue growth over time.
PE: 28.5x
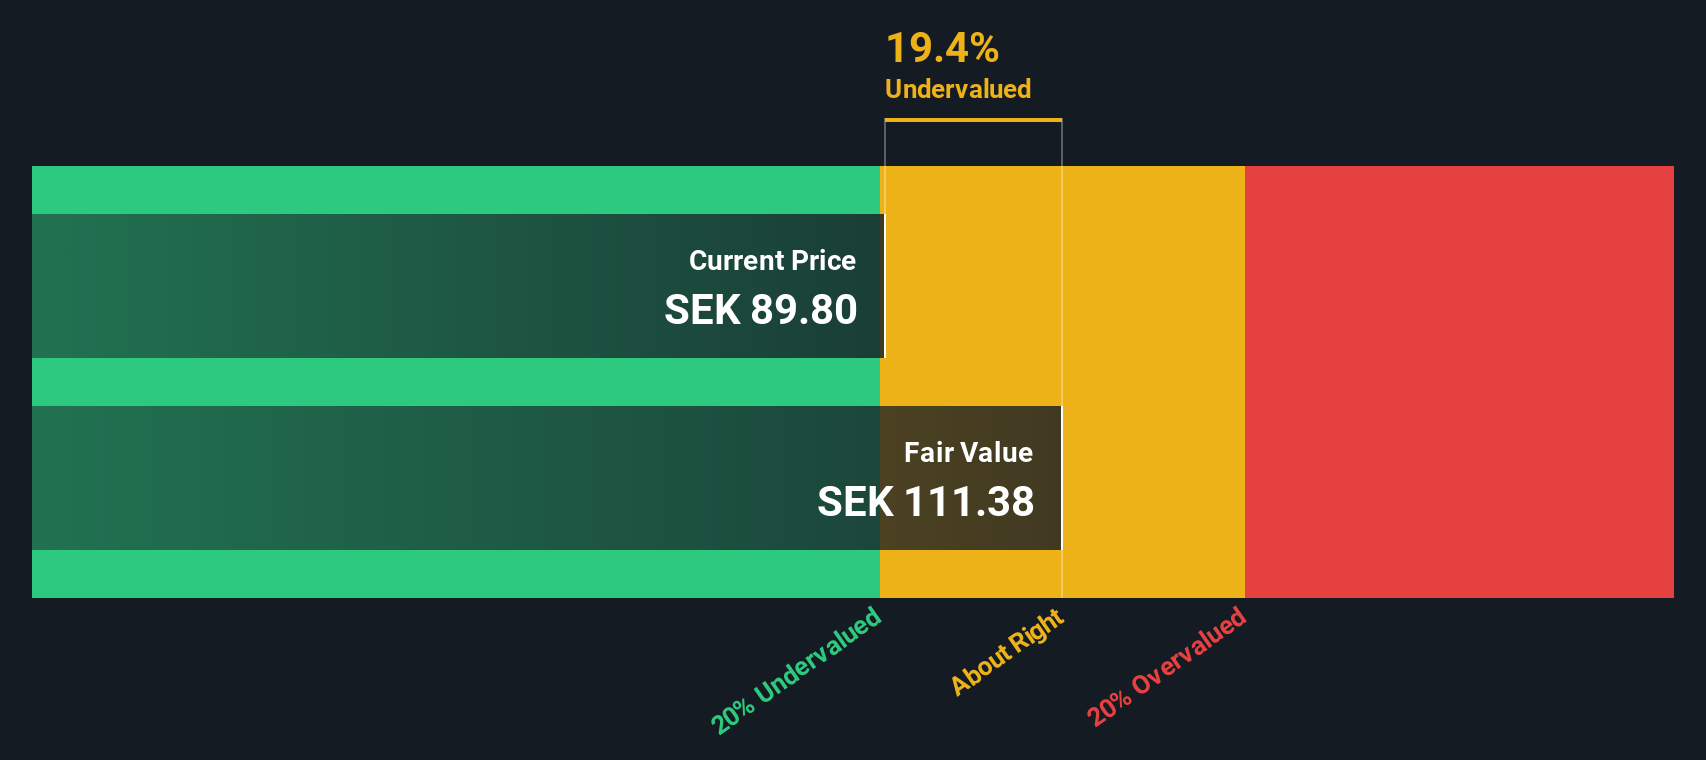
Hanza, a manufacturing solutions provider, is navigating its growth through strategic restructuring and share repurchases. Despite past shareholder dilution, the company forecasts a 32.64% annual earnings growth. Recent buybacks of up to 150,000 shares aim to optimize capital structure and support acquisitions. For Q2 2026, sales surged to SEK 2.6 billion from SEK 1.5 billion year-over-year, while net income rose slightly to SEK 54 million. The Horizon program's reorganization efforts could enhance operational efficiency across Europe by year's end.
- Delve into the full analysis valuation report here for a deeper understanding of Hanza.
Assess Hanza's past performance with our detailed historical performance reports.
Coveo Solutions (TSX:CVO)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Coveo Solutions is a technology company specializing in AI-powered search and recommendation software, with a market cap of approximately CAD $0.73 billion.
Operations: Coveo Solutions generates revenue primarily from its Software & Programming segment, with the latest reported figure at $151.34 million. The company has observed fluctuations in its net income margin, recently recording a figure of -12.97%. Operating expenses are significant, including costs related to sales & marketing and research & development. The gross profit margin shows variability but was last noted at 78.16%.
PE: -14.0x
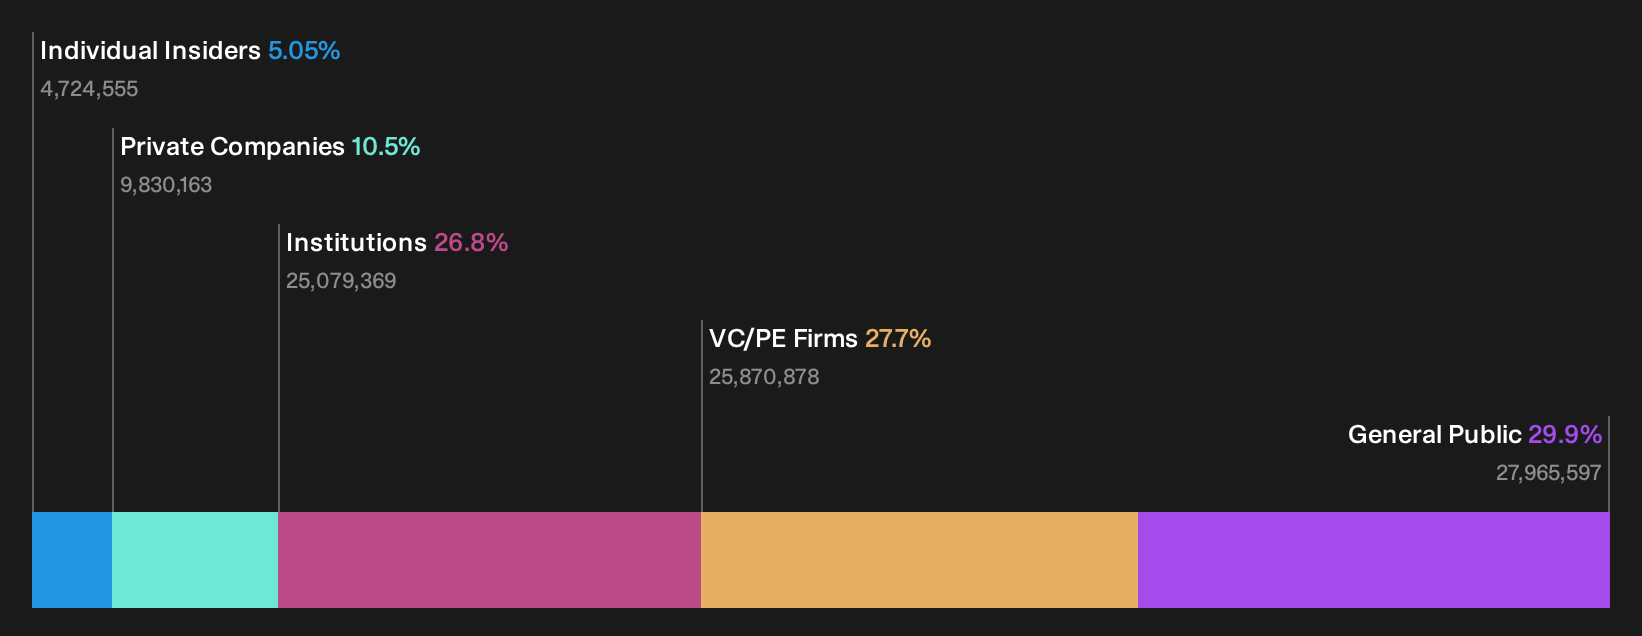
Coveo Solutions, a smaller company in the tech space, has shown potential with its recent financial performance. For the quarter ending June 30, 2026, revenue rose to US$38.55 million from US$35.55 million a year earlier, while net losses narrowed significantly to US$5.81 million from US$15.05 million previously. Despite being unprofitable and reliant on external borrowing for funding, insiders have demonstrated confidence by purchasing more shares recently. The company's guidance anticipates revenues between US$39.7 million and US$40.2 million in the upcoming quarter, suggesting steady growth amidst ongoing challenges.
- Click to explore a detailed breakdown of our findings in Coveo Solutions' valuation report.
Gain insights into Coveo Solutions' past trends and performance with our Past report.
Summing It All Up
- Dive into all 122 of the Undervalued Global Small Caps With Insider Buying we have identified here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com