
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Kiosk Launch Require Action From Zebra Stock Investors?
- Zebra Technologies launched the KC401 self-service kiosk, a 10 inch, IP65 sealed device aimed at reducing queues and routine inquiries across retail, hospitality, manufacturing, and healthcare.
- The KC401 leverages shared infrastructure with Zebra’s CC6000 and integrates Elo solutions, which may lower upgrade costs and broaden use cases across high traffic, hygiene sensitive sites.
- We will now look at how Zebra Technologies' investment narrative could be affected by the KC401 self service kiosk launch.
Scan how Zebra Technologies fits into the broader push for automation by comparing it with 93 robotics and automation stocks shaping self-service and efficiency across warehouses, shop floors, and clinical settings.
Zebra Technologies Investment Narrative Recap
To own Zebra Technologies, you need to believe in a long run shift toward automated, data driven workflows in retail, logistics, manufacturing, and healthcare, with Zebra supplying much of the on the ground hardware and software. The KC401 launch fits that story, but on its own it looks like an incremental product extension rather than a major short term swing factor.
The near term swing issue still looks tied to hardware demand recovery in softer regions like EMEA and manufacturing, plus how quickly Zebra can grow software and services from a modest base. Key risks remain high debt, tariff exposure, and intense competition in customer facing kiosks and point of sale, where Elo pushes Zebra further into crowded markets.
The most relevant recent development is Zebra Technologies taking the KC401 and tying it tightly to the Elo portfolio. That creates a broader kiosk and touchscreen offering that can be dropped into high traffic locations, using existing CC6000 infrastructure to limit disruption for current clients and potentially shorten deployment cycles for upgrades.
For you as an investor, the interest sits in execution. Strong adoption of the KC401 across retail, hospitality, and healthcare would support the automation and IoT catalyst. Slow uptake would keep Zebra more reliant on traditional printers and mobile computers. Given heavy R&D and acquisition spend, any gap between expected and actual cross selling could pressure cash flow and margins.
What The KC401 Means Against Zebra Technologies' Forecasts
Zebra Technologies' narrative projects US$7.2b revenue and US$991.3m earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings increase of about US$452.3m from current earnings of US$539.0m.
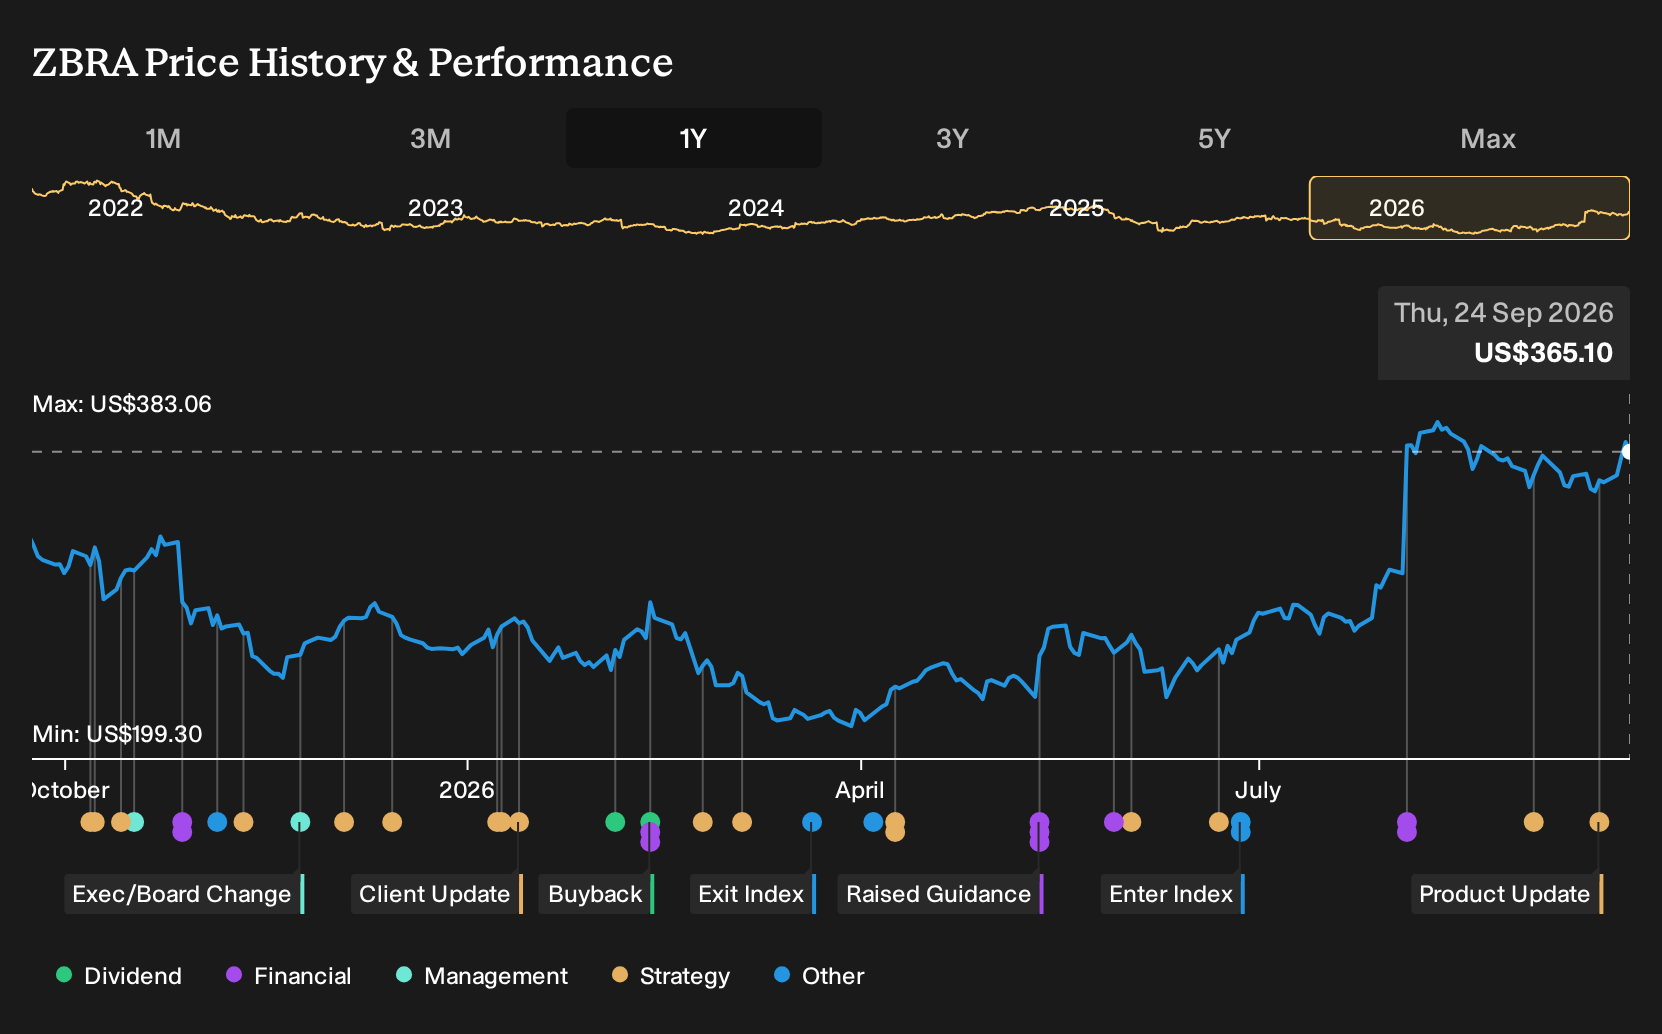
Uncover how Zebra Technologies' fair value indicates a 9% potential upside to its current price before other investors start pricing in that gap.
Exploring Other Perspectives
Some of the most optimistic analysts frame the KC401 in the context of a faster shift toward software and recurring revenue at Zebra Technologies. Before this launch, the bullish camp was already penciling in US$7.3b revenue and US$1.1b earnings by 2029. You can see how a kiosk that deepens automation could push those expectations higher or prompt reassessment as adoption data emerges.
Explore 4 other Zebra Technologies fair value estimates, including one that suggests as much as 46% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zebra Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zebra Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zebra Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Zebra Technologies?
If the KC401 story has you thinking more broadly about where automation and data heavy workflows can create value, it can help to line Zebra Technologies up against a wider watchlist using the Simply Wall St Screener.
- For investors focused on value and quality together, scan a curated set of companies that combine strong fundamentals with potentially mispriced share prices through the 30 high quality undervalued stocks.
- If capital preservation and smoother returns matter most to you, filter for businesses that carry sturdier balance sheets and steadier profiles via the 30 resilient stocks with low risk scores.
- When you want ideas that are less crowded by attention, look across a universe of under the radar opportunities with solid financial traits using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com